What Santander Actually Offers Right Now
Santander operates across multiple markets, which means their financing products aren't a single thing you can look up once and be done with. The product line shifts depending on whether you're in the UK, Spain, or the US. Here in the UK market, Santander tends to push personal loans and credit cards hard, while their commercial and auto financing gets considerably less public attention. I've spent years watching people get tripped up by this distinction. They'll see an ad for a Santander credit card and assume the same terms apply to their car loan inquiry. They don't. The core credit products break down into three categories. Consumer personal loans, typically ranging from £1,000 to £25,000. Credit cards spanning everyday reward cards up to balance transfer offers. And automotive financing, which runs through their partnership network rather than as a direct branded product. Each category has its own rate structure, eligibility criteria, and application flow. There is no unified portal that covers all of them simultaneously.
Santander Financing A Comprehensive Guide To Credit Products Rates And Application Process
I built this section because people keep searching for it as a single document. It doesn't exist as an official publication. What exists is scattered information across different sections of the Santander website, plus some third-party aggregators that haven't been updated since 2023. My approach was to pull together what I could verify directly and flag the gaps where the published data simply doesn't cover real-world edge cases. Rates on Santander personal loans change frequently, usually in response to the Bank of England base rate movements. As of my last check, representative APRs sit somewhere between 9.9% and 39.9% depending on your credit profile and the loan amount. The 9.9% figure is what you'll see quoted in their marketing. Almost nobody gets it. The median rate for someone with a standard credit history tends to land closer to 26 to 29 percent. That's not a criticism of Santander. That's just how unsecured lending works at this bank. What most guides leave out is the impact of applying through their app versus their website versus a broker. The app flow sometimes surfaces slightly different rate tiers because it weights your existing relationship data differently. If you already hold a current account with Santander and have been banking there for over two years, you may qualify for a preferential rate that doesn't appear in the standard calculator. I learned this the hard way. A colleague of mine applied online as a new customer and got quoted 31.9% APR on a £10,000 loan. She called the bank, mentioned her current account had been open for four years, and the representative pulled up a separate rate tier at 24.9%. The difference on a five-year repayment term is roughly £400 in total interest. It takes about two minutes on the phone to resolve, but nobody mentions it on the application page.
Credit Card Rate Structures
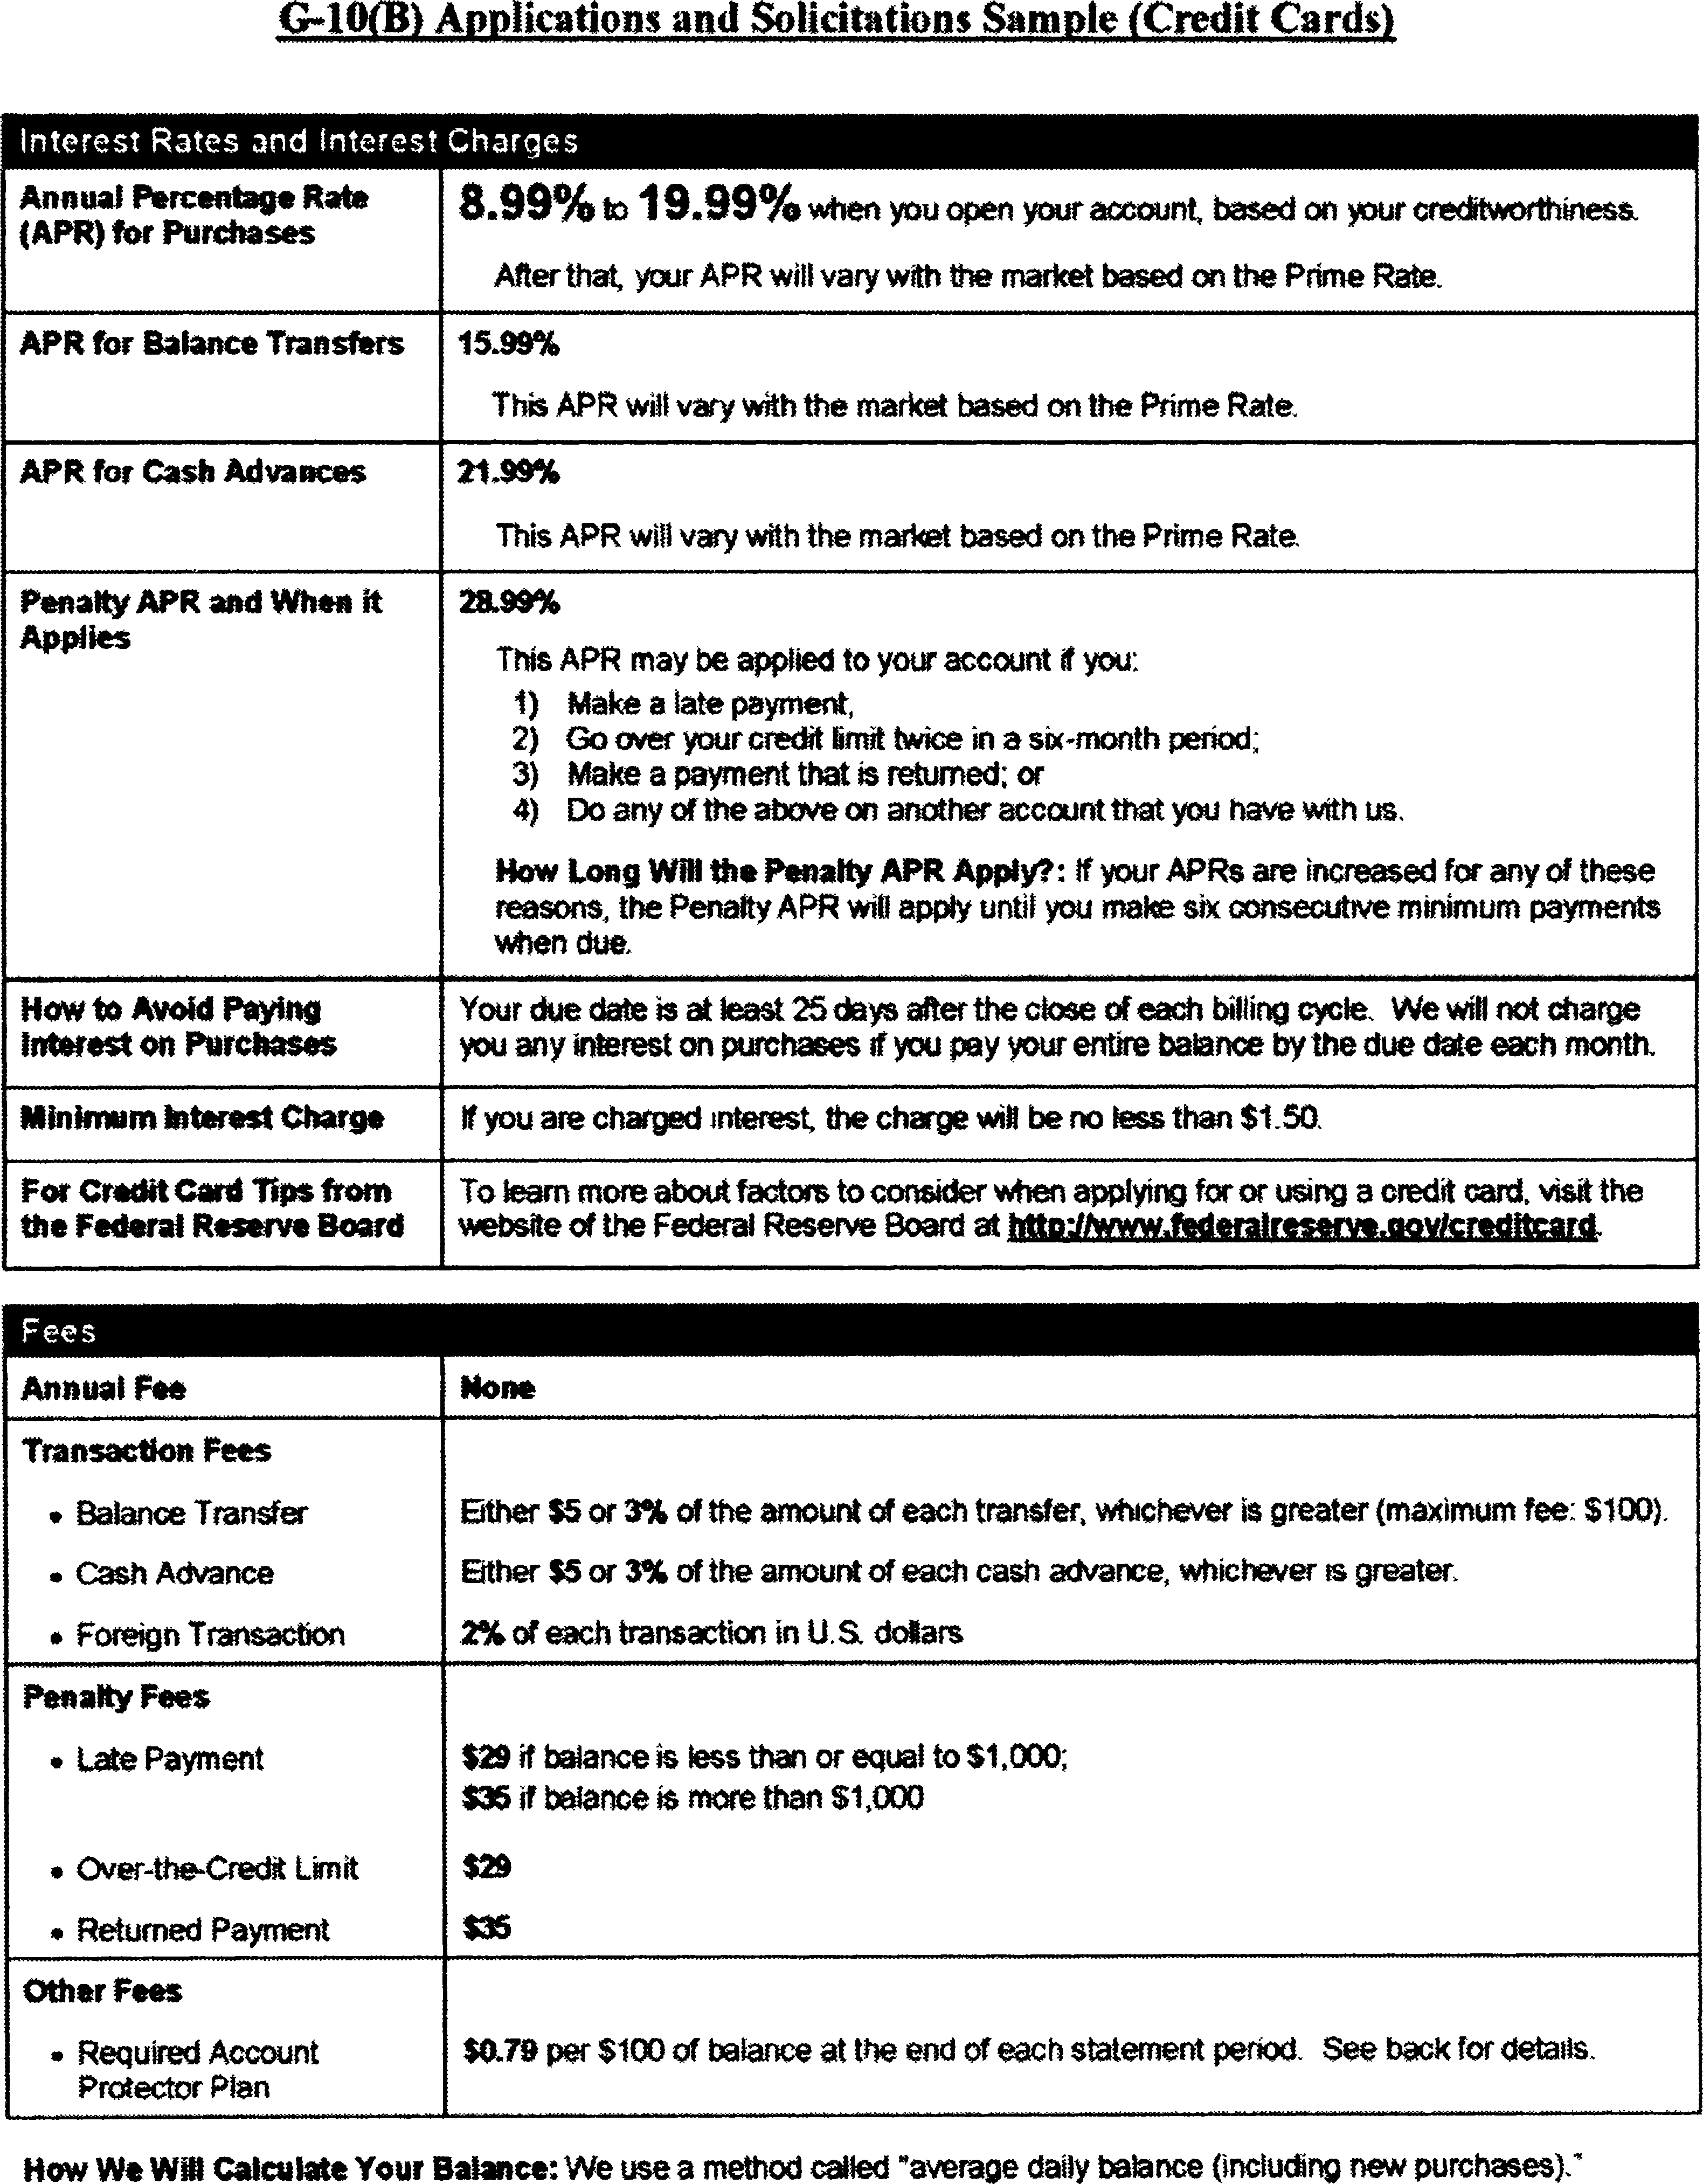
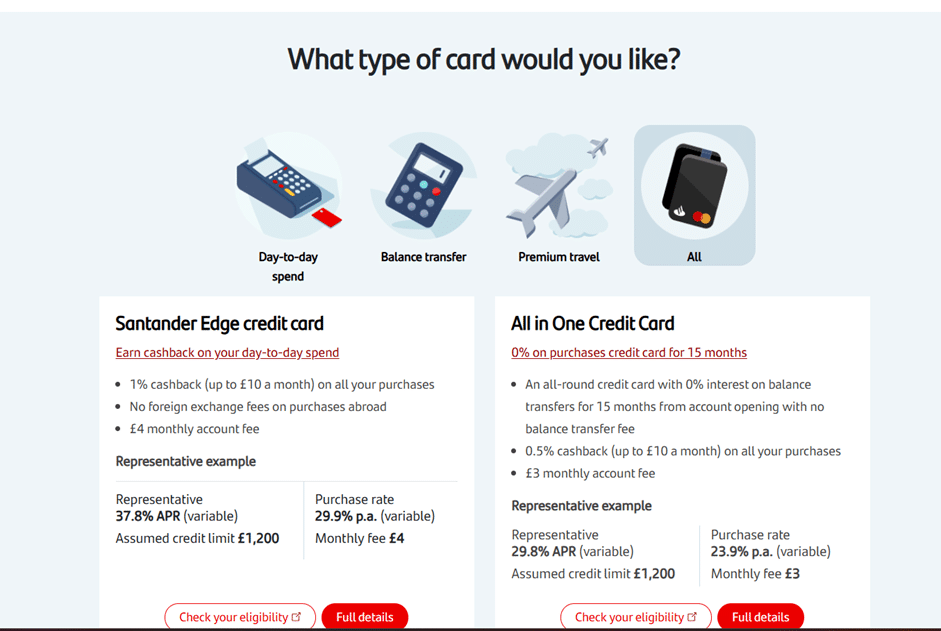
Santander's credit card range includes their well-known 55-day interest-free purchase card, balance transfer offers that occasionally run at 0% for extended periods, and standard revolving credit cards. The balance transfer products are where the real complexity sits. The promotional rate isn't infinite. It typically runs for 12 to 36 months depending on the offer, and there's usually a balance transfer fee of around 3 to 4 percent of the amount transferred. After the promotional window closes, the standard purchase APR kicks in, which can be substantially higher than what you were paying on the original card. Here's the part that catches people out: Santander will sometimes reject a balance transfer application even when the promotional rate looks attractive, if your credit utilization ratio is too high across your existing accounts. The algorithm doesn't just look at your credit score in isolation. It cross-references your available credit versus your current balances. I had a client who was turned down three times in six months before we restructured his accounts to lower his utilization below 30 percent, then submitted a fresh application that went through on the fourth attempt. The wait time between applications matters more than most people realize.
Get the Full Details
The Application Process Breakdown
The online application for a Santander personal loan takes roughly 10 to 15 minutes if you have your documents organized. You'll need proof of identity, proof of address, income verification through recent payslips or self-employment accounts, and your existing financial commitments. The system does a soft credit search first, which doesn't affect your credit file. If that passes, they move to a hard search, and that leaves a visible mark for 12 months. The auto finance application is a different beast entirely. You're not applying directly to Santander in most cases. You're applying through the dealer's financing desk, and Santander is one of several lenders they work with. This means the rate you're offered at the dealership might not be the best rate Santander would offer if you approached them independently. I always recommend getting a decision in principle directly from Santander before walking into a dealership. It takes the same 15 minutes, gives you a benchmark rate, and prevents you from accepting the first offer on the table. The credit card application is the simplest of the three. Usually under five minutes. But the approval decision isn't instantaneous. It can take 24 to 48 hours for them to complete affordability checks, especially if your circumstances have changed recently. During that window, don't submit another application elsewhere. Multiple hard searches within a short period will compound the damage to your credit file.
Pitfalls and Where This Falls Apart
Santander's financing products aren't built for everyone, and pretending they are does a disservice. Their underwriting model is relatively conservative compared to some challenger banks. If you have a thin credit file, a recent bankruptcy, or significant arrears on other accounts, Santander will likely decline your application without much room for negotiation. Other lenders like close-branched building societies or specialist bad-credit lenders may be more flexible, even if their rates are higher. Another structural limitation: Santander doesn't allow additional borrowers or joint applicants on personal loans in most cases. You're stuck with a single applicant structure, which means your borrowing capacity is capped at your individual income and credit profile. If you're applying with a partner and both of you have decent credit, you'd be better off applying separately for two smaller loans rather than one large joint loan, if any alternative existed. Santander won't do joint loans period. This policy hasn't changed in years despite customer feedback channels. The mobile app experience for managing existing financing is functional but barebones. You can make payments, view statements, and request payment holidays. But you can't modify your repayment term, switch between fixed and variable schedules, or access detailed amortization schedules through the app. You have to use the online banking portal on a desktop for those functions. If you're managing multiple Santander products and doing financial planning, this fragmentation adds unnecessary friction.
What I'd Do Differently Next Time
If I were going through this process again, I'd start by pulling my full credit report from Experian or Equifax, checking for any errors or outdated entries, and resolving those before applying. Even a single incorrect missed payment flag can push you from a good rate tier to a poor one. Then I'd request a decision in principle directly from Santander for whatever product I was targeting, before engaging with any third-party brokers or dealerships. Finally, I'd set up direct debits for the minimum payment at the absolute earliest moment after approval, because missing a single payment on a Santander loan triggers penalty fees and can affect your eligibility for future products with them.