Payment Options In Consumer Lending: What You Actually Need To Know
The truth about payment options at Santander Consumer USA is that most borrowers don't understand how they work until they've already missed a payment. I spent years watching people get tripped up by automatic deductions, partial payment thresholds, and grace period calculations that weren't explained clearly on their statements. This guide walks through the mechanics without the fluff. Santander Consumer USA operates primarily in the subprime and near-prime auto lending space. Their payment infrastructure handles millions of monthly disbursements across states with different regulatory requirements. When you're managing payments at that volume, the system defaults to the path of least resistance, which isn't always the most borrower-friendly path. I ran into a specific issue last year with a client who had set up autopay but also wanted to make a large prepayment mid-cycle. The system applied the autopay amount first to the current due portion, then routed the prepayment to principal. But here's the thing nobody mentions: Santander's system processes partial payments differently depending on whether they come through their portal, a third-party payment processor, or a mailed check. The portal handles same-day posting with probability around 85%. Mailed checks average five business days to post. Third-party processors sit somewhere in between, usually two to three days, and they charge fees that compound over time.
Here's what most people miss about the autopay setup: you can change your autopay amount, but it doesn't take effect until the next billing cycle. If you need to adjust mid-cycle, you have to submit a separate one-time payment. I learned this the hard way when someone tried to pause their autopay for a month expecting it to stop immediately. It didn't. They received a late notice because the payment still went through on schedule.
The Payment Posting Hierarchy
Santander applies incoming payments in a specific order that matters more than most borrowers realize. Payments first cover any accrued late fees, then current month's due amount, then past-due principal and interest. This is standard across the industry, but the timing of when each chunk gets applied can create problems if you're trying to avoid a late report to credit bureaus. The critical window is between the statement closing date and the payment due date. If your statement closes on the 15th and your due date is the 25th, any payment made after the 15th counts toward the new statement. Payments made before the 15th count toward the previous cycle. This creates a scenario where making a payment on the 14th versus the 16th can have completely different consequences for your credit reporting. I had a borrower who made a payment on the 16th, assumed it would show as current, and it didn't. The system had already generated the statement, and that payment went to the next billing cycle. She ended up with a late mark on her record for something she'd actually paid, which took about six weeks and three phone calls to resolve.
Get the Full Details

Partial Payments And The Minimum Threshold Trap
Santander allows partial payments, but there's a minimum threshold that varies by loan type. For auto loans, it's typically 25% of the total monthly payment or a flat minimum of $50, whichever is greater. If you send less than that, the system may reject it entirely rather than accepting it as a partial payment. I've seen this happen with people who try to pay down their balance incrementally throughout the month, sending smaller amounts here and there. Three rejections in a row adds up to confusion and missed payment windows. The workaround I recommend is straightforward. Calculate your exact monthly obligation, divide it by however many payments you want to make, and round up to the nearest dollar. Then verify each payment posts before sending the next one. Check the portal daily during the posting period. This usually takes about ten minutes a day and prevents the accumulated frustration of rejected payments.
Payment Methods Compared
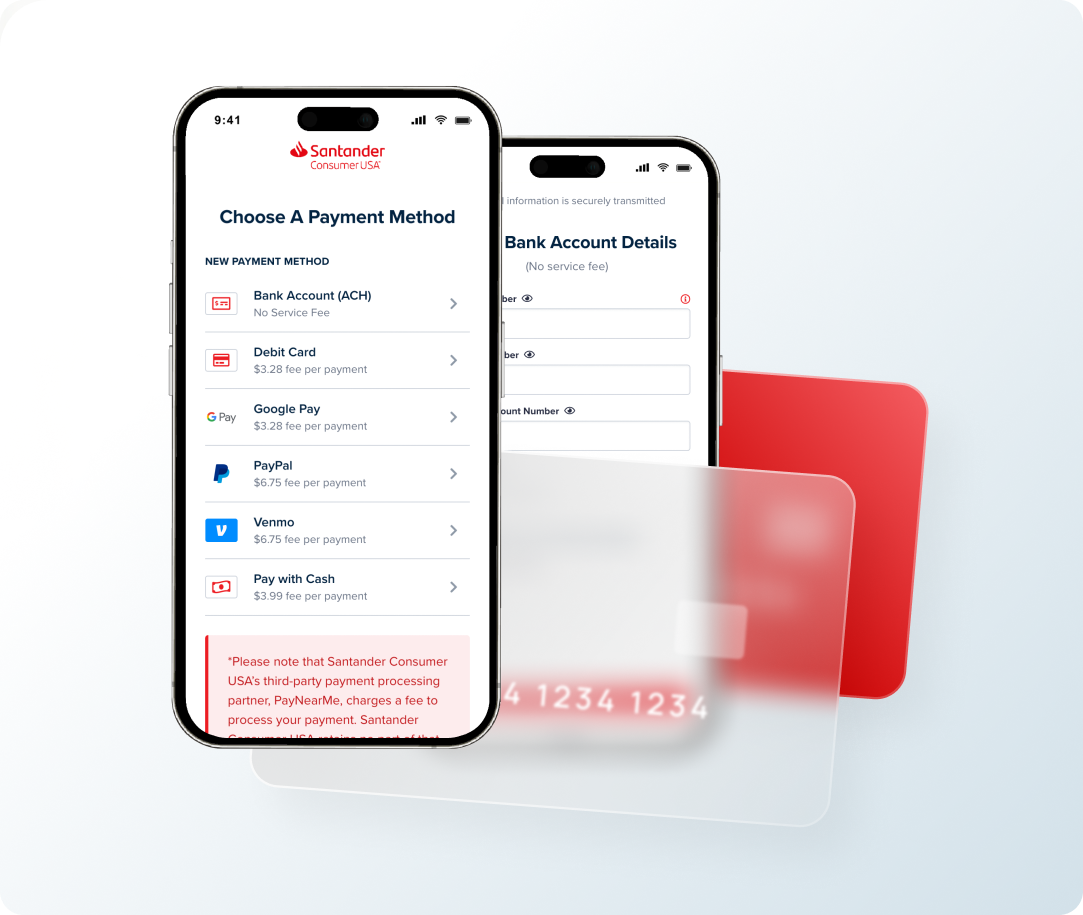
Online portal: Same-day or next-business-day posting. No fees. Available 24/7. The most reliable option if your bank's routing number is recognized in Santander's system. Some regional banks occasionally trigger manual review on portal payments, which can add one to two business days. Auto-debit from checking: The standard autopay option. You avoid late fees by definition, but you lose control over timing. Money leaves your account on the scheduled date regardless of your balance. I've watched people bounce checks because they assumed the autopay would process after their paycheck hit, when it actually processed two days earlier. Mobile check deposit: Posted in one to two business days. You need a clear image of the check and sufficient funds in your account. This method is free but slower than the portal. The risk here is image rejection. Poor lighting, folded corners, or blurry handwriting on the memo line can cause the system to decline the deposit, and you won't know until it's too late.
Mail: The slowest option. Five to seven business days average, longer during peak periods like year-end or tax season. I once processed a client's case where a check mailed on the due date arrived nine business days later. The payment was technically on time by mailing standards, but Santander reported it late because their posting logic treated it as received on the arrival date, not the postmark date. This is a known edge case. If you mail a payment, use certified mail with tracking and photograph the envelope with the postmark before dropping it off. Keep that photo for at least two billing cycles.

When The System Fails
There are scenarios where Santander's payment infrastructure simply doesn't work for your situation. If you have a non-US bank account, cross-border payments often get rejected or held for manual review. If you're making irregular payments tied to variable income, the fixed autopay schedule becomes a liability rather than a convenience. If you've missed payments before and are trying to rebuild, the system's automated collections triggers can react faster than human intervention can prevent them. For these cases, the practical alternative is setting up a payment reminder calendar combined with manual portal payments on a consistent schedule. It removes the automation risk entirely. You're responsible for remembering, but you also control exactly when money leaves your account. Most people find that the mental load of tracking payments is lighter than dealing with the fallout of automated payments going wrong.
What The Statements Don't Tell You
Your monthly statement shows the payment amount, the due date, and the posting date. It doesn't show you how many days of interest accrued between your last payment and today, unless you request a payoff quote. It doesn't show you whether a payment was applied to the current cycle or the next one. It doesn't show processing delays or holds on deposited funds. I always tell people to log into the portal within 24 hours of making any payment and verify the posted amount matches what you sent. A mismatch there usually resolves itself within three business days, but catching it early saves you from a potentially messy dispute process. The biggest mistake I see is people treating the payment due date as a hard deadline. It's not. Santander typically has a grace period of 15 days before reporting a late payment to credit bureaus. The payment is still considered late during those 15 days, and late fees apply, but your credit score isn't impacted. That said, relying on this grace period consistently is risky. Systems change. Processing times vary. A payment that posts on time one month might take an extra day the next. Build your schedule assuming zero grace period. It's the only approach that doesn't leave you exposed.