San Mateo County Property Tax Payments: What Actually Happens When You Try
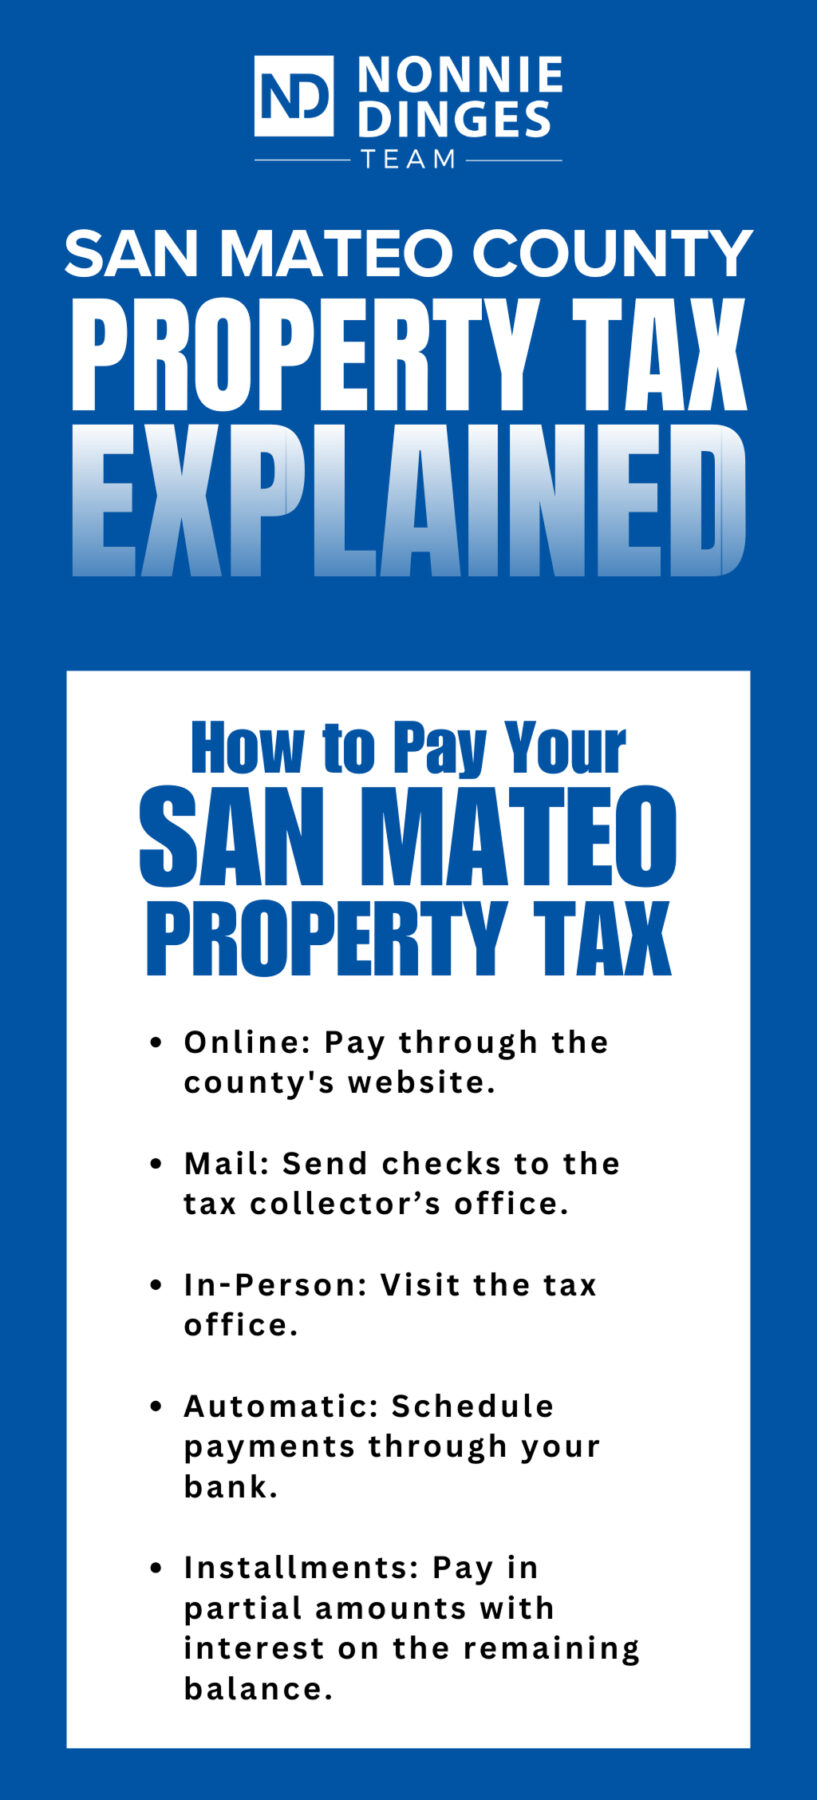
I spent about three years doing property tax filings across three different Bay Area counties before I got San Mateo dialed in. The system works, but there are enough weird edges to it that if you wing it, you will lose money. Here is the breakdown of how their programs actually function and what to watch out for. San Mateo gives you four main ways to handle your bill. The standard installment plan splits your annual tax into four quarterly payments. The due dates are November 1, February 1, April 1, and May 1. That last one is the final cutoff before the bill becomes delinquent. If you miss May 1, you are on the hook for a 10 percent penalty plus accrued interest and you lose the ability to pay under the installment plan until the next cycle resets. Then there is the monthly installment program. This one is not automatic. You have to apply for it. I found this out the hard way after someone at a neighbor association meeting casually mentioned it and I realized I had been paying quarterly penalties without ever knowing the monthly option existed. It breaks the same total amount into twelve equal payments and costs you nothing extra. The catch is that applications have to be filed annually, usually between July and August. Miss that window and you are stuck with quarters again until next summer.
The semi-annual option splits everything into two payments. November 1 and February 1 only. It cuts your transaction volume in half but you still carry the same total. I see a lot of people defaulting to this because they want fewer checks to write, but the downside is you have twice the amount due at once. If cash flow is tight, quarterly or monthly is safer even if it feels like more administrative overhead. There is also the option to pay electronically through the county's portal using a credit card or bank account. Credit card payments run a convenience fee, typically around 2.5 percent. I ran the numbers once and for a $5,000 tax bill that added about $125. Bank account withdrawals are free. If you are sitting on rewards points, sometimes the math works in your favor. But do not just swipe without checking what your actual reward rate is first.
Property Records and How They Actually Work
Property records in San Mateo are handled by the Tax Collector's office alongside the Assessor's office. They are related but separate. The Assessor determines value. The Tax Collector bills and collects. When you pull a record, you are typically looking at parcel information, assessed value, tax history, and any lien or exemption status attached to the parcel. Here is something most people do not realize. You can request a preliminary parcel report online for free, but getting a full certified copy with historical payment data usually runs between $15 and $25 depending on how deep you want to go. I wasted about forty minutes on the phone once trying to get what should have been a simple address verification and ended up with a department that kept transferring me because the assessor data and collector data sit in different internal systems. The workaround was straightforward once I figured it out: use the Assessor's parcel lookup tool for property details and the Tax Collector's site for payment history. They are on different subdomains. The page does not make this obvious. The county does maintain a searchable property search tool on their main site. It is functional but not great. Search by address and it returns a handful of records. Search by parcel number and you get more precise results. I always recommend having the APN handy before you start. The search field does not accept partial numbers well. I spent five minutes typing in "1234" trying to narrow down a result when the system wanted the full 14-digit identifier from day one.
Get the Full Details
Exemptions and Deferrals Worth Knowing About
The homeowner's exemption saves you from having tax calculated on the first $7,000 of your assessed value. It is not automatic. You have to file form BOE-100 and mail it in or submit it online. A lot of people who buy a home assume this applies by default. It does not. If you bought in January and did not file, you could lose several hundred dollars in savings for that entire tax year. For senior citizens and disabled homeowners, there is a property tax deferral program under Proposition 60 and Proposition 19. This lets you defer payments until the property transfers or the owner passes away. The county pays the bill on your behalf and you repay with interest later. It sounds generous but the interest rate compounds. I looked at one case where a homeowner deferred for eighteen years and the deferred amount had roughly doubled. The program works, but it is a long-term financial decision, not a free pass. There is also the anti-speculation surcharge for second homes and investment properties. If you own more than one residential property in California, you may be subject to an additional 1 percent surcharge on top of your regular taxes. This started a few years back and a lot of people still do not know about it. Check your bill line items. If you have a second property and there is no surcharge listed, call the office and ask. I found one property owner who had been underpaying by roughly $800 a year for three years before his monthly statement started showing it correctly after an audit flag.
Common Pitfalls That Cost People Money
The biggest mistake I see is people not tracking the exact due dates. February 1 falls on a weekend sometimes. The county counts it as on time if you mail it the Friday before or submit it electronically that day. But if you assume the system gives you until the following Monday, you are wrong. They do not. I had a client once who mailed a check on February 2 because he thought the weekend extended the deadline. The postmark was accepted but the check was returned as late and he ate the penalty. Electronic payment on the actual due date is safer every single time. Another thing: partial payments. The county will accept them, but they do not reduce your penalty risk in a meaningful way. If you pay half in November and half in April and then miss the April portion, you are still penalized on the full amount. Do not treat installments as optional minimums. Pay the full installment or do not pay at all and wait until the next one. There is also a misunderstanding about when reassessment happens. Buying a home does trigger reassessment, but gifts and certain transfers between family members may not. If you inherited a property and the paperwork was sloppy, your assessed value could be wildly off. I worked with someone whose parent transferred a house without a proper parent-child exclusion filing and the assessed value jumped by nearly $400,000. The fix was filing a corrected exemption claim retroactively, which took about six weeks and saved them thousands over the following year.
What the Online System Gets Right and Wrong
The payment portal itself is decent. It loads fast enough, accepts credit cards and bank accounts, and gives you a confirmation number instantly. The property search is where it stumbles. Results do not always refresh in real time. I submitted a payment and then immediately pulled up the property record to verify the balance cleared. The system still showed the old amount. It took about forty-eight hours for the collector's database to sync with the public search tool. Not a dealbreaker but worth knowing so you do not panic and try to pay twice. The site also lacks a dashboard for recurring reminders. You can set up automatic payments, but there is no calendar view or email notification system built in. I recommend setting your own calendar alerts three days before each due date. That buffer caught me when a bank processing delay almost cost me a penalty in 2023.

Direct Contact Options
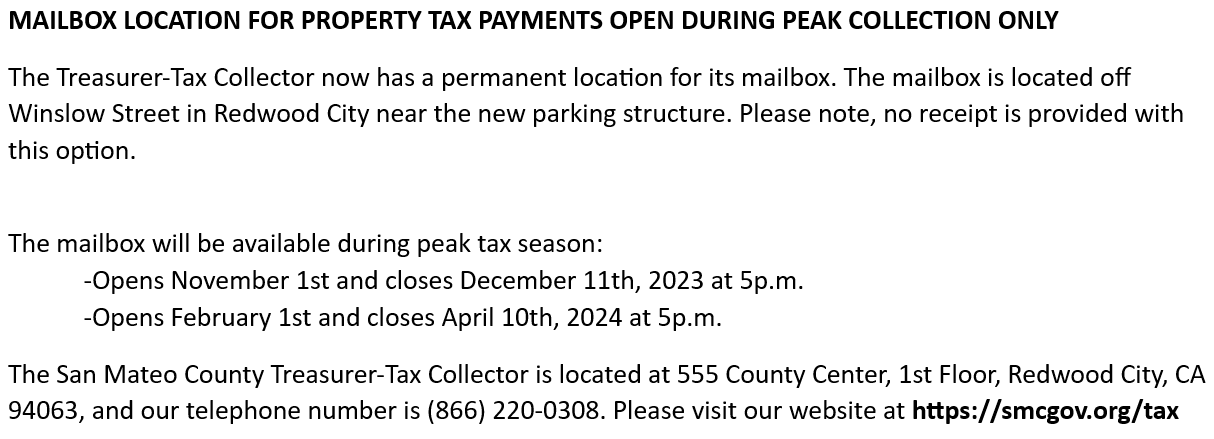
If you need to talk to a real person, the Tax Collector's office is at 501 County Center in Redwood City. Phone hours are Monday through Friday, 8 AM to 5 PM. Wait times vary. I called on a Wednesday morning in early November and was on hold for about twelve minutes. Calling mid-afternoon in February, right after the quarterly deadline, I waited nearly forty-five minutes. The website has a contact form but responses take five to seven business days. For anything time-sensitive, call during off-peak hours or go in person. Walking in on a Tuesday around 10 AM usually gets you served within fifteen minutes. There is no live chat. The website mentions digital assistance but it redirects you to a FAQ page. If you are dealing with a specific payment issue, a phone call or in-person visit is your fastest route to resolution.