Understanding The San Antonio Market Through Data, Neighborhood Breakdowns, And Strategic Positioning
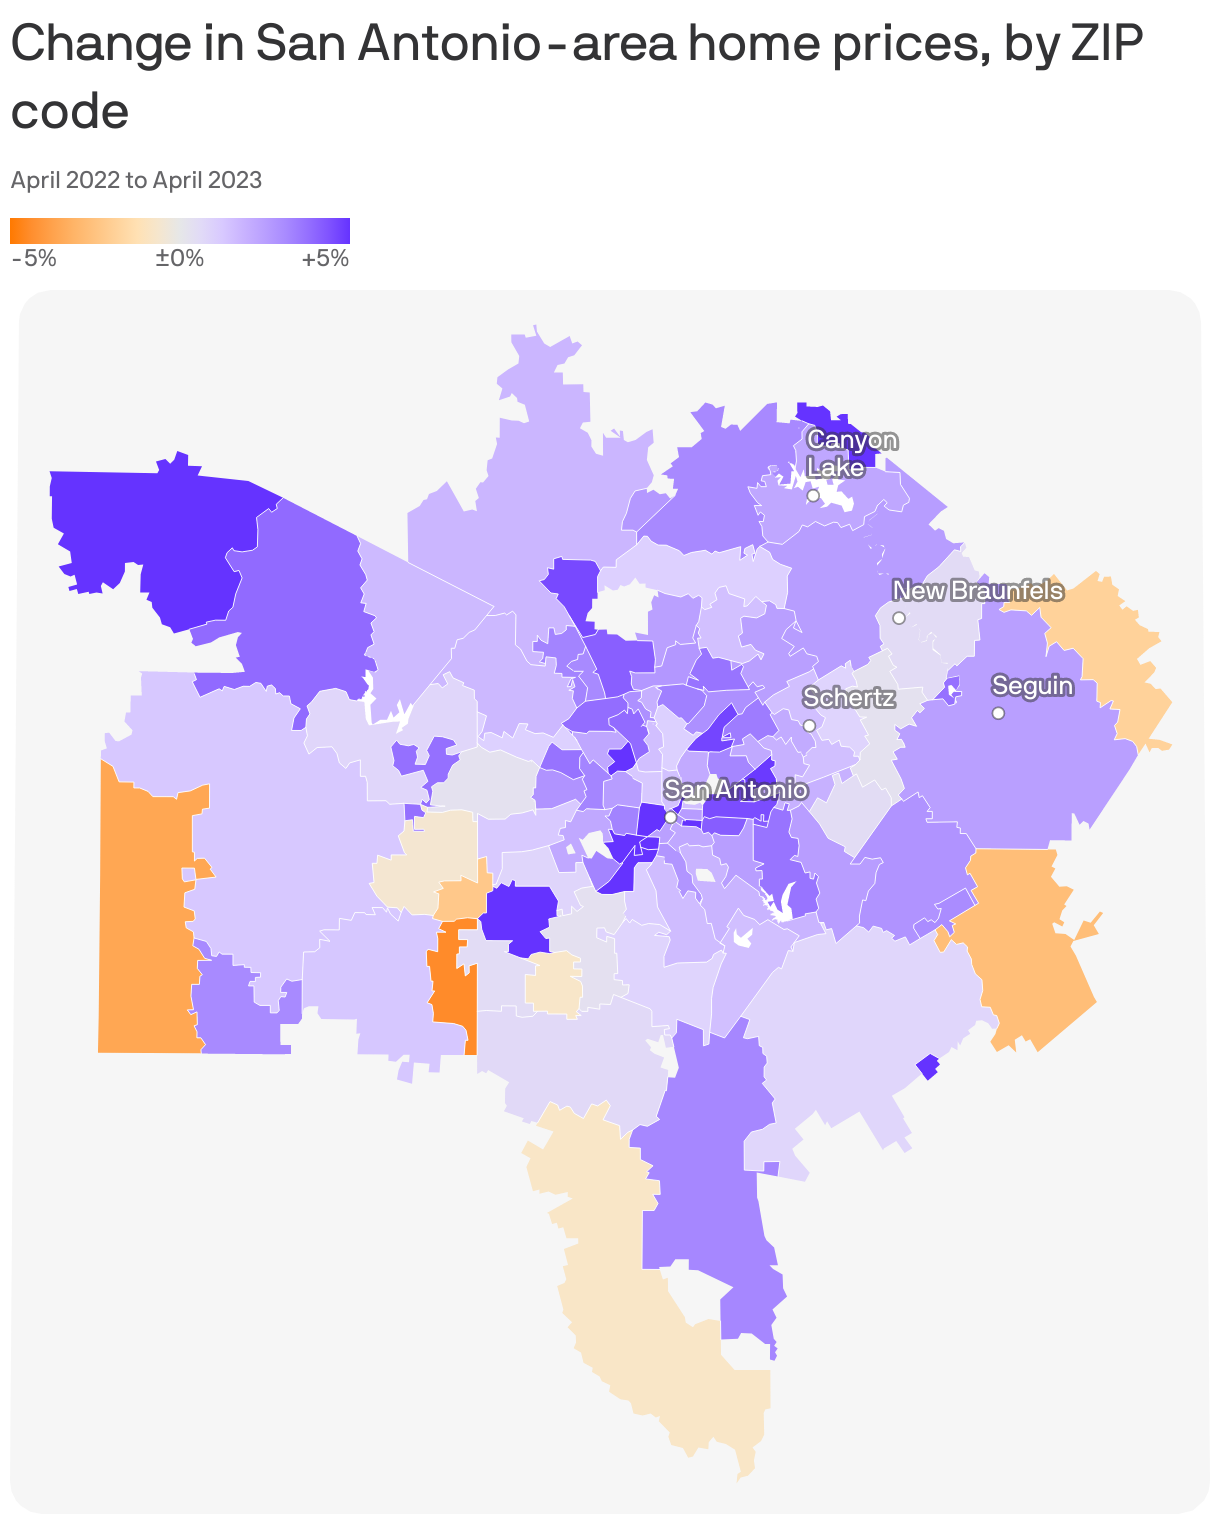
Looking at San Antonio's real estate market without a structured approach is like shooting in the dark. The city sprawls across 500 square miles with fundamentally different submarkets, and each one operates on its own timeline. What works in Alamo Heights will absolutely destroy you in the East Side or the far North Side. I have spent years tracking these patterns, and the short version is that most people treat San Antonio as one market. It isn't. Here is how you actually approach it. Let me start with something most guides skip over. You need to understand absorption rates before you look at a single listing. Absorption rate is simply how many months of inventory exist at the current sales pace. In San Antonio's core neighborhoods like the Pearl District or Government Hill, you might see a 1.5 to 2 month supply, which is a seller's market regardless of what the wider city numbers say. Meanwhile, out in Universal City or Selma, you could be looking at 6 to 8 months of supply even during boom periods. Those two environments require completely different entry strategies. I tracked this firsthand back in 2022 when the rates spiked. A lot of people sold off properties they had picked up during the pandemic boom, but the data told a messy story. The overall city median price barely moved, which looked stable on the surface. But when you broke it down by zip code, you saw something entirely different. West Side neighborhoods like 78227 absorbed the rate increase badly because they had a high concentration of investor-owned properties bought at peak prices. East Side areas near 78222 held value better because owner-occupant density was higher and the buyer pool was different. If you had just looked at the metro-wide numbers, you would have made the wrong call on both sides.
The trick most people miss is that San Antonio's market is heavily driven by employment corridors, not just neighborhood prestige. The Medical Center expansion, the lack of corporate relocations compared to Austin or Dallas, and the steady military presence create demand pockets that don't always align with traditional desirability rankings. For example, properties within a mile of UT Health San Antonio or near Fort Sam Houston have their own demand drivers that are somewhat insulated from the broader housing cycle. They do not crash the same way, and they do not surge the same way either. When you are doing your actual property search, the first filter you should apply is employment anchor proximity. Map out the major employers: lackland AFB, Brooke Army Medical Center, the downtown legal district, the North Star Mall corridor, and the growing tech presence around the 410 loop. Properties within a 15 minute commute of at least two of these anchors tend to maintain liquidity even when the broader market cools. I use this as a quick screening tool before I ever dig into comparable sales or run pro formas. It saves probably 80 percent of the time you would otherwise spend evaluating dead-end locations. Here is a specific edge case that cost me three weeks of work. A client wanted to buy a duplex near the 78209 zip code, right between the Pearl and the entertainment district. The numbers looked solid on paper. Cap rate was decent, the rent roll was fully leased, and the comps supported the price. The problem was that the property sat in a flood zone overlay that was not clearly marked on standard MLS sheets. Standard flood zone maps showed minimal risk, but a FEMA letter of map revision had been filed in 2019 that expanded the AE zone to include the rear half of the lot. No one had updated the tax records or the disclosure paperwork. The insurance premium alone would have doubled and made the deal unprofitable. The workaround was pulling the FEMA certificate of valid elevation directly from the county engineer's office and cross-referencing it with the latest FIRM panel updates. That process took about four days and saved us from closing on a money loser. If you are buying investment property in this city, budget two weeks minimum for due diligence that goes beyond the standard inspection.
Neighborhood definitions in San Antonio are also more fragmented than most outsiders realize. You can drive two miles from the King William district into what is technically a different submarket with different zoning rules, different school catchments, and a completely different buyer profile. The Alamo Heights ISD boundary runs right through areas that look identical on the surface. A house that sits 200 yards inside the boundary commands a 30 to 40 percent premium over an otherwise identical house just outside it. This is not a small difference. It is the entire margin on most rental deals. Data sources matter a lot here. The standard MLS gives you the basics, but you need to layer in the Bexar County Appraisal District records for actual sale history, the local police district maps for crime trends, and the city's development pipeline reports if you are looking at anything outside the core. New construction in the far North Side has been flooding certain segments with speculative inventory, and theMLS does not always flag that a listing is part of a tract development with builder incentives still active. Those incentives change the comparable analysis entirely. If you run comps against full market price when the actual transaction included a 5 percent buydown and $8000 in closing credit, your valuation is wrong. One counter-intuitive thing about this market: distance to downtown is becoming less of a pricing factor than it used to be. The remote work shift and the decentralization of jobs have changed the gravity map. Areas like Stone Oak and the Far Northwest are priced at a premium partly because of school districts and master-planned community amenities, but the commute advantage over something like 78216 near the South Side is shrinking in real terms. What matters more now is micro-location within a neighborhood. A block away from a major road, a different tree line, or a slight elevation change can swing value by 10 to 15 percent in ways that macro data completely misses.
Get the Full Details

For strategy, the simplest framework that actually works is to pick one submarket and map every transaction in it over the last 18 months. Not the whole city. One submarket. You will quickly see patterns like whether certain streets sell faster in spring versus fall, whether certain property types have a persistent supply shortage, and whether the current owners are mostly upsizing downsizing or relocating. That last point is critical. Relocation buyers pay more and close faster because they are under time pressure. Upsizers and downsizers are more price sensitive and negotiate harder. I once spent six weeks trying to work a deal in 78230 only to learn that every sale in that pocket that year came from a military PCS move. Once I adjusted my offer strategy to account for the typical 60 day timeframe those buyers operate on, everything clicked into place. There are real limitations to relying on data alone in San Antonio. The city does not have the same level of granular neighborhood reporting that you get in larger metros. Many neighborhoods do not have dedicated community association databases, and the historical appreciation data for smaller submarkets can be sparse or inconsistent. In those cases, the data points you do have are noisy and easy to misinterpret. The workaround is combining the available data with physical scouting. Drive the neighborhoods at different times of day. Talk to property managers who handle units in the area. The qualitative information you pick up fills gaps that quantitative data simply cannot cover, and it usually takes about two weekends of driving to get a reliable sense of a submarket's rhythm. If you want a practical starting point, here is what I use. Pull the Bexar County property search by zip code and sort by days on market. Identify the zip codes where properties are moving in under 30 days on average. Cross reference those with the city's current permitting data to see where new supply is being built. Then overlay the school district boundaries and the major employer distances. The intersections of those three maps tell you where the market is actually tight. Everything else is noise. This process takes me about 45 minutes when I have the data already loaded, and it is significantly faster than manually reviewing listings one by one.