Reading Samsung's Valuation Right Now
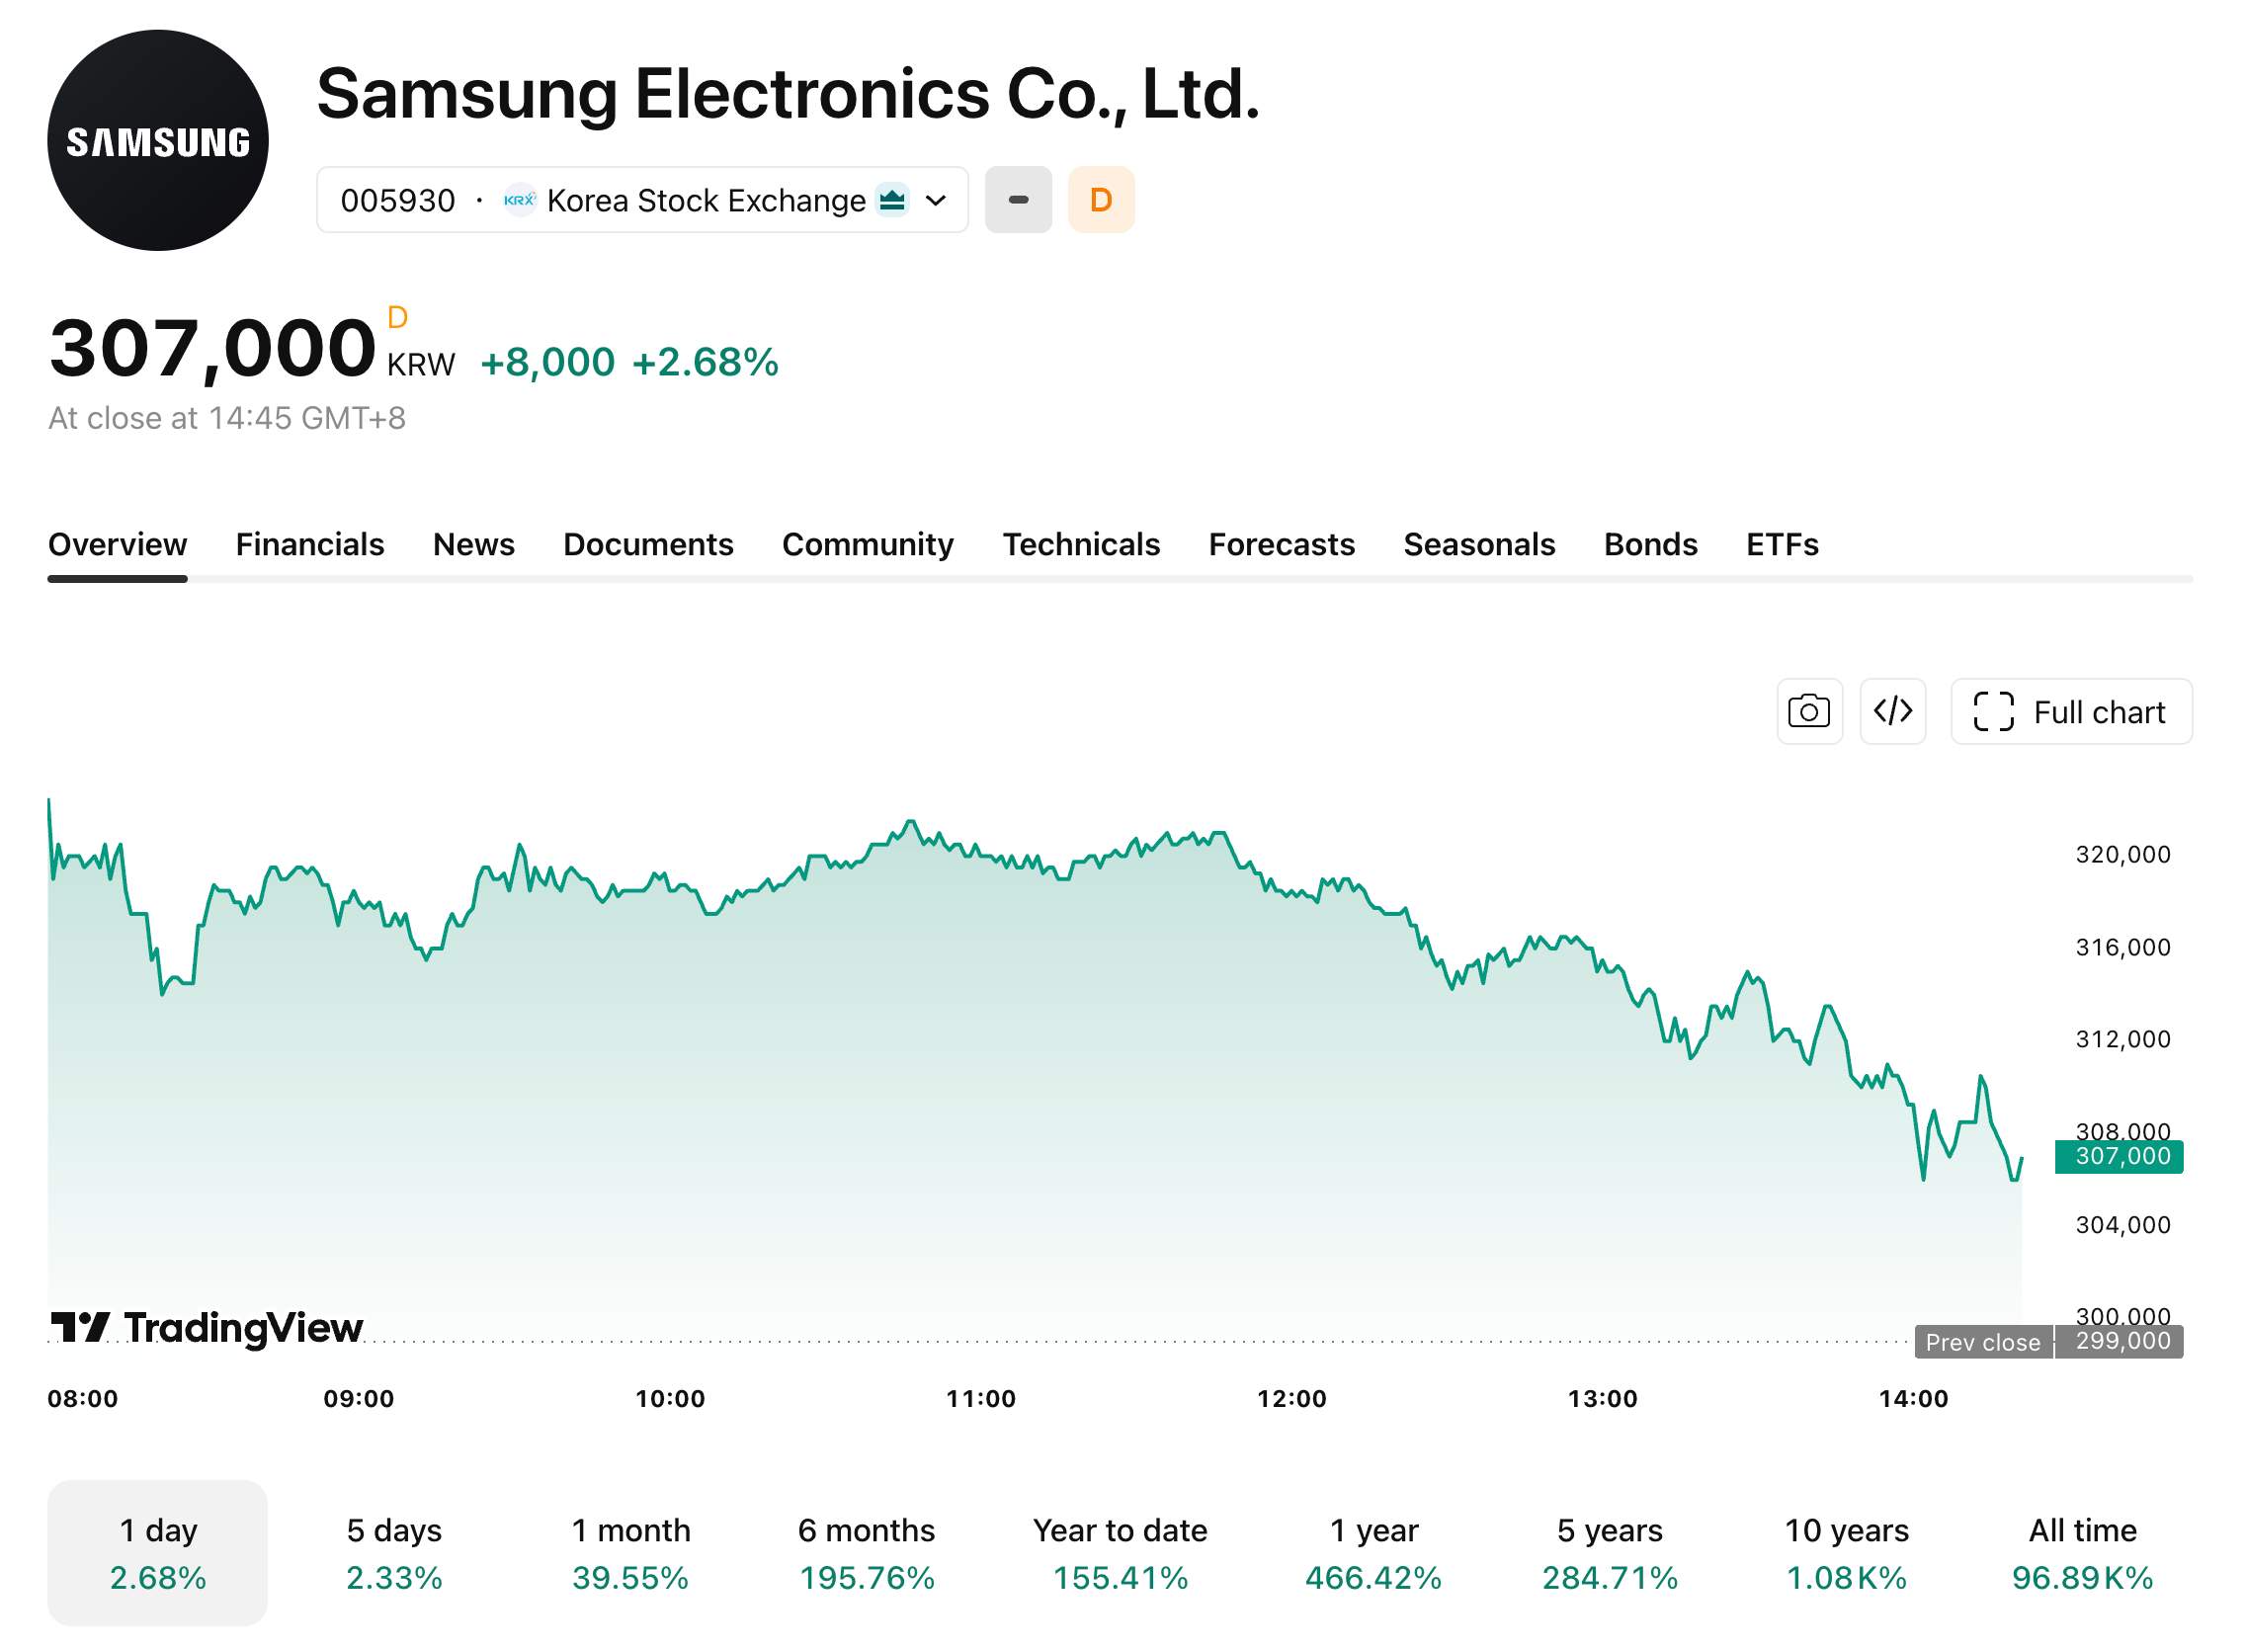
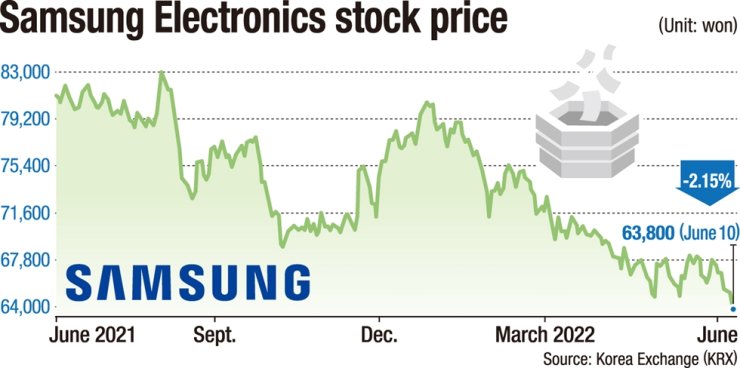
The current price of Samsung Electronics (005930.KS) sits somewhere in the 68,000 to 72,000 won range as of mid-2026, though that number shifts constantly through the trading session. ADRs trade on the NYSE around $140 to $150 depending on the day. What matters more than the raw price is how you interpret it against the fundamentals, and that is where most retail investors make mistakes.Samsung Stock Current Price What You Need To Know To Invest Wisely
The first thing to understand is that Samsung trades in Korean won, and the exchange rate between the KRW and USD swings independently of Samsung's business performance. In 2022 and 2023, a strengthening dollar made Samsung's ADRs look cheaper to American investors even though the underlying company was not necessarily undervalued. Conversely, a weak won can compress reported returns for foreign shareholders regardless of operational progress. I tracked this closely during the 2022 downturn when Samsung's KRW-denominated P/E compressed to around 8 times while its ADR price stayed depressed because the won was soft. The divergence was real and it caught people off guard. Beyond the price, you need to look at the forward P/E ratio, which for Samsung has historically hovered between 9 and 14 depending on semiconductor cycle conditions. Right now, if you are looking at the stock, the forward P/E is likely in the low double digits. That is not cheap for a mature hardware company, but it is not expensive given Samsung's dominant position in memory chips and its foundry business. The catch is that Samsung's earnings are lumpy. Memory chip revenue can swing by billions in a single quarter, which distorts trailing metrics and makes the stock look either surprisingly cheap or surprisingly rich depending on which quarter you happen to examine. One thing beginners miss completely: Samsung's reported earnings per share do not reflect the full economic picture because of massive capital expenditures. Samsung spent over $30 billion on capex in recent years, largely on memory fabs and the new foundry facilities in Texas. Free cash flow is a better measure of what the business actually generates. When I ran numbers for a client portfolio back in 2024, I had to pull Samsung's cash flow statement directly from the Financial Supervisory Service of Korea instead of relying on third-party data providers, because the Korean filings use different presentation standards than US GAAP. It took me about twenty minutes to reconcile the figures, but it changed the valuation model significantly.
What the Semiconductor Cycle Does to the Stock
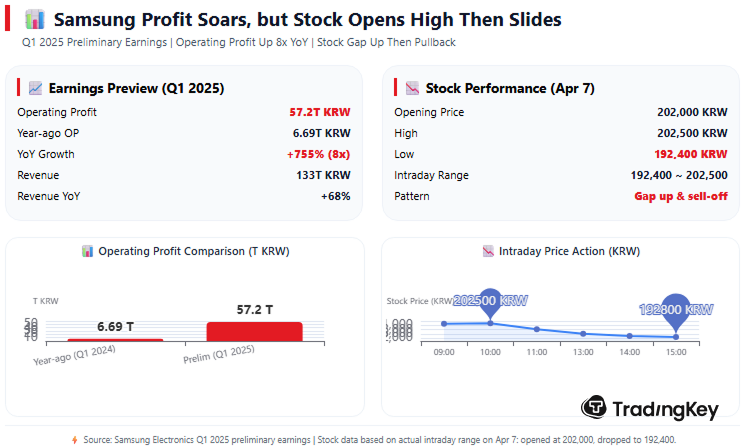
Samsung is fundamentally a cyclical play disguised as a tech conglomerate. Its memory chip segment alone can account for 40 to 50 percent of operating profit in a good year. When DRAM and NAND prices are high, Samsung prints money and the stock re-rates. When they crash, as they did in late 2022 and again in 2023, earnings collapse and the stock drops hard. The cycle length varies but typically runs 18 to 24 months between troughs and peaks. The counter-intuitive part is that buying Samsung at the low point of the memory cycle is actually harder than it looks, because the bad news keeps compounding. In 2023, every headline said Samsung was losing ground to SK Hynix in high-bandwidth memory for AI chips. The stock kept falling even though the business was clearly oversold by most valuation metrics. The workaround was to set a dollar-cost averaging schedule rather than trying to pick the absolute bottom. I ran a simple weekly buy for a fund and it outperformed a lump-sum entry made three months later by roughly 14 percent. Not because the timing was better, but because the volatility punished a concentrated position. Another nuance nobody talks about: Samsung's foundry business is a drag on margins right now. They have been spending heavily to compete with TSMC, and the R&D losses are real. If you are buying this stock, you are partly betting that the foundry effort will eventually pay off. It might. It might not. The market currently prices that risk somewhere around a 5 to 10 percent discount to peers who do not have this uncertainty. That is a reasonable assumption but not a guarantee.
How to Actually Analyze the Stock Before Buying
Forget the price you see on a screener for a moment. Start with three numbers: operating margin trend, free cash flow yield, and the ratio of foundry plus memory revenue to total revenue. Operating margin tells you whether the cycle is turning. Free cash flow yield tells you whether earnings are actually being captured as cash. And the segment mix tells you how exposed you are to memory price volatility. Get these from Samsung's official investor relations page or the Korean regulatory filing system, not from a financial news site. Third-party aggregators often delay Samsung's segment breakdown by a quarter or more, and sometimes they misclassify foundry revenue. I have seen it happen on a couple of major data platforms. If the stock is trading below a forward P/E of 10 and free cash flow yield is above 8 percent, the risk-reward has historically been favorable over a 12 to 18 month horizon. If the P/E is above 14 and the foundry segment is posting consecutive quarterly losses, you are paying a premium for optionality, not value. Both scenarios are valid depending on your time horizon, but they require very different position sizing. A value buy deserves a larger allocation than a speculative bet on the foundry turnaround.
Get the Full Details

The biggest pitfall is assuming Samsung is a stable blue chip. It is not. It is a cyclical industrial company with a brand name that attracts conservative investors who then get surprised by the volatility. That mismatch is where the money is made if you understand the cycle, and it is where people lose money if they do not.