What you're actually dealing with
New York requires most businesses that sell tangible personal property or certain services to collect and remit sales tax. The state handles filing through a portal called Webfile, and yes, the name itself is about as exciting as it sounds. You log in, enter your returns, and pray the session doesn't time out mid-submit. I have spent too many late evenings staring at a loading spinner while my browser held its breath. The NY Department of Taxation and Finance manages this. Your account lives inside their system and you access it through the same Webfile login you use for other state filings. Most companies that operate in New York get assigned a file number automatically when they register. If you are multi-entity, each entity usually gets its own file number. I learned this the hard way when a subsidiary filed under the parent's number and the reconciliation process became a two-week nightmare of cross-referencing payment vouchers and correcting misapplied remittances. Here is how the process actually works on the ground.
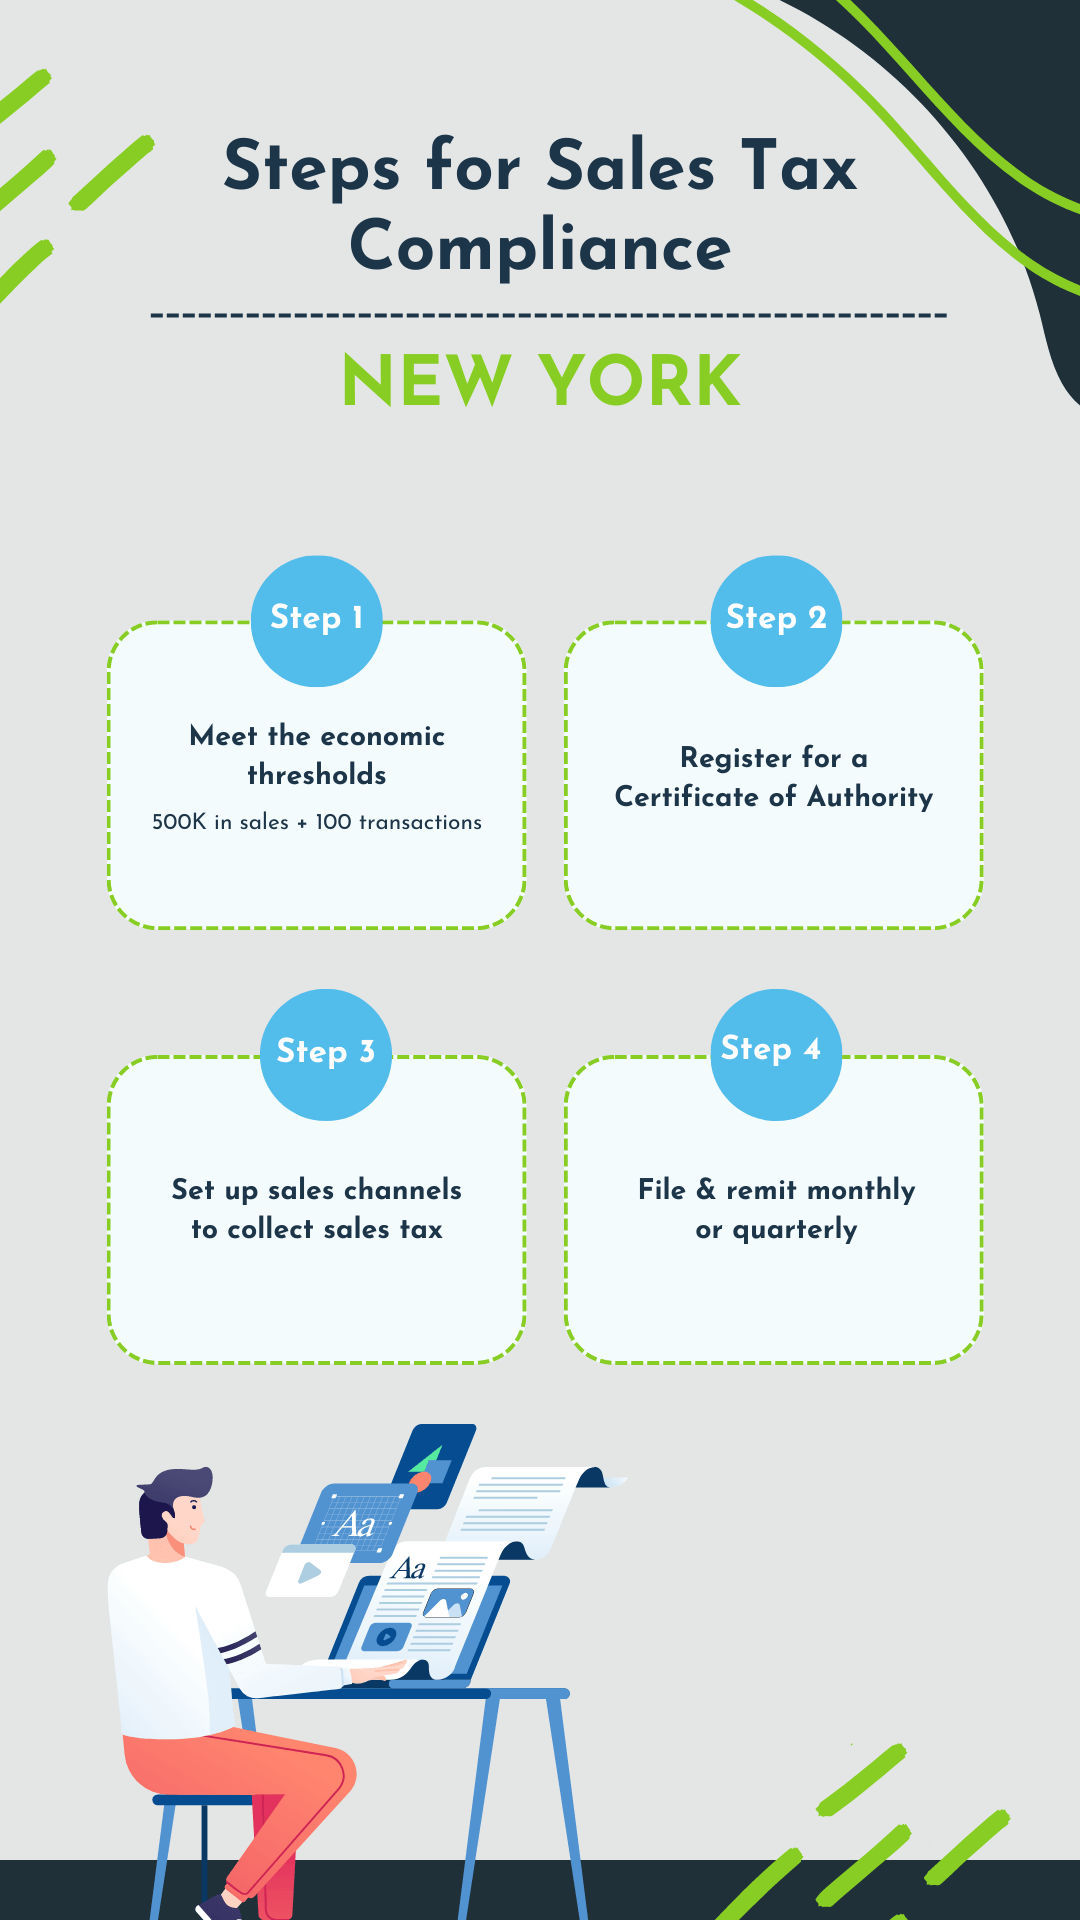
Step one: figure out if you have nexus. Nexus means you have a sufficient connection to New York that triggers the obligation to collect and remit. Physical presence is the old standard, but economic nexus changed everything after the South Dakota v. Wayfair decision. If you exceeded $500,000 in sales and 100 transactions into New York in the previous calendar year, you likely have economic nexus even if you have no office, employees, or warehouse there. Thresholds are measured in a rolling four-quarter window, not a single quarter. Miss that detail and you will underreport for a while before the state catches up. Step two: determine what is taxable. New York taxes the sale of tangible personal property. Services are mostly nontaxable unless specifically listed. Digital products occupy a messy middle ground. Software downloaded electronically is taxable. Some streaming services are not. Food prepared for immediate consumption is taxable. Grocery food is generally exempt. If you run a subscription box, the entire value of the shipment is typically taxable at the point of delivery, not just the markup. Rates vary by locality. The base rate is 4 percent statewide, but counties and cities add their own portions, which can push the effective rate to 8.875 percent in parts of New York City. You must collect the rate that applies at the delivery location, not the rate at your business address. Step three: register and get your credentials. You register through the New York State Department of Taxation and Finance website. Once approved, you receive a file number and login credentials for Webfile. Keep those credentials in a password manager. I have seen too many small business owners lose access because their CFO left without handing over the login details. If you do lose access, the reissuance process involves identity verification and can take anywhere from a few business days to two weeks depending on volume.
Step four: collect the tax. You collect sales tax from your customers at the correct rate. You must issue receipts that separately state the tax amount. New York does not require a specific receipt format, but if your receipt does not break out the tax, the state may treat the entire charge as nontaxable and you could owe both the tax and penalties. Line items matter more than you think. Step five: file and pay on time. Your filing frequency is assigned by the state based on your expected tax liability. Most small businesses file quarterly. Larger ones file monthly. You can check your assigned frequency by logging into Webfile and looking at your account summary. The due date is the 20th of the month following the reporting period. If the 20th falls on a weekend or holiday, the next business day is your deadline. Late filing penalties start at 5 percent of the unpaid tax per month, up to 25 percent. Interest accrues separately at the statutory rate. These are not discretionary. They are automatic. I ran into a specific problem once that illustrates how it is to make mistakes here. I was preparing a return for a client who sold both taxable and nontaxable items. The Webfile interface asks you to enter total sales and then breaks out the taxable and non-taxable portions. My client had consolidated everything into a single gross sales figure and tried to back into the numbers afterward. The system accepted the entry but the computed tax was wrong because it applied the rate to the full amount instead of the taxable subset. I had to pull the original invoice logs, rebuild the breakdown by line item, amend the return, and resubmit. That took roughly six hours of manual work to fix an error that should have taken ten minutes to catch. The workaround is simple: do not rely on aggregated figures. Export your POS data or accounting ledger, categorize every line item before you enter anything into Webfile, and verify the taxable subtotal matches your internal records before you hit submit.
Get the Full Details
Step six: keep records. New York law requires you to maintain sales tax records for at least three years from the date the return was filed. That includes invoices, receipts, exemption certificates, and your filed returns. Exemption certificates deserve special attention. If a customer claims an exemption, you must obtain and retain a properly completed Form ST-120 or its electronic equivalent. Verbal claims do not count. I once audited a vendor who accepted exemption claims over email without collecting the certificate. The state disallowed every exemption and the vendor owed back tax on millions in supposed exempt sales. The lesson is blunt: if you do not have the certificate on file, the sale is taxable regardless of what the customer told you. There are nuances that beginners consistently miss. One is the difference between transactional tax and use tax. Transactional tax is what you collect from buyers at the point of sale. Use tax is what you owe on purchases you made for your business where the vendor did not collect New York sales tax. Many businesses file their transactional returns correctly and then forget about use tax entirely. If you buy equipment, software, or supplies from an out-of-state vendor that does not charge you New York tax, you are generally required to self-assess and remit use tax on Webfile. This is not optional. It is a separate line item on your return, and the state does expect you to report it even when no third party is watching your purchase activity.
Another counter-intuitive detail is the treatment of allowances and discounts. If you offer a prompt payment discount, you can generally deduct the discounted amount from your taxable sales as long as the discount is taken before payment is received. If you give a post-sale rebate, that is different. Rebates do not reduce your taxable sales for filing purposes unless you structure them correctly. I had a client who issued paper rebates to bulk buyers and excluded those amounts from their sales tax returns. The state flagged the discrepancy during a routine review and assessed additional tax plus penalties. The fix was to switch to a point-of-sale discount that reduced the invoice amount at the time of sale rather than issuing a rebate afterward. Let me be honest about the limitations of Webfile. The interface is functional but outdated. It was built for a simpler era of e-commerce and it shows. File uploads can fail silently. Session timeouts are aggressive. The help documentation is sparse and often points to forms that no longer exist. If you have a high volume of transactions, manual data entry is unsustainable. I recommend using an integrated sales tax solution that connects to your accounting system or e-commerce platform and pushes the data directly to Webfile through their API or a supported import format. These tools cost money, but they eliminate the most common sources of error and cut the filing time from hours to minutes for most businesses.
Another limitation is that Webfile does not provide real-time audit guidance. If you are unsure whether a particular sale is taxable, the system will accept your entry and move on. It will not warn you that you undercollected or overcollected. The consequence of that silence is that errors compound. You might file five consecutive quarters with a slight miscalculation before anyone notices. By then, the back tax, interest, and penalties add up quickly. The workaround is to schedule a quarterly review with someone who understands New York sales tax before you file, or to run your numbers through a test return in a sandbox environment first. If your business operates in multiple states, New York's conformity rules are not identical to other states' rules. New York uses a destination-based sourcing model for most sales, meaning the tax rate is determined by where the product is delivered. California and Texas also use destination-based sourcing, but their rate structures and exemption categories differ. If you are multistate, do not assume that a rate lookup tool built for another jurisdiction will work accurately for New York. Run your rates against the official New York rate table or use a tool that is specifically calibrated for New York's local jurisdiction breakdowns. For the actual filing process, here is the sequence you will follow each period:
Log into Webfile with your file number and password. Navigate to the sales tax filing section. Select the appropriate return period. Enter your total sales, taxable sales, and any adjustments. Apply the correct tax rate for each jurisdiction involved. Review the computed tax. Submit the return and pay the amount due. You can pay via electronic funds withdrawal from your bank account or by credit card. EFT is free. Credit card payments incur a processing fee that ranges from about 2.5 to 3 percent depending on the processor. For a quarterly payment of $5,000, that fee is roughly $125 to $150. I always recommend EFT unless you need the float for a few extra days. After you submit, Webfile generates a confirmation number. Save it. If you do not have a confirmation number and the state does not show your payment, you are in a difficult position. There is no chat support with instant resolution. You will need to call the tax department and wait on hold for a period that ranges from thirty minutes to over an hour during peak filing seasons, which are April, June, July, October, and January. There is also a combined business application that allows you to register for multiple tax types at once, including sales tax, withholding tax, and corporation franchise tax. If you are starting a new business, filing the combined application saves time compared to filing each registration separately. However, the combined form does not assign your sales tax filing frequency. That comes later in a separate notice. Do not assume your frequency is set until you receive that notice or see it confirmed in your Webfile account dashboard.
If you need to change your filing frequency, you can request a change through Webfile or by contacting the department directly. Changing from quarterly to monthly usually happens automatically if your liability increases beyond a certain threshold. You cannot voluntarily switch to monthly just to appear more compliant. The department controls that decision based on your payment history and reported liability. One final practical note: New York has recently expanded its tax base to include certain digital services and subscription products. The rules are still evolving, and the department issues bulletins periodically to clarify how existing statutes apply to new business models. If you sell digital goods or recurring services, subscribe to the New York State tax bulletin updates. Ignoring those updates has led to compliance failures for businesses that assumed their products were nontaxable based on outdated guidance. The system works if you treat it with the seriousness it deserves. The penalties are real. The interface is unforgiving of sloppy input. The rules change without much fanfare. Keep your records organized, verify your rates before each filing, and do not rely on memory or assumptions when the tax code is this detailed. That is how you stay compliant without losing sleep over a missed line item.