Understanding How Issaquah Sales Tax Actually Works In Practice
If you live in Issaquah or shop here regularly, you have probably noticed that the sales tax rate isn't just some generic statewide number. Washington state has a layered system where county, city, and special district additions stack on top of the base rate, and Issaquah sits inside both King County and the Lake Sammamish Regional Transit Authority district. That means the total rate you see at checkout is the result of multiple separate levies being combined, not a single flat percentage set by one authority. The Washington Department of Revenue publishes the combined rates annually, but those numbers can shift when new transit or fire district fees get approved through local votes. I have spent years dealing with sales tax compliance for a small business in the area, and the most confusing part for people is always the same thing: the distinction between where you buy something and where you are shipping it. Washington is a originating-location state for retail sales tax, which means the rate is determined by the seller's physical location, not the buyer's address. I learned this the hard way when I tried to honor a customer's residential rate for a delivery to Elk Grove because it felt more fair. The state doesn't care about fairness. It cares about where the seller's place of business is registered. I had to change my checkout system to route rates based on my Issaquah nexus address, and even then I still get audit flags when a customer disputes the charge because they think their own city rate should apply. It does not. The originating seller's location controls everything.
Sales Tax In Issaquah Washington A Detailed Breakdown For Residents And Shoppers
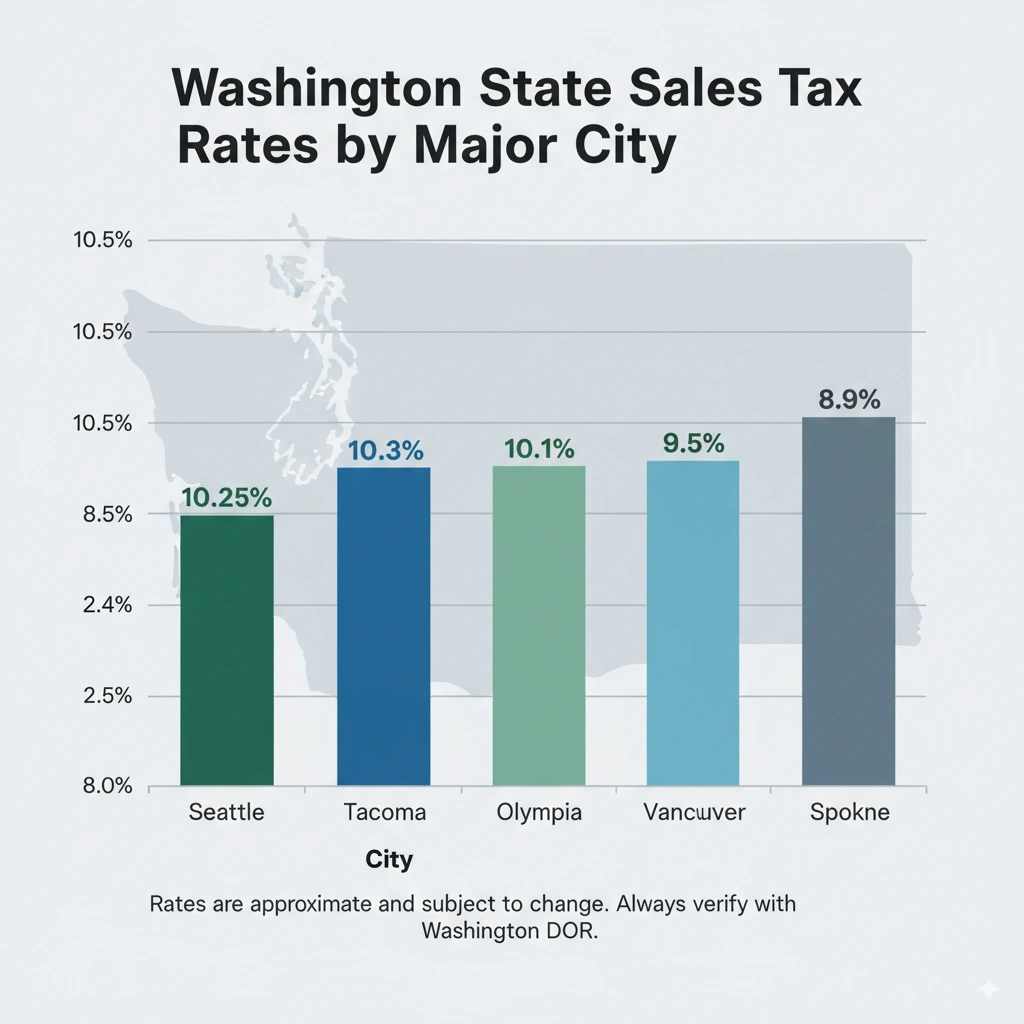
The current combined sales tax rate in Issaquah runs around 10.1%, and that figure comes from several distinct components. The Washington state base rate is 6.5%. King County adds 0.27% for transportation projects, which is a dedicated levy that shows up on your receipt as a separate line item in some cases. The City of Issaquah contributes its own local rate, which has fluctuated over the years as ballot measures have come and gone. Then there is the Lake Sammamish Regional Transit Authority, which adds roughly 0.45% to 0.5% depending on the current levy status. A fire district surcharge and possibly a hospital or parks levy may also factor in. These are not always visible individually on a consumer receipt, which is why people frequently assume the rate is arbitrary. One thing that catches people off guard is that the rate is not uniform across the entire Issaquah city boundary. Issaquah spans multiple fire and transit taxing districts, and the boundaries don't always align neatly with neighborhood lines. If you are setting up an e-commerce storefront that ships from Issaquah, you need to price goods using the originating-location rate, but if you have physical presence in multiple jurisdictions, the calculation becomes significantly more complicated. I handle this by maintaining a rate table that maps every zip code and street segment to its corresponding combined rate, then updating it quarterly when the Department of Revenue releases new figures. The automated tools most retailers use will give you a single blended rate for Issaquah, but that blending can hide the fact that two addresses only a mile apart might technically fall under different district combinations. There is also a practical issue with online marketplaces and third-party sellers. Under Washington law, marketplace facilitators are responsible for collecting and remitting sales tax on their own platforms, which means items sold through Amazon or eBay will show a rate at checkout that is calculated based on the marketplace's nexus location, not necessarily yours. This creates an inconsistency where the same product purchased from different channels will carry different tax amounts. I have had customers email me asking why their online order showed a lower rate than my local store. The answer is usually straightforward, but explaining it to someone who just wants a straight number is not easy because the underlying mechanics involve multiple layers of legislative intent and compliance obligation that most shoppers never see.
Food and groceries operate under a completely separate set of rules, which is another frequent source of confusion. Washington State does not tax most groceries for home consumption, but it does tax prepared foods, hot foods, and restaurant meals. I worked with a client who ran a small bakery and was genuinely surprised to learn that their pre-packaged cookies were exempt while their fresh-baked goods sold by the slice were taxable. The distinction comes down to whether the item is considered prepared for immediate consumption, and the line between those categories is blurrier than most people expect. A loaf of bread is not taxable. A sandwich from the same bakery is. The same product, sold side by side, taxed differently. Another nuance that matters if you are a resident doing any kind of resale is the requirement to obtain a resale certificate. Washington issues this through the Department of Revenue as part of the business licensing process, and it allows you to purchase inventory without paying sales tax upfront, provided you file the proper forms and maintain accurate records. I have seen small business owners skip this step because they assumed their out-of-state suppliers would handle the tax correctly. They do not always. If you buy from a vendor who does not verify your resale status, you pay the full tax, and recovering it later requires filing a refund claim that can take months to process. Keeping your resale certificate on file and presenting it at the point of purchase is the only reliable way to avoid this problem. The digital products category is also worth addressing because it has changed dramatically in recent years. Services like software downloads, streaming subscriptions, and digital media are generally taxable in Washington, whereas tangible goods may not always be, depending on how they are classified. I ran into an issue last year when a client was purchasing a digital asset from an out-of-state provider and the vendor refused to collect Washington sales tax, arguing that the transaction was nexus-independent. The state's position has been that digital products are taxable regardless of where the seller is located, and the burden of self-assessment falls on the buyer in those cases. It is not commonly enforced against individual consumers, but businesses that make significant purchases of this type should be aware that they may have a voluntary disclosure obligation.
Get the Full Details
Practical Steps For Residents And Shoppers
If you want to understand exactly how much tax you are paying on a specific purchase, the most reliable method is to look at your receipt line items and cross-reference them with the current rate published by the Department of Revenue. The agency maintains an online rate lookup tool that allows you to enter a street address and get the exact combined rate for that location. It is not always perfectly up to date, but it is close enough for most purposes. If you are running a business and need precision, you should subscribe to their rate update notifications so you are not caught collecting at the old rate after a levy change takes effect. For residents who travel outside Issaquah to shop, remember that Washington does not offer a credit for taxes paid at lower-rate jurisdictions. If you buy something in a city with a lower combined rate and bring it back to Issaquah, you do not owe additional tax at home, but you also do not get reimbursed for the difference. The tax is due where the sale occurs. Some people try to circumvent this by mailing purchases to friends in lower-tax areas and having them forward the items, but that strategy only works for out-of-state transactions where no Washington tax was collected in the first place. It does not help you avoid Washington sales tax on a purchase made within the state. The use tax concept is important here, even though most people ignore it. Use tax applies to items you purchase from an out-of-state seller who does not collect Washington sales tax. Technically, you are required to report and pay this tax on your own income or personal property tax return, but enforcement is largely voluntary. The state does send occasional notices to taxpayers who appear to have made significant out-of-state purchases, and those notices can trigger an audit. If you buy a high-value item like a vehicle, appliance, or piece of equipment from an online retailer that does not collect Washington tax, you should factor the use tax into your cost calculation before making the purchase. It is usually a few hundred dollars on a thousand-dollar item, and it makes the price advantage of shopping out of state disappear quickly.
I also want to mention the temporary events and special jurisdiction rules because they come up more often than you might think. Issaquah hosts several large events throughout the year, including the Issaquah Arts Festival and various farmers markets, where temporary vending permits are issued and sales tax collection is handled differently. Vendors at these events are typically required to collect tax at the combined Issaquah rate, but the administrative burden falls on them rather than on a centralized marketplace facilitator. I have seen vendors get confused about this and under-collect, which leads to penalties that far exceed the original tax shortfall. If you are selling at one of these events, confirm the rate with the city clerk's office before the event starts rather than assuming the standard rate applies.
What The System Does Not Handle Well
The biggest weakness in Washington's sales tax framework is the lack of simplicity. Rate changes happen frequently through voter-approved levies, and the timing of those changes is not synchronized across jurisdictions. A transit district renewal might pass in November but not take effect until the following July, creating a six-month window where the published rate is outdated and businesses need to track two different rates for the same location. I keep a spreadsheet that logs every known levy expiration and effective date, and I check it monthly. The state provides a newsletter, but it is easy to miss updates if you are not actively subscribing. Another problem is the inconsistency in how different platforms display tax information. A credit card statement, a receipt, and an online order confirmation will sometimes show different tax amounts for the same transaction, usually because the point-of-sale system calculates tax at a slightly different moment in the checkout flow than the payment processor does. This discrepancy matters if you are trying to reconcile expenses for a business, and it is one of those things that will cause headaches during an audit unless you have a consistent policy for which document you trust. I recommend using the point-of-sale receipt as your primary record and treating any variation from a payment processor as a rounding or timing artifact that should be documented and explained. The system also struggles with remote and gig economy transactions. Delivery drivers, freelance contractors, and independent service providers who sell directly to consumers in Issaquah may not realize they have a sales tax collection obligation until they receive a notice from the Department of Revenue. Washington requires tax collection on retail sales of tangible personal property and certain enumerated services, and the definition of a retailer in this context is broad enough to include anyone who makes occasional sales, not just established businesses. If you sell items on Facebook Marketplace, eBay, or a similar platform from within Issaquah and your sales volume exceeds the threshold, you may need to register and collect tax going forward. The state has been increasing its enforcement in this area, and the penalties for non-compliance are calculated on the full amount of uncollected tax, not just the difference between what was collected and what should have been.