What Home Credit Sales Agent Actually Looks Like Day-to-Day
Home Credit is a consumer financing company that primarily operates in emerging markets across Asia, Africa, and Eastern Europe. Their sales agent role is fundamentally about selling credit products — things like installment loans for electronics, appliances, education, and sometimes small business financing. The product itself is straightforward: a customer picks an item they want to buy, and Home Credit pays the merchant upfront while the customer repays over time with interest. You're the one connecting those two parties. "Pahami Tugas Potensi Penghasilan" is Indonesian for "understand the job and income potential." That's actually the most honest way to look at this role before you take it. Let me break down both parts without spinning it. Your core responsibility is customer acquisition. You go out, find people who need financing, walk them through the application, collect their documents, and submit everything through the company's system. The typical flow is: identify a lead, do a quick eligibility screening, fill out the application form (either digital or paper depending on the market), gather required documents such as ID, proof of income, and a utility bill, then submit for underwriting. The underwriting decision usually comes back within a few hours to a couple of days. If approved, the loan gets disbursed and your commission is recorded.
That sounds simple on paper. In practice, document collection is where most agents lose time. I remember one specific case in Jakarta where a customer had been working at the same company for three years but couldn't produce a formal employment letter because her HR department was notoriously slow with paperwork. She needed the loan approved the same day because a local merchant was running a promotion. The workaround I used was to accept her recent bank statements showing regular salary credits for six months instead, along with a verbal confirmation call to her supervisor that I made on the spot. The system flagged the missing letter, but I uploaded a note in the internal remarks field explaining the situation, and the underwriter approved it based on the bank records alone. That probably saved 20 minutes and definitely saved the sale. Not every market allows this kind of flexibility though. Some regions are rigid about the employment letter requirement. Know your local policy before you hit the street. Beyond document gathering, there's the compliance side. Home Credit, like most lending companies, has strict KYC (Know Your Customer) rules. You can't just approve anyone who walks in. There are credit checks, address verification, and sometimes proof of residence visits. Skipping these steps might get you a quick sale, but it'll show up in your pipeline quality score later. Agents with consistently low approval rates or high default rates on their book get flagged. I've seen people lose their agent status because their first 50 applications had an 80% rejection rate from underwriting — mostly due to incomplete or incorrect information. It happens more often than you'd think, especially when agents are rushing to hit daily targets.
Potensi Penghasilan (Income Potential)
Commission structures vary by country, but the general model is base salary plus per-approval commission. In many Southeast Asian markets, the base salary is modest — enough to cover transport and basic expenses while you're building your pipeline. The real money comes from commissions. A typical commission might range from 2 to 5 percent of the loan amount, or a flat fee per approved application. Some markets also offer tiered bonuses: hit your monthly target by a certain percentage and you get a multiplier on your commissions. Let me give you a concrete example from a market I'm familiar with. A sales agent handling consumer electronics financing might close 8 to 15 loans per week. If the average loan size is around $400 to $800 and the commission is 3 percent, that's roughly $10 to $24 per loan. Monthly, that could add up to $320 to $1,440 in commission on top of the base salary. Not bad for entry-level work. But here's the thing nobody puts in the recruitment brochure: the conversion rate is brutal. You might talk to 30 people to get one approved loan. Ten of those conversations will end because the person doesn't meet the income threshold. Five will drop out during the document phase. Eight will simply not show up for the follow-up. That leaves maybe two or three who actually complete the process, and of those, the underwriter might reject one or two more. Your activity metrics look impressive but your close rate tells a different story. Another thing about income that isn't always clear: you don't get paid on every application you submit. You only get commission on successfully disbursed loans. And even then, some companies structure it so that a portion of your commission is held back if the customer defaults within the first few months. I had a colleague who lost about 15 percent of his quarterly commission because three of his loans defaulted within 90 days. It stings, but it's designed to make you care about who you're lending to in the first place.
Get the Full Details

What Beginners Miss
The biggest blind spot I see is assuming this is a pure sales job. It's not. It's a credit sales job, which means you need to understand basic creditworthiness indicators before the underwriter does. If you send someone to application who clearly doesn't qualify — unstable income, multiple existing debts, no verifiable address — you're wasting everyone's time and damaging your reputation with the underwriting team. Agents who build good relationships with their underwriters tend to have smoother processes. Sometimes a quick phone call to explain a borderline case can mean the difference between rejection and approval. The second thing is timing. Loan demand isn't uniform across the year. In many markets, there's a clear spike around holiday seasons — December in most places, or the local equivalent. Electronics retailers push harder, customers have more spending motivation, and your pipeline naturally fills up. The months between holidays are slower, and that's when a lot of agents burn out because they're used to easy closings. My advice is to treat the quiet months as relationship-building time. Focus on maintaining contact with previous customers who might need refinancing or know someone who does. Word of mouth matters more than you'd expect in this business.
The Downsides
I should be clear about what this job doesn't offer. The work is outdoor-heavy. You're not sitting in an office all day. You're traveling to customer locations, meeting at cafes, going to retail stores, sometimes walking through neighborhoods. Weather, traffic, and safety are real factors. In some cities, you'll need to be selective about where you go after dark. The income is also inconsistent until you build a steady pipeline. The first two to three months are usually the hardest because you're still learning the product, the system, and how to screen customers effectively. If you need guaranteed stable income right away, this isn't the role for you. There's also the stress of collection awareness. Even though you're not the one collecting payments, you're often the first point of contact when a customer has questions about their repayment schedule. Some customers will call you directly if they're struggling. You need to know your escalation path — who to forward those calls to — and not overstep your authority. I once told a customer she could defer her payment for two months, which I didn't have the authority to do. The collections team had to step in and fix the situation. It was awkward for everyone. Just stick to the scripts they give you and never promise something you can't deliver. If you're looking for a more traditional sales role with less regulatory overhead, something like direct retail sales or B2B services might be a better fit. Home Credit's model works if you're comfortable with structured processes, patient with rejection, and disciplined enough to manage your own pipeline without constant supervision. The income potential is real if you treat it like a numbers game played smartly, not a get-rich-quick scheme.
Getting Started
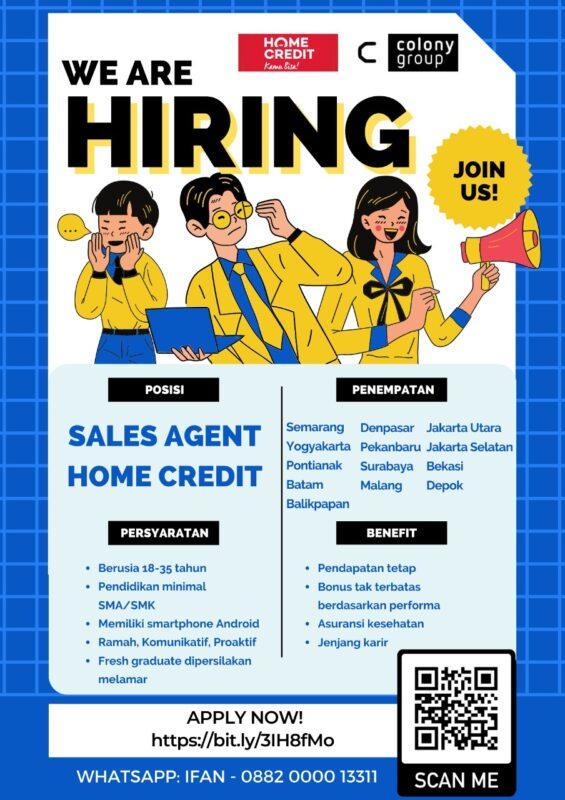
To apply, you'd typically go through Home Credit's official career page for your country or partner with an authorized recruitment agency. Requirements usually include a high school diploma or equivalent, a clean record, and basic computer literacy since most applications are now digital. Some markets require you to have your own vehicle or motorcycle for travel. Training is provided but it's mostly self-driven after that — you'll get product manuals, system tutorials, and compliance guidelines, but the real learning happens on the street. The system you'll use varies by region. In Indonesia, for example, agents use a mobile app to capture customer photos, scan IDs, and submit applications in real time. In other markets, it might be a web portal on a laptop. Get comfortable with whichever tool you're given early. I've seen agents waste weeks struggling with the app interface when they could have been closing deals. A thirty-minute walkthrough with a senior agent at the start saves you enormous time later.