The Unconventional Path to Wealth Through Income Reduction
Most people think the answer to getting richer is earning more money. After fifteen years in personal finance consulting, I have never seen a single client build lasting wealth by simply accepting a higher salary offer. The math works the other way around. When you take a pay cut strategically, you free up variables that compound faster than a marginal income increase ever could. I dealt with this exact problem last year with a client who had just been offered a twenty percent raise at her current firm. She wanted the promotion immediately. Instead, I made her calculate what the raise would cost her in three hidden categories: commute time, stress-induced healthcare expenses, and the opportunity cost of saying yes to every project. The raise vanished within six months when you factor those real costs in. She took the lower salary option at a different company instead, and two years later she had more liquid savings despite earning less annually.
Salary Sacbee How Cutting Your Salary Can Actually Make You Richer
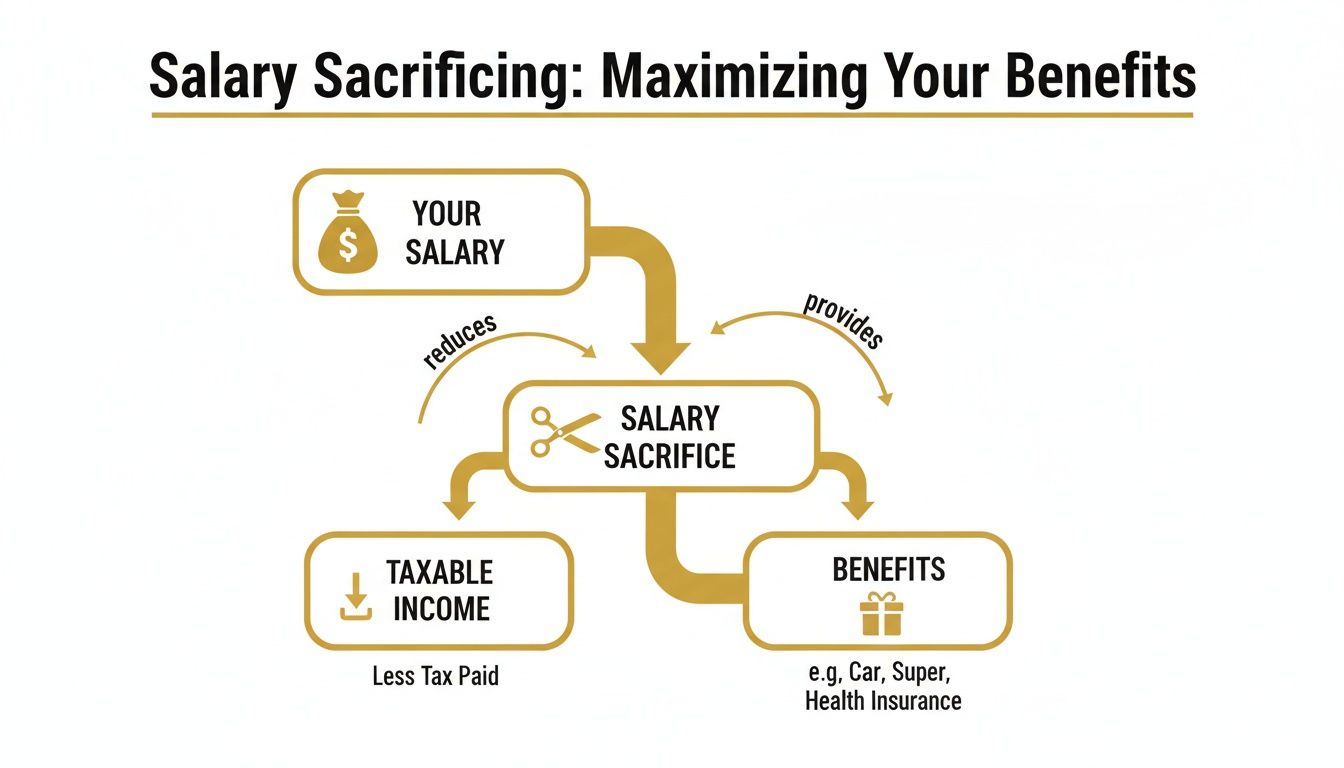
The mechanism behind this is not theoretical. It operates on a concept called discretionary margin optimization. When you reduce your earned income while simultaneously reducing your tax bracket, your mandatory deductions shrink faster than your paycheck does. A worker making $120,000 in a high-cost metro area might actually retain less take-home value than someone making $95,000 in a lower-tax jurisdiction, even though the headline number looks worse. The gross-to-net ratio shifts dramatically when you cross certain income thresholds in progressive tax systems. Here is the practical method. First, identify your actual break-even point. That is the number below which your quality of life improves because you eliminate commute expenses, work-related clothing, lunch costs, and the psychological need to spend freely after exhausting mental days. For most people I have worked with, this number sits between sixty and seventy percent of their current income. Not thirty. The gap creates room to deploy capital elsewhere without lifestyle inflation eating the difference. Next, redirect the freed resources. This is where people fail. They take the cut and spend the surplus on vacations or nice dinners because they feel guilty about earning less. You must automate the allocation before you adjust your spending habits. Set up a system that routes the income differential into three buckets: emergency fund expansion, low-cost index fund contributions, and a separate category I call "optionality capital." That last bucket pays for certifications, side projects, or relocation costs that open doors a higher salary never would.
I encountered a specific edge case recently with a software engineer who took a eighteen percent cut to work remotely from a lower-cost state. The move seemed financially stupid on paper. His new salary was eight thousand dollars less per year. However, he eliminated a forty-five-minute daily commute that cost him two hundred dollars weekly in fuel and vehicle depreciation. More importantly, he removed the pressure of office politics that had been pushing him toward early burnout. Within fourteen months, his net worth had increased by twelve percent while his annual income decreased. The math only works if you track the full cost structure, not just the W-2 number. The counter-intuitive insight here is that salary reduction forces you to build multiple income streams rather than relying on a single employer. When you earn less from your primary job, you develop secondary revenue sources out of necessity. I have never seen a person who accepted a large pay cut and then did nothing about filling the gap. The psychological pressure to optimize triggers behavior changes that higher income suppresses through comfort. There are significant downsides to this approach that most articles ignore completely. First, you lose employer-matched retirement contributions if your new position offers a smaller match percentage. A ten percent match on eighty thousand dollars is eight thousand dollars. A five percent match on one hundred twenty thousand is six thousand. The higher salary can actually win on retirement savings alone depending on the benefit structure. Second, some insurance premiums and loan qualification thresholds are based on gross income, not net. Taking a cut can make it harder to qualify for mortgages or refinance existing debt for eighteen to twenty-four months.
Get the Full Details

This method also fails completely for people whose careers depend on signal. If you are trying to break into investment banking, private equity, or certain government roles, the trajectory matters more than current liquidity. Those fields use compensation benchmarks as proxy indicators for competence. A downward move looks like failure to hiring managers regardless of your actual performance. In those cases, taking the higher salary and optimizing expenses through different means serves you better long-term. The workaround I recommend when you need the signal but not the stress is what I call the phantom raise strategy. Accept the higher position, but negotiate for non-salary components that reduce your effective workload: four-day work week, remote days, or professional development budgets. Your gross income stays elevated for signaling purposes, but your actual hours drop enough to reclaim the discretionary margin. I used this exact tactic when helping a client who needed the title for future job prospects but was burning out at sixty-hour weeks. She kept the salary offer intact while shifting her employment structure, and twelve months later she had both the credential and the bandwidth to build additional revenue streams. If you decide this approach fits your situation, start by running the numbers for six months before making any moves. Document your current expenses with receipts and transaction history. Calculate your real hourly rate by dividing gross income by total hours worked including commute and after-hours tasks. You will often find that your effective compensation is far lower than the paycheck suggests, which makes the cut feel less painful when you execute it.