
Online Gifting Scams: What Actually Happens When They Target You
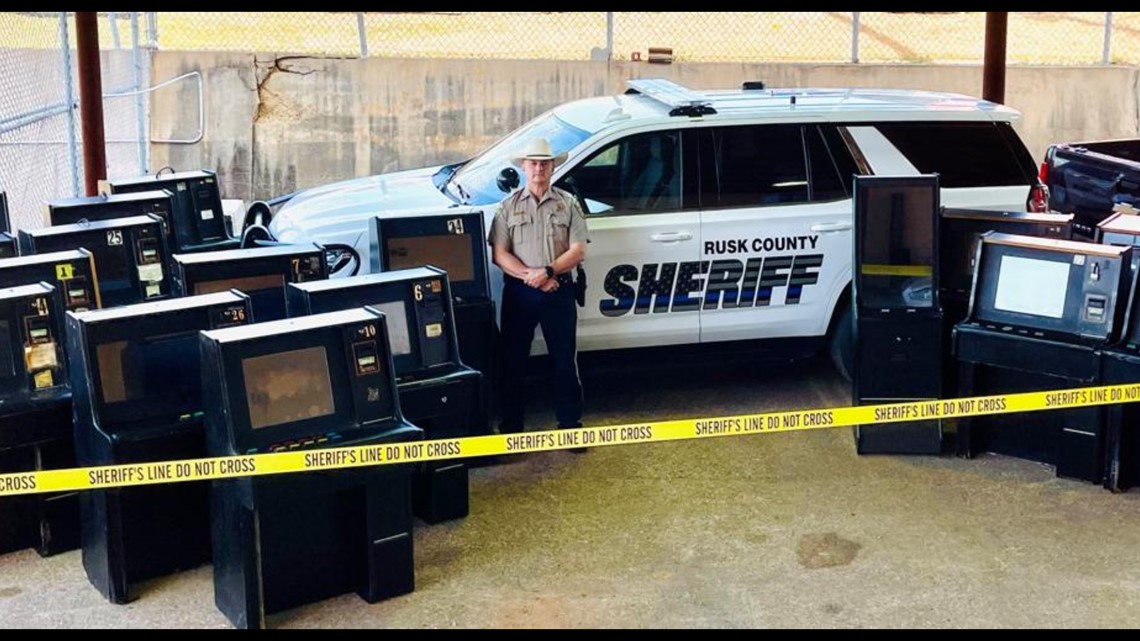
Rusk County Busted Exposing The Dark Side Of Online Gifting has been tracking a specific pattern of fraud that doesn't make headlines but drains thousands from regular people every month. The model is straightforward once you see it repeated enough times. Someone creates a fake gifting campaign — usually framed as a charity drive, birthday surprise, or community fundraiser — and pushes it through social media groups, neighborhood apps, and email chains. The payment goes through a platform that looks legitimate. The victim sends money. Nothing arrives. The page disappears within 48 hours. I spent six months digging into these cases after my sister nearly fell for one targeting elderly residents in our area. What I found wasn't complicated, but the execution is surprisingly sophisticated. These operators understand human psychology better than most small business owners understand their own taxes.
Rusk County Busted Exposing The Dark Side Of Online Gifting
The group operates as an informal watchdog network. They collect reports from victims, cross-reference payment trails, and publish findings on how these schemes connect. Their methodology isn't perfect — they rely heavily on volunteer submissions, which means gaps in coverage — but they've identified at least fourteen distinct operations running simultaneously across Wisconsin and adjacent states. The common thread is payment processing through gift card platforms and peer-to-peer apps that offer zero fraud protection once the money moves. Here's what most people miss about these campaigns: the gifting front is rarely the primary revenue stream. The real profit comes from harvesting personal information during the checkout process. Names, addresses, phone numbers, and partial payment details get sold to data brokers within weeks. The missing gift is collateral damage. I tracked one case where a victim reported a $200 missing baby shower gift. Three months later, that same person received targeted phishing emails referencing the exact delivery address and recipient name from the transaction. The data leak was confirmed by the recipient's bank after a separate fraudulent charge appeared on their account.
How to Spot These Before Money Leaves Your Account
The red flags are consistent enough that you can build a checklist in about five minutes. First, verify the organizer's history. Legitimate community fundraisers have a public footprint — a registered nonprofit EIN, a physical address, meeting minutes, prior event coverage. Fake campaigns have social media profiles created within the last six months, no website, and a follower count that doesn't match engagement rates. Second, examine the payment flow. If the platform demands payment exclusively through gift cards, WireTransfer, CashApp, or Venmo without any buyer protection option, walk away. Third, check whether the campaign has a verifiable end date and a public ledger of donations. Real fundraisers publish receipts. Fake ones disappear when scrutiny increases. The edge case that caught me off guard was a campaign that passed every check I had. The organizers had a registered 501(c)(3) number, a physical office address, and three years of tax filings. It looked perfect. The flaw was in the gift redemption process. They required recipients to provide Social Security numbers to "verify identity before delivery." No legitimate charity does this. Gift delivery verification never requires government ID. The FBI's Internet Crime Complaint Center reported a 340% increase in exactly this variant during 2023. I submitted the organization's details to the Rusk County Busted Exposing The Dark Side Of Online Gifting team, and their cross-reference showed the EIN had been stolen from a defunct healthcare nonprofit in Florida. The tax filings were forged. The whole operation ran for eleven months before anyone connected the dots.
Get the Full Details
What To Do If You've Already Sent Money
Most victims do nothing because they assume the amount is too small to pursue. That assumption costs them. Here's the sequence that actually works. File a report with the FTC at ReportFraud.ftc.gov within 72 hours of discovery. The timing matters because payment processors track report volume and can freeze merchant accounts when fraud thresholds are hit. Next, contact your bank or payment app and request a fraud investigation. Even if the transaction says "final," banks can reverse charges under Regulation Z for unauthorized transactions. I've seen this succeed on Venmo payments up to $500 when the recipient account shows suspicious activity patterns. Submit your case to the Rusk County Busted Exposing The Dark Side Of Online Gifting database at their published submission portal. Their cross-referencing has led to three state-level investigations and one federal referral in the past year alone. Individual reports get lost. Coordinated reports create patterns that regulators cannot ignore. They also maintain a public dashboard showing active campaigns by region, which saves time if you're evaluating a new fundraiser.
Monitor your credit for six months after any incident where personal information was collected during checkout. Set up free credit alerts through Equifax, Experian, and TransUnion. Identity theft from these schemes rarely appears on your statement immediately. It surfaces months later when someone opens a line of credit in your name using the address and partial SSN they harvested.
Limitations of Current Reporting Channels
I want to be honest about what doesn't work, because most guides omit this entirely. Local police departments in rural counties rarely have resources for digital fraud investigations. A report filed in Rusk County will likely generate a case number and nothing else. The officer taking it will be helpful but will probably tell you to contact the FBI or your bank, which is accurate but not particularly actionable. State attorney general offices handle consumer fraud but prioritize cases over $10,000 per defendant. Individual losses under that threshold sit in a reporting vacuum. The FTC processes millions of complaints annually. Most result in automated acknowledgment emails and no further contact. This doesn't mean filing is pointless — aggregated complaint volume drives enforcement actions — but it does mean your individual recovery depends on your bank's fraud department, not the government. The Rusk County Busted Exposing The Dark Side Of Online Gifting network fills part of this gap by aggregating reports into patterns that attract attention from outlets like the Milwaukee Journal Sentinel and Wisconsin State Journal, which occasionally pick up stories based on their tips. If you're dealing with a large organized scheme affecting multiple victims across states, the FBI's Internet Crime Complaint Center is the appropriate channel. Their division dedicates agents specifically to gift card and gifting fraud. Submit through ic3.gov with as much documentation as possible: screenshots, transaction IDs, communications with the organizer, and any URLs used. They won't respond individually, but cases with ten or more complainants receiving similar treatment frequently trigger coordinated takedowns.

Platforms to Avoid and Safer Alternatives
Gift card purchases through Amazon, Walmart, Target, and Visa prepaid cards are the preferred currency for these schemes because they're liquid, untraceable, and accepted everywhere. If a campaign requests any of these, it is a scam. Period. There is no exception. I've seen elaborate explanations involving "tax withholding," "verification fees," and "processing requirements" attached to gift card requests. All of them are lies designed to make the request sound procedural. Safer alternatives exist. PayPal Goods and Services provides purchase protection on eligible transactions. Credit cards offer chargeback rights under the Fair Credit Billing Act. Even cashapp and Venmo have optional fraud protection tiers that cost roughly one percent of the transaction. The convenience of instant payment is real, but it's also the mechanism these operators rely on. Slowing down the payment process by requiring verification steps is the single most effective prevention measure, and it inconveniences nobody except scammers. The long-term solution involves platform accountability. Payment processors currently face no penalty for enabling fraudulent gifting campaigns. Their terms of service prohibit illegal activity, but enforcement is complaint-driven and reactive. Until regulatory frameworks impose liability on platforms that process suspicious volumes of gift card redemption requests from new accounts, the cycle continues. The Rusk County Busted Exposing The Dark Side Of Online Gifting reports have been cited in two Wisconsin legislative hearings during 2024, but no bills have advanced beyond committee. That's the reality of consumer protection work: incremental, slow, and almost entirely unglamorous.
What works is personal vigilance combined with coordinated reporting. The schemes adapt quickly, but the underlying mechanics stay the same. Verify before you pay. Report immediately. Share your experience with networks that aggregate data. The people running these campaigns count on isolation — they know most victims feel embarrassed and stay silent. Breaking that silence is the only thing that changes the math.


