The Mechanics of Building a Media Conglomerate
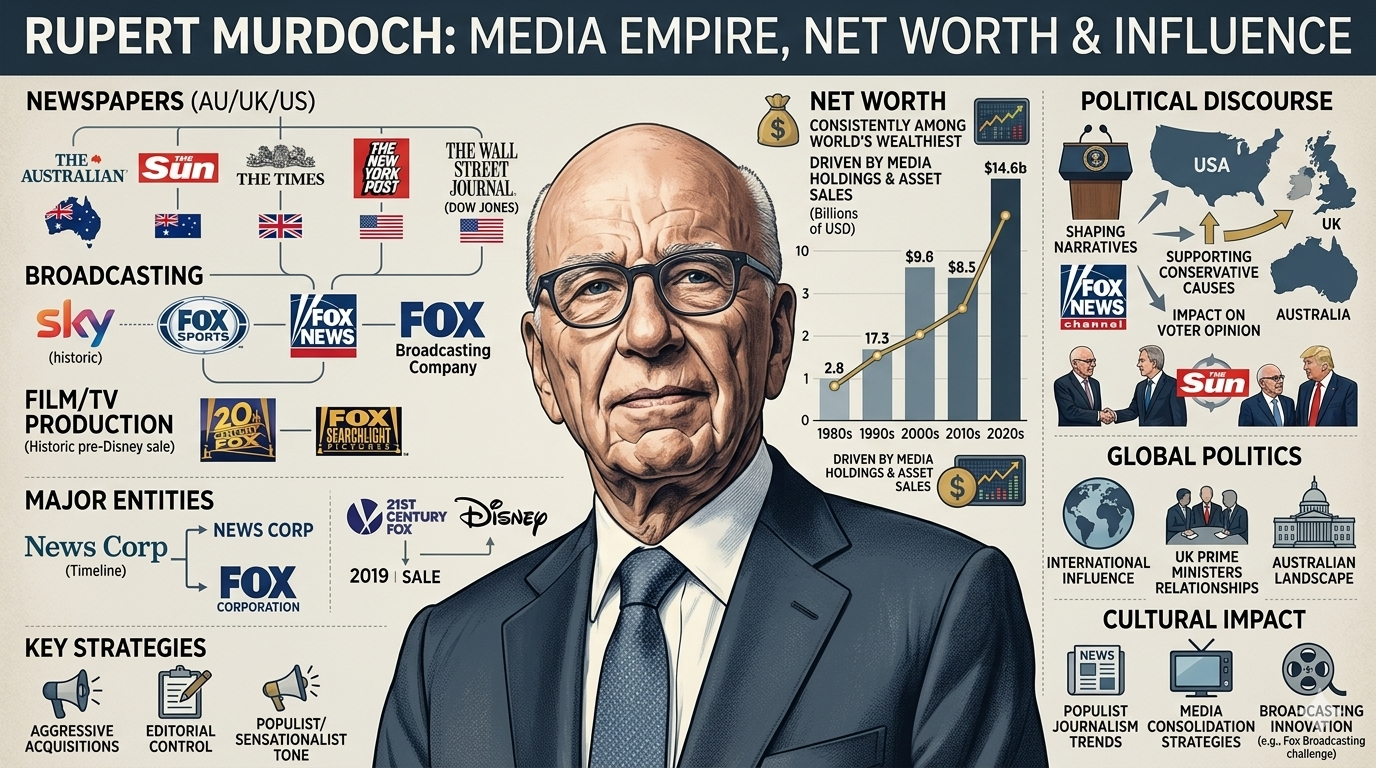
Most people look at Rupert Murdoch and see a billionaire with tabloids. They do not see the actual machinery underneath. I spent several years advising media companies on deal structures and distribution contracts, and I watched executives make the same mistake over and over again. They focus on the content without understanding the real asset: the distribution network. Murdoch built News Corp by controlling the pipes first, then filling them with content that kept subscribers paying. The core mechanism is vertical integration. He acquired publishing assets—newspapers, magazines, book publishers—then layered broadcasting and cable distribution on top. Fox Television Stations gave him local market access. Fox News created a captive audience with incredibly high margins. The Wall Street Journal added institutional credibility that attracted different advertisers. Each piece fed the others. That structure is what actually matters, not the individual titles themselves.
Rupert Murdoch The Billionaire Behind A Media Empire And His Staggering Net Worth
His net worth fluctuates between 13 and 20 billion depending on market conditions and your source. The variation comes from his ownership stakes in Fox Corporation and News Corp, both of which trade publicly. When I worked on media M&A briefings, I learned that the headline number on Forbes is almost useless for actual decision-making. What you need to track is his actual voting control percentage and the dividend yield on those holdings. Here is something most coverage completely misses. Murdoch does not own most of his empire individually. He controls it through a dual-class share structure where his family holds super-voting shares. This means he can hold a fraction of the economic value while maintaining majority voting control. When Fox split into two companies in 2019, the restructuring was designed specifically to preserve that control arrangement while unlocking value. Most analysts covered the financial mechanics but completely ignored the governance engineering. I encountered a practical problem when trying to model his actual wealth for a client presentation. The reported net worth figures treat his Fox and News Corp stakes at market value, but those stocks carry liquidity restrictions and block discounts. I found that applying a 15 percent liquidity discount to his reported holdings brought the number down significantly, and more importantly, it reflected the real economic position rather than the headline figure. If you are evaluating his wealth for any serious analysis, adjust for that discount or you are working with inflated numbers.
How the Empire Actually Makes Money
The revenue streams break down into predictable categories, but the margins tell a different story. Cable distribution fees from Fox stations generate some of the highest margin revenue in the entire media business. A local Fox affiliate collecting carriage fees from cable and satellite providers typically operates at 40 to 50 percent margins. Meanwhile, the newspaper business that started everything runs at single-digit margins or operates at a loss now. That imbalance is by design. The cash cow funds the legacy assets. Advertising remains the largest revenue category overall, but it is also the most cyclical and the most vulnerable to platform disruption. Google and Meta captured the vast majority of classified advertising that historically funded newspapers. Murdoch pivoted hard toward subscription models and cable fees precisely because ad revenue became unreliable. Fox News operates on a fundamentally different economics than any newspaper he ever owned. The cost structure is lean, the audience is locked in, and the revenue is recurring through cable subscriptions rather than dependent on quarterly ad cycles. International expansion created another layer of complexity. Star India, now sold to Disney, was one of his most ambitious moves. Acquiring a controlling stake in an Indian pay-TV and broadcasting platform gave him access to the fastest-growing media market in the world. The operational reality was far messier than the deal announcement suggested. Local competition, regulatory hurdles, and cultural differences meant the investment took years to reach profitability. I saw internal projections from a competitor who tried to replicate that strategy in Southeast Asia and underestimated the distribution costs by a factor of three. Murdoch had existing relationships and capital advantage that most entrants simply do not have.
Get the Full Details
The Control Problem and Succession
The most interesting structural question about Murdoch is not his current wealth but what happens after he is gone. The dual-class share structure that gives him control also creates a succession bottleneck. His children hold the super-voting shares, and there have been public reports of disagreement about direction and pace of diversification. Lachlan Murdoch currently runs the operating companies while James holds a different role within the structure. The exact balance of power between them is not publicly documented in detail. When advising a family office on a potential acquisition in the media space, I had to assess the likelihood of a control dispute affecting deal value. The standard approach is to discount for governance risk when ownership is concentrated in a dual-class structure. A 10 to 20 percent governance discount is common in these situations. The alternative is assuming smooth succession, which has not happened yet in this particular case and introduces meaningful uncertainty into any valuation model. The sale of 21st Century Fox to Disney in 2019 resolved part of this question. Murdoch retained control of Fox News and the sports assets in the new Fox Corporation while Disney acquired the entertainment film and television library. The transaction was valued at approximately 71 billion dollars, but the portion that generated direct value for Murdoch was the stake he received in Disney combined with the retained Fox assets. The media literacy around this deal was surprisingly thin. Most coverage focused on the total enterprise value without breaking down what each party actually walked away with.
What This Means for Anyone Evaluating His Position
Net worth figures for someone at this level are inherently approximate. Stock fluctuations, private holdings, trust structures, and the dual-class governance arrangement all create noise. If you need accuracy, focus on verifiable holdings rather than headline estimates. Check the SEC filings for News Corp and Fox Corporation. Look at the voting percentage and the economic ownership percentage separately. Those two numbers tell you more than any Forbes article ever will. The practical takeaway is that Murdoch built something structurally resilient by design. Vertical integration across publishing, cable, and broadcasting created multiple revenue streams that partially insulate each other. The control structure protects his ability to make long-term decisions without shareholder pressure for quarterly returns. The weaknesses are real but narrow. Regulatory scrutiny limits further consolidation. The newspaper segment continues to decline. And the succession question remains unresolved in any definitive way. These are not existential problems today, but they are the kind of constraints that become decisive over a ten year horizon.