Understanding Promotional Financing at Furniture Retailers
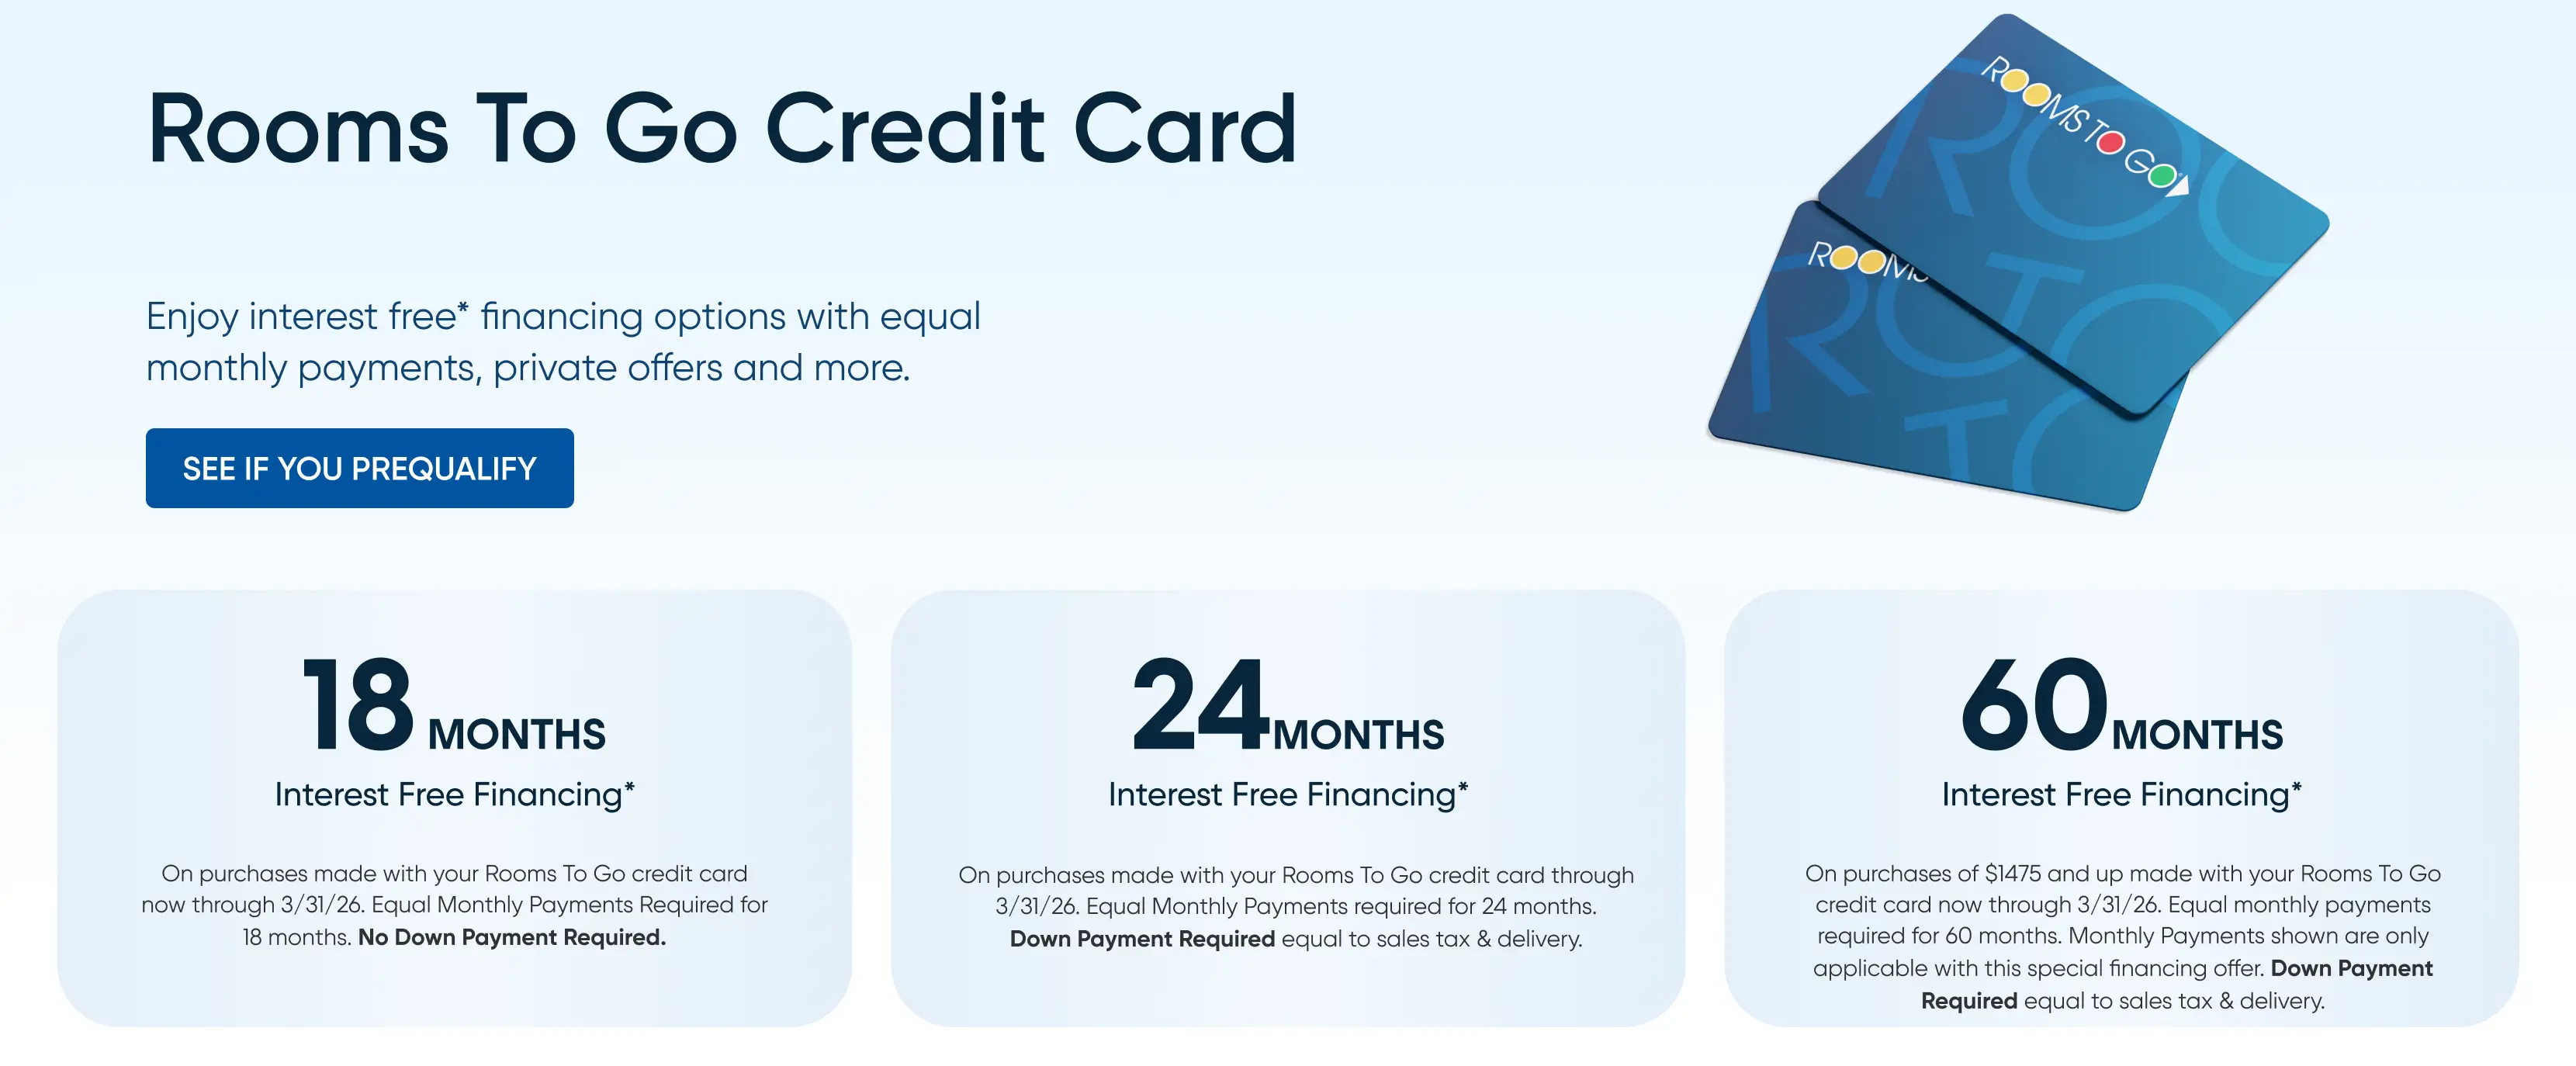
Zero percent financing sounds like a gift, but anyone who has worked retail lending knows it is one of the most misunderstood consumer products in the furniture space. Rooms To Go and similar big-box retailers advertise these deals heavily because they work for the store more often than they work for the customer. The math is straightforward when it plays out perfectly. You finance a $3,000 sofa and entertainment center at 0% APR for 24 months. You pay $125 a month on time. At the end, you owe nothing extra. That saves you roughly $300 to $500 in interest compared to a standard 18% to 24% furniture card offer. In that narrow window, yes, it saves money. The problem is that window is fragile. Most of these promotional offers are actually deferred interest, not true zero-percent loans. The interest is not waived; it is deferred. If you miss a single payment by even one day, or if you do not pay off the full balance before the promotional period ends, the retailer applies retroactive interest to the entire original purchase amount at the contract's standard APR, which typically runs between 25% and 35%. On a $3,000 purchase over two years, that retroactive charge can easily exceed $1,200.
I learned this the hard way with a customer back in 2019. A woman came in to pay off her financed dining set ahead of schedule. She had been making on-time payments for 23 months on a 24-month promotion. She paid the remaining balance, but the system charged her $847 in retroactive interest. The reason was simple: she had a single $125 payment that posted five days late because her bank had a system outage. Five days. One occurrence. The contract did not have a grace period that applied to promotional accounts the way most people assumed it did. The workaround, which took another hour of phone calls and supervisor escalations, was getting her bank to submit a formal good-will adjustment letter citing the outage, then having the Rooms To Go financing partner void the retroactive charge as a one-time courtesy. It worked, but it took three days and two supervisors. Most people do not go through that. They just absorb the charge. Another detail people consistently miss is that promotional financing through furniture stores usually runs through third-party consumer finance companies like Synchrony Bank or Ocwen Consumer Solutions. These are not store credit cards in the traditional sense. They operate under completely different billing rules. Your minimum payment calculation, your billing cycle dates, and your late payment reporting to credit bureaus can differ from what you are used to with a Chase or Citi card. The statements are often misleading about the remaining promotional window. You might look at your account and think you have eight months left when the system has already locked in a higher minimum payment that will not clear the balance in time. There is also a subtlety around partial payments. Some of these contracts require you to pay the full statement balance each month to maintain the promotional rate. Paying only the minimum, even if it is on time, can void the 0% offer entirely and trigger immediate retroactive interest. I have seen this trip up people multiple times because their autopay was set to the minimum payment amount. The payments were always on time. The promotional rate was still revoked because the full balance was never paid.
If you decide to use this kind of financing, here is what actually matters. Get the exact payoff amount in writing before you leave the store. Not the monthly payment. The full remaining balance as of any given date. Ask specifically whether the promotion is true 0% APR or deferred interest. Read the contract language around what happens if a payment is late by even one day. Set your autopay to the full statement balance, not the minimum. Set a calendar reminder for the final month showing the exact payoff figure so you can clear it early and avoid any end-of-term surprises. The alternative route that fewer people consider is a personal loan from a credit union. You would pay maybe 8% to 12% interest over three years, but there is no retroactive clause. No deferred interest bomb waiting at month 24. You know exactly what you owe from day one. For most people, that predictability is worth more than the theoretical savings of a promotional furniture deal. 0% financing can save you money if you are disciplined, organized, and actually read the fine print. Most people are none of those things when they are standing in a furniture showroom deciding between a sectional and a loveseat. The house payments are not going to wait for you to figure out your billing cycle. That is why these promotions exist.
Get the Full Details