Understanding Romania's 2023 Economic Picture
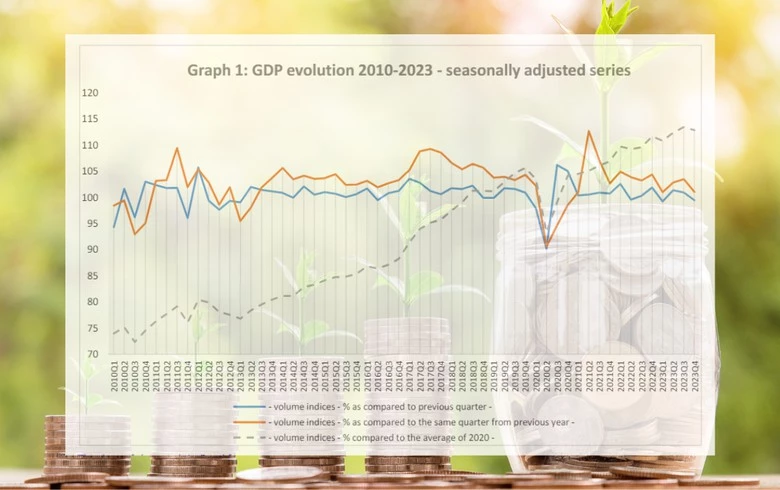
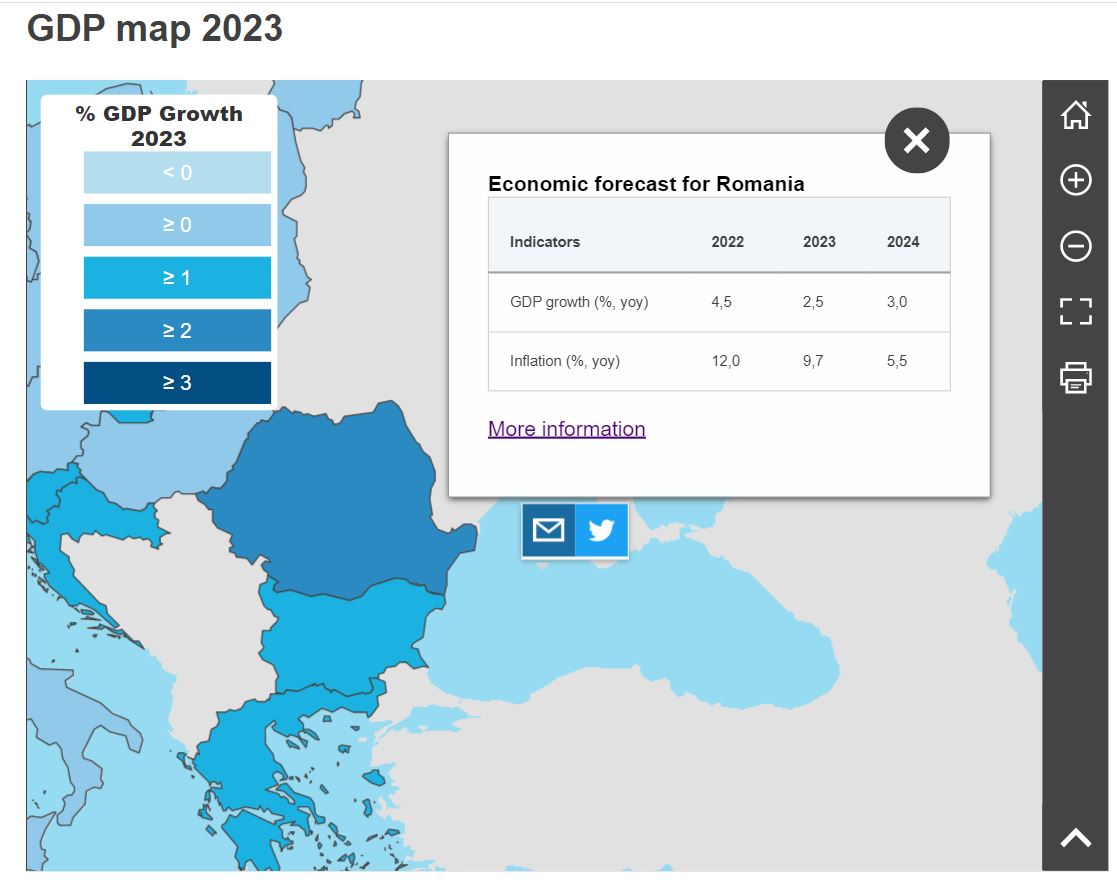
Looking at Romania's GDP data for 2023 requires context most summaries skip. The official growth figure landed around 2.5% to 2.8% depending on which source you consult, but those numbers don't tell the whole story. The economy grew, sure. It also fought inflation hovering near 9% for much of the year, dealt with uneven EU fund absorption, and navigated energy price shocks that hit industrial output particularly hard. Here is how I break it down when someone asks me to explain what actually happened. First, you look at nominal GDP versus real GDP. Nominal GDP for Romania in 2023 came in somewhere above 300 billion euros, but nominal figures are misleading if you are trying to understand real economic performance because they include price level changes. Real GDP adjusted for inflation is where the actual growth story lives. That's the number that matters for things like wage comparisons, investment decisions, and policy evaluation. The main drivers were domestic consumption and the construction sector. Consumption held up better than many economists predicted going into the year. That sounds counterintuitive given the inflation rate, but household savings accumulated during the pandemic years provided a buffer. People spent down some of those reserves. The construction sector benefited from EU fund-driven infrastructure projects, though disbursement was uneven across quarters.
One thing beginners miss when analyzing this data is the sectoral composition. Industry actually contracted in real terms for parts of 2023, particularly manufacturing. Automotive production, which is significant for Romania, dealt with semiconductor supply chain aftershocks and reduced European demand. Services carried the growth load. Tourism rebounded strongly. IT and business services continued their expansion trajectory. So the growth was real but narrow in its foundations. I ran into a specific problem last year when compiling a cross-sector analysis using data from INS, the Romanian National Institute of Statistics. Their quarterly GDP release methodology changes timing slightly between publications. The first estimate is always provisional, then revised in the second and third releases. If you are pulling data from different quarterly publications without noting the revision status, your year-over-year comparisons will be wrong. The workaround is simple but easy to overlook: always cross-reference the latest revised figure against the original estimate and note the revision delta in any analysis you produce. The revision for 2023 GDP growth was roughly 0.2 to 0.3 percentage points between the first and final estimates, which sounds small but changes the narrative significantly when you are making investment-grade recommendations. The inflation dynamics deserve their own section because they directly impact how you interpret the GDP numbers. The National Bank of Romania kept interest rates elevated through much of 2023, with the reference rate sitting at 7% for a considerable stretch. High rates slow credit growth, which eventually feeds into lower consumption and investment. The lag effect is real. You will see the impact of rate decisions in GDP data roughly six to nine months later. That means the full effect of the monetary tightening cycle had not yet materialized in the 2023 annual figure.
Another counter-intuitive point: Romania's current account deficit narrowed during 2023 despite growth. Most people assume growth widens the deficit because higher domestic demand pulls in more imports. In Romania's case, the deficit narrowed because the value of imported energy dropped significantly. Oil and gas prices, while still elevated compared to pre-2022 levels, came down from their peaks. That improved the trade balance enough to offset increased import demand from other sectors. This is the kind of detail that separates a surface-level summary from something actually useful. EU fund absorption remains the structural bottleneck. Romania has access to billions in recovery and resilience funds, plus cohesion policy funds, but absorbing that money is harder than winning the allocation. Bureaucratic capacity, procurement delays, and administrative hurdles eat into the timeline. In 2023, absorption improved compared to previous years but remained below the pace needed to meaningfully close the investment gap with Western European peers. The gap between allocated funds and actually disbursed funds is where the real economic potential sits untapped. If you are using this data for investment or policy analysis, here is what I recommend practically. Get the data directly from INS at ins.ro rather than aggregators. Check the quarterly releases, not just the annual summary. Look at the sectoral breakdown by NACE codes. Compare nominal and real figures side by side. Factor in the revision history. Cross-reference with National Bank of Romania monetary and financial statistics. The picture that emerges is more nuanced than any headline number suggests.
Get the Full Details
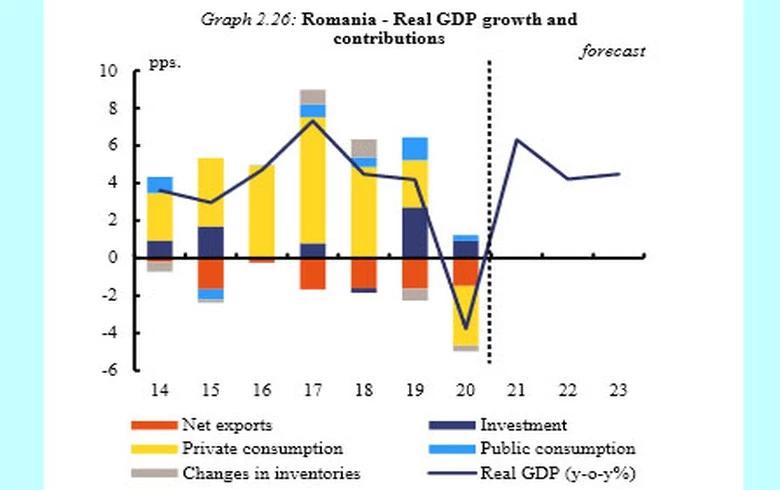
The labor market tells a parallel story. Unemployment stayed near historic lows, below 5% for much of 2023. That supports consumption but creates wage pressure, which feeds back into inflation. The government responded with minimum wage increases that outpaced productivity growth in several sectors. That is a sustainability question for the medium term, not a 2023 problem, but it affects how you read the GDP growth durability. Fiscal policy added another layer. The budget deficit remained above the EU threshold of 3% of GDP for 2023, which triggered infringement procedures from Brussels. Government spending stayed elevated, partly to cushion households from energy costs and partly due to electoral cycle pressures. High deficits in a high-inflation environment create policy tension. The Romanian government chose growth support over fiscal consolidation, which is a defensible position but not one without consequences. Regional variation within Romania matters too. Bucharest and the developed counties consistently outperform rural areas and former industrial regions. The GDP growth figure is an aggregate. It masks significant intra-country divergence. Investment flows, infrastructure quality, and human capital differences drive this split. Any analysis that treats Romania as a single homogeneous economy is missing critical detail.
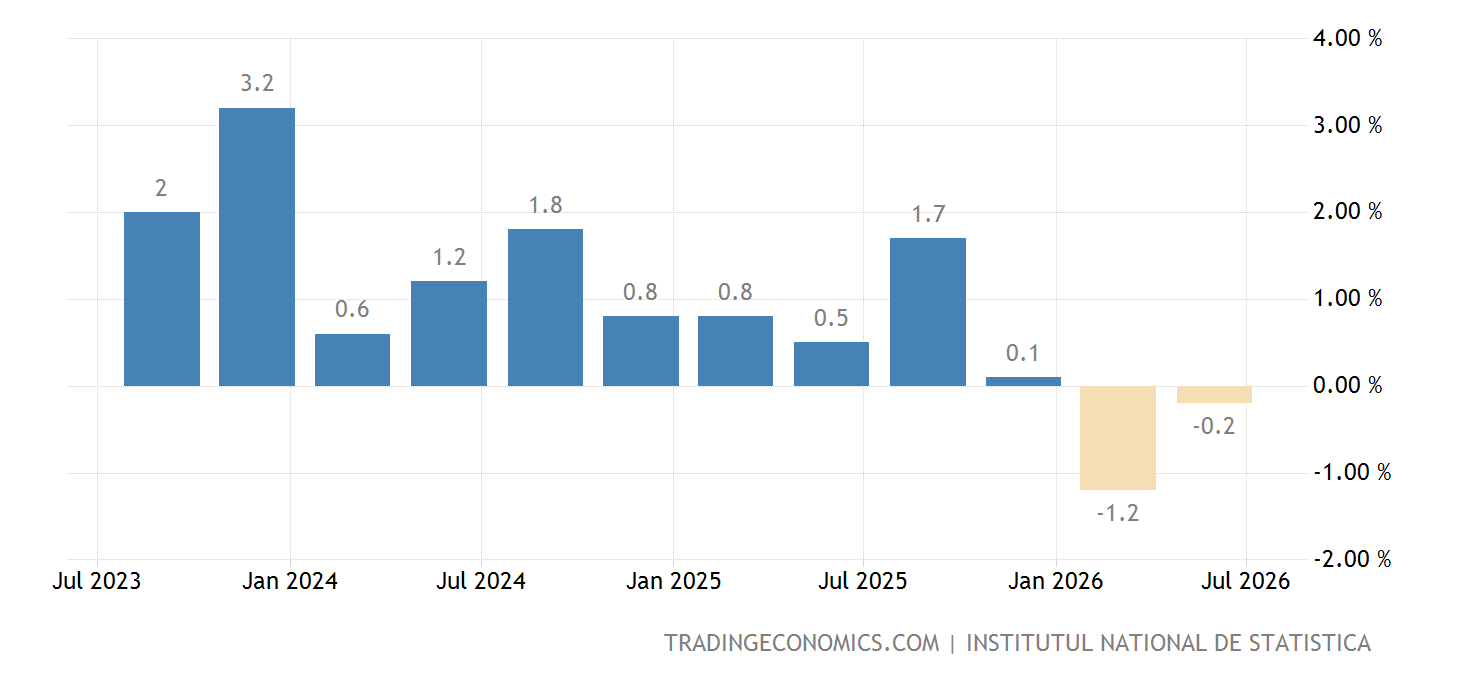
For anyone working with this data regularly, the biggest practical pitfall is treating a single quarter as definitive. Romanian GDP data is volatile quarter to quarter. One quarter can show 3% growth, the next 1.5%, and revisions shift both numbers. The annual trend is more reliable than any individual quarterly snapshot. Budget your analysis time accordingly and plan for at least two data review cycles before drawing conclusions.