Getting through Rocket Mortgage's rates these days takes a different approach than it did three years ago
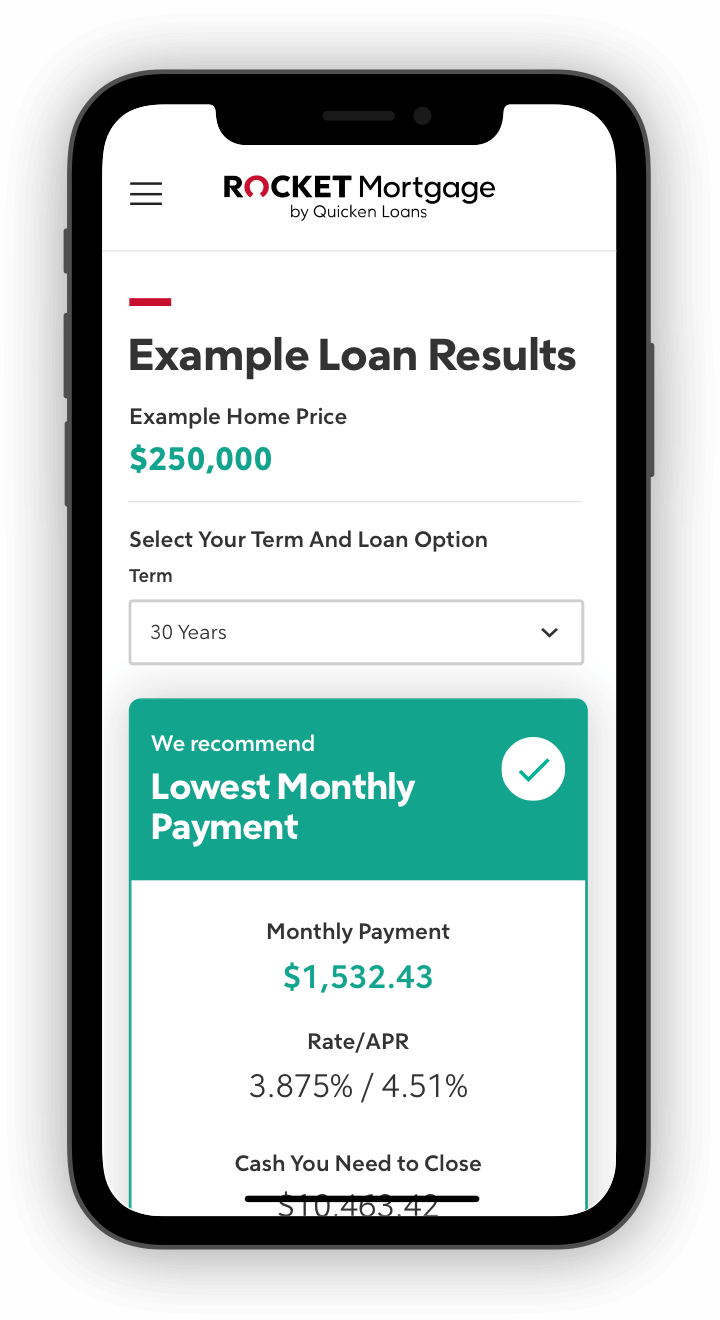
I've been processing and comparing mortgage deals long enough to notice the window for autopilot applications has closed. The rates on Rocket's site right now look decent at first glance, but the real rate you lock depends on a handful of things most borrowers gloss over. Here's what actually moves the needle and where people waste time. First, stop looking at the advertised rate and start looking at the APR and the points structure. Rocket, like most big lenders, will show you a rate that assumes you're paying discount points or meet specific promo conditions. The difference between their headline number and your actual all-in cost can be four or five hundred dollars a month depending on where you qualify. I spent last year going back and forth with a borrower who was fixated on a 6.75% rate she saw online, only to discover it came with two full discount points and an appraisal waiver that didn't apply to her property type. By the time we stripped the points and recalculated, her effective rate was closer to 7.1% and her monthly payment jumped by nearly eighty dollars. That's the gap you need to close before you ever click submit. The process itself is straightforward once you know which inputs matter. You'll need your credit score range, debt-to-income ratio, loan amount, property type, and occupancy status all accurate before you start. The Rocket app will generate rate sheets in minutes, but those rate sheets are conditional. They shift based on how you adjust your down payment, whether you buy points, and sometimes even the county you're buying in. I had a case recently where a borrower in a specific Michigan county qualified for a significantly better rate because of a state-level assistance program layered on top of the loan. Rocket's calculator didn't surface that automatically. I had to flag it through a processor on the operations side and they adjusted the rate sheet within an hour. It wasn't glamorous but it saved the deal from falling apart near closing.
One thing that catches people off guard is how quickly rates move inside Rocket's platform during the application funnel. You'll input your details, get a rate hold, and then return an hour later to find it shifted by a quarter point or more. That's not a glitch. Rate locks are time-bound and the platform refreshes them based on bond market movement throughout the day. If you're serious about a number, you want to get to a formal commitment letter as fast as you can. That usually means having your documentation ready upfront instead of assembling it while you're watching rates drift. I typically tell people to pull their credit report, gather their last sixty days of bank statements, and get their purchase contract or refi docs in order before they even open the application. It cuts the time from first login to locked rate from about two days down to under four hours for most borrowers. There are tradeoffs worth being honest about. Rocket works best for standard conforming loans on owner-occupied single-family homes with clean credit and straightforward income. If you're self-employed with complex depreciation schedules, buying an investment property, or looking at jumbo loans in high-cost counties, their automated underwriting engine tends to be less flexible than a local broker or community bank. I had a borrower with significant 1099 income and partial documentation who got bounced back twice through the automated system before we moved her to a manual underwrite that took three extra weeks. The rate ended up about a eighth higher than what a regional lender would have offered. That's not a Rocket problem specifically, it's just the reality of large-scale automated processing versus relationship-based lending. Another counter-intuitive detail is that buying rate points through Rocket isn't always the cheapest way to lower your interest. Their point pricing is competitive on standard products but they don't always match the point structures offered by wholesale lenders going through correspondents. For a 30-year fixed at current levels, buying one point might save you half a percent, but the break-even calculation depends heavily on how long you plan to stay in the home. If you're moving in three years, you're better off keeping the higher rate and saving the upfront cash. If you're staying ten or more, the points pay for themselves and then some. Most people skip that math entirely and just pick the lowest rate they see.
Here's a practical sequence that actually works if you want to secure a solid deal right now. Run your numbers on the Rocket site with your real figures, not idealized ones. Compare the APR and total closing cost across at least three different rate-point combinations. Check whether you qualify for any first-time buyer programs or employer partnerships Rocket occasionally offers. If your situation is standard, lock through the platform and move fast on documentation. If it's complicated, use Rocket as a benchmark rate and take that number to a local broker or community bank and ask them to match or beat it with more flexibility. Don't be shy about using one lender's quote against another. It's standard practice and most of them will work with you if you're a serious borrower. The market these days rewards patience and preparation more than speed. The lowest advertised rate isn't the rate you get. The rate you lock depends on your documentation, your timeline, and how well you understand what's included in the price. Rocket Mortgage remains a legitimate option for a large portion of borrowers, but treating it like a self-service kiosk will cost you more than walking in with your numbers ready and a clear comparison in hand.
Get the Full Details