The Ripple SEC Case Has Been Longer Than Anyone Expected
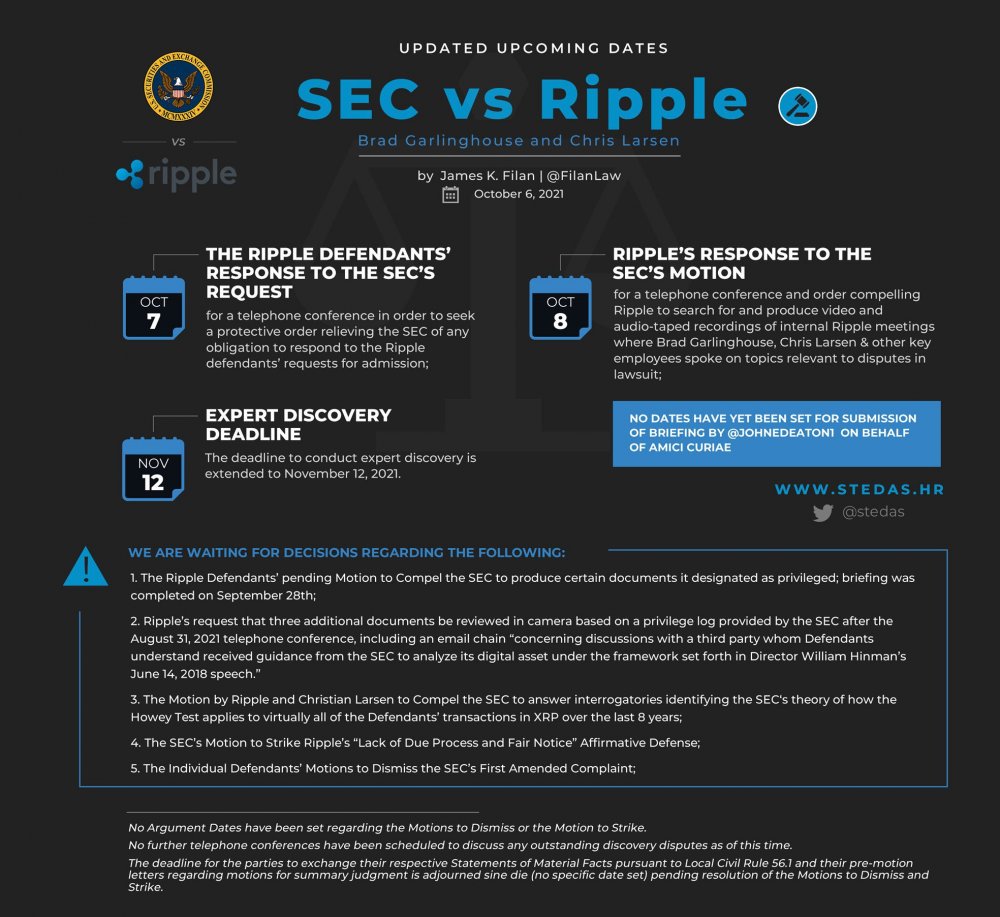
The Ripple vs SEC lawsuit started in December 2020, and depending on how you count, it's still not fully wrapped up. People ask me all the time when this is going to end, like there's a definite finish line. There isn't one. Not really. The case has moved through multiple phases, multiple rulings, and one appellate decision, and the timeline keeps shifting every time either side files a motion or appeals a ruling. Here's what actually happened, in order, without the spin: December 2020: The SEC filed its complaint against Ripple Labs, alleging that XRP sales constituted unregistered securities offerings. Ripple moved to dismiss, arguing XRP is a currency, not a security. This alone took eight months to get to a hearing.
July 2022: Judge Analisa Torres issued her partial summary judgment ruling. She drew a distinction between programmatic XRP sales on exchanges (not securities transactions) and institutional XRP sales directly from Ripple (potential securities offerings). This was the first major win for Ripple, but it also meant the case wasn't over. It just changed shape. October 2023: The penalty phase began. The SEC wanted $2 billion. Ripple wanted nothing. The court ultimately settled on a $125 million civil penalty in December 2023. That felt like a relief until you realize the case still had procedural follow-ups and compliance monitoring to work through. 2024: The SEC appealed certain aspects of the ruling. Appeals add time. A lot of time. The Second Circuit took the case, and oral arguments happened sometime in late 2024 or early 2025. Depending on how the court schedules briefing, you're looking at another six to twelve months before any appellate decision lands.
2025–2026: Whatever comes out of the appeal becomes the final word on the securities law questions. After that, there may be remedial proceedings for the institutional sales portion, and potentially new enforcement actions or settlements with state regulators. This is where people get confused about the "resolution timeline" because the case doesn't resolve cleanly. It fragments into multiple tracks. I've tracked this case since the initial complaint dropped. What nobody tells you is how many procedural motions get filed that have nothing to do with the merits. Discovery disputes. Motions to compel. Amicus briefs from basically every crypto company in existence. I spent about three weeks in 2022 just reading the discovery disputes because they revealed more about what the SEC actually knew about XRP's distribution than any ruling did. The workaround I used was to ignore the headline-making motions and focus on the district court docket entries themselves. Those are public records. You can pull them directly from the Southern District of New York's Pacer system. Filter by case number 20-cv-10852. The raw filings tell a different story than the press coverage. Here's something most people miss about this case: the institutional vs. programmatic sales distinction created a regulatory gray zone that the court never fully resolved. It left open the question of what constitutes an exchange-traded transaction versus a direct offering. That ambiguity matters for any exchange listing XRP, and it matters for any future DeFi protocol that distributes tokens programmatically. The ruling was narrow. It didn't create a blanket exemption for programmatic token sales.
Get the Full Details
Another thing people don't understand: the $125 million penalty, while small compared to what the SEC wanted, was still a settlement-adjacent outcome. The court had discretion on the penalty amount, and Ripple's cooperation with the court's reasoning on the institutional sales side played a role. Had Ripple fought harder on that front, the penalty could have been significantly higher. Or the case could have gone to a different judge who wouldn't have been as sympathetic to the nuances. The biggest bottleneck right now is the appellate process. Federal appeals take time. Even expedited briefing schedules in high-profile cases run 8 to 14 months from notice of appeal to decision. If the Second Circuit affirms the district court's ruling, which most observers think is likely, the case then goes back to the Southern District for any remaining remedial proceedings. That's where the institutional sales question gets resolved definitively. That could add another 6 to 12 months minimum. If you're looking for a clean end date, there isn't one coming. The closest thing to resolution is the appellate decision, and even that won't close every door. State-level actions, new SEC leadership, or regulatory guidance changes could all extend the practical impact of this case well beyond whatever final judgment comes out of it.
The practical takeaway is that the legal questions are mostly settled at this point. The securities law distinction between institutional and programmatic XRP sales stands. What's left is procedural cleanup and potential precedent-setting from the appeals court. The timeline for that cleanup is unpredictable because federal courts don't operate on fixed schedules, especially not for cases with this much publicity and so many interested third parties filing amicus briefs. I stopped trying to predict exact dates about three years ago. The docket moves in fits and starts. A scheduling order gets modified. An amicus deadline shifts. A judge takes a short leave. These things add weeks or months at a time and nobody outside the courtroom notices. The only reliable pattern is that the case resolves in phases, not all at once, and the final phase is always longer than anyone expects.