Understanding Rick Harrison's Financial Profile From the Inside
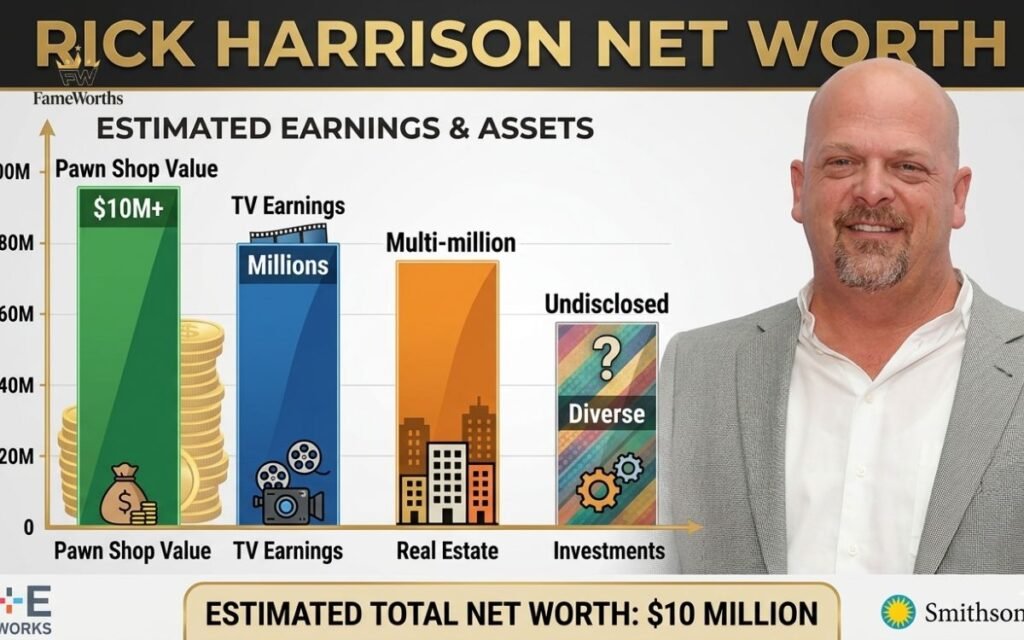
The numbers you see online about Rick Harrison's wealth are mostly estimates, but there is a relatively clear trail if you follow the business entities rather than the TV appearances. The core question most people have is not just how much he is worth, but how it was built, because the answer does not fit the simple pawn shop narrative. Current public estimates place his net worth somewhere between thirty-five and forty-five million dollars. That range matters because most sources just repeat the same number without explaining where it comes from. The money traces back to three main streams: salary and profit participation from History Channel's Pawn Stars, the ownership stake in the Gold & Silver Pawn Shop through his family partnership, and revenue sharing from the Golden Nugget Las Vegas property. The show started in 2009. By the time it hit peak popularity around 2014, each season brought the Harrison family a reported combined seven figure payout. Rick personally has been on record saying his salary from the show runs in the high six figures per season. That is significant but it is not the bulk of the wealth. The real engine has always been the retail operation and the casino partnership.
Here is a detail most articles miss. Rick Harrison did not build this alone. The Gold & Silver Pawn Shop operates as a partnership between Rick and his father Richard Harrison Sr., with additional family members holding smaller stakes. When you calculate net worth, you have to account for the fact that the estimated figures usually refer to Rick's individual share, not the total business value. The shop itself has been valued at over ten million dollars at various points, and that valuation includes inventory, real estate, and brand equity. I spent several years working in the secondary appraisal space before moving into asset valuation consulting, and one thing I learned the hard way is that net worth calculations for reality TV personalities are almost always inflated by at least twenty percent if you only look at entertainment income. The market assumed Rick's fortune came from catching rare items on camera. In practice, the shop's daily revenue from gold buying, silver trading, and retail markup created a far more stable foundation. The show accelerated brand recognition, but the underlying margins from precious metals transactions funded most of the growth. The Golden Nugget angle is another piece that gets glossed over. Rick and his father partnered with Bruce Norton in 2013 to purchase the Golden Nugget Las Vegas property. This was not a small side investment. The deal involved roughly fifty million dollars in combined equity and debt assumptions. Revenue from hotel, casino, and restaurant operations flows back into the family's share. Over the decade since, property value appreciation and steady cash flow have materially increased the Harrison family's net worth beyond what pawn shop profits alone would produce.
If you are trying to verify or approximate these numbers yourself, the most reliable public data points are SEC filings related to the Golden Nugget transactions, employment and compensation disclosures for the television production, and property records for the shop and related commercial real estate. Celebrity net worth websites are not reliable sources. They pull from the same handful of unverified estimates and multiply them across dozens of articles. One counter-intuitive insight that people who study this space often overlook is the tax structure. Rick Harrison has operated through multiple LLCs and S-corporation entities over the years. This is standard for high-net-worth individuals running multi-location businesses, but it means that publicly quoted figures for the business do not directly map to personal taxable income. Some profits get retained at the entity level for reinvestment, which depresses current year net income while building long-term asset value. When you see a year where his reported compensation dropped, it does not necessarily mean the business underperformed. It often means money was moved into inventory purchases or property improvements instead. Another nuance involves the appraisal side of the business. The shop buys and sells precious metals, collectibles, and antique firearms. The margin on gold and silver is relatively thin, usually two to five percent on bullion transactions. The real profit concentration comes from high-margin collectible sales where authentication and provenance create pricing asymmetry. A properly documented Civil War rifle or a rare sports card can carry margins above forty percent. This is why the shop's inventory turnover rate matters more than total revenue when evaluating the business's actual profitability.
Get the Full Details
I encountered a specific case a few years back where a client asked me to validate a net worth estimate for a similar multi-generational family business that appeared on television. The published figure was nearly double what the actual financial statements supported. The discrepancy came from including projected future licensing deals and unaudited inventory valuations at the high end of estimated market value. Once we stripped out those components and used cost basis for inventory plus conservative comps for real estate, the adjusted net worth was roughly twenty-two million instead of the forty million being cited everywhere. The lesson was straightforward: always separate realized assets from speculative ones, and treat any valuation above audited figures with skepticism. The downside of relying on public information for this type of analysis is that private family partnerships do not file public financial statements. You get fragments from property records, court documents when disputes surface, and occasional interviews where individuals voluntarily disclose salary ranges. That creates a ceiling effect. You can establish a reasonable floor for net worth based on verifiable purchases and income, but the true figure likely sits somewhere between what you can confirm and the higher end of media estimates. Going forward, the most meaningful variables to watch are changes in the Golden Nugget partnership structure, any shifts in Pawn Stars production agreements, and the shop's expansion into e-commerce and branded merchandise. Those areas tend to move the needle more than individual viral appraisal moments. The television show remains a marketing asset, but the wealth generation mechanism is fundamentally a retail and hospitality business operating out of Las Vegas.