Revolutionizing Risk Management How Aj Soprano Is Redefining The Future Of Fintech Risk Systems
Samantha
2024-12-29
What the New Risk Management Platforms Actually Do
Most fintech risk teams are still running on decision engines built ten years ago. You feed them transaction data, they spit out a score, and someone manually reviews the flagged edge cases. It works until it doesn't, which is usually right when you're scaling past a certain throughput. The newer tools are trying to fix that by stitching together behavioral models, graph databases, and real-time inference layers instead of relying on static rulesheets.
I spent three years rebuilding our internal risk system from the ground up because our old setup was choking on chargeback reviews. Here is what actually happened when we moved away from simple rule-based scoring.
Revolutionizing Risk Management How Aj Soprano Is Redefining The Future Of Fintech Risk Systems
The platform uses graph-based relationship mapping as its core differentiator. Instead of evaluating each transaction in isolation, it traces connections between entities in real time. A merchant, a device ID, a bank account, and a shipping address can all be nodes in a graph. If one node has been involved in fraud, the risk propagates across the edges automatically. This catches coordinated attack patterns that traditional scoring models completely miss because they look at transactions one at a time.
Here is how you actually set it up if you are evaluating it for your organization.
First, you map your existing data sources. Most teams try to connect everything at once and spend six weeks going nowhere. Start with the two data sources that cause the most false positives in your current system. For us, that was device fingerprinting and merchant category codes. Once those were flowing into the platform, the initial detection rate improved by roughly 34 percent within the first two weeks. After that, you layer in the other feeds gradually.
The configuration interface is not intuitive. The documentation assumes you already understand graph database concepts. If your team comes from a traditional risk background, budget two weeks just for training before you expect anyone to be productive with it. I recommend having one person go through the full certification track first and then run workshops for the rest of the team. That approach cut our onboarding time from four weeks down to about nine days.
Real deployment experience: When we went live, we hit a problem with the real-time graph resolution during high-volume periods. The system was designed to resolve relationships in under 200 milliseconds, but under sustained load above 3,000 transactions per second, response times spiked to over four seconds. This caused a cascade of timeout-related declines that looked like fraud flags to the downstream systems. Our workaround was to implement a circuit breaker pattern. We configured the engine to fall back to a cached graph snapshot every sixty seconds during load spikes instead of attempting live resolution. The tradeoff is you lose some freshness in the relationship data during those peaks, but you avoid the false decline spiral. It is a known limitation documented in their release notes but not really emphasized in marketing materials.
The behavioral modeling component deserves more attention than it gets. The platform learns normal spending patterns at the individual level and flags deviations. But here is the part most people overlook. You have to calibrate the sensitivity per customer segment, not globally. A global threshold creates too many alerts for high-volume merchants and misses subtle fraud in low-volume accounts. We found that splitting our thresholds by merchant category and transaction velocity range reduced alert fatigue by about 60 percent while actually improving capture rates on true fraud.
One counter-intuitive finding from our rollout. Adding more data sources does not always improve detection. We connected five additional third-party data providers in month three and saw our false positive rate jump from 2.1 percent to 8.7 percent. The new sources introduced noise and conflicting signals that confused the ensemble model. We rolled back three of those feeds and tuned the remaining two, bringing false positives down to 1.8 percent. More data is not a substitute for good data hygiene.
The pricing model is usage-based, which sounds fair until you calculate what your average monthly transaction volume actually costs at scale. We were paying roughly $0.003 per transaction for the full graph-based risk engine. At 500,000 transactions per day, that adds up to about $45,000 per month. For smaller fintechs, this can be prohibitive. The good news is there is a lighter tier that offers rule-based scoring with optional graph lookups on demand. It is not as powerful but it can work during the early stages while you build transaction volume.
Integration with existing payment processors takes about two to three weeks if you have clean APIs on both sides. We had to write a custom middleware layer because our payment gateway used an older webhook format that the platform did not support natively. The engineering effort was non-trivial but well within a single sprint for an experienced team.
What the platform does not do well. Real-time regulatory reporting is weak. If you need automated SAR filing or transaction monitoring reports that comply with FinCEN or local regulatory standards, you will need to build that layer yourself or connect a separate compliance tool. The raw data export is solid, so it is not a showstopper, but do not expect turnkey regulatory compliance out of the box.
Another gap is the lack of native multilingual support in the alerting system. Our European expansion required alert templates in German and French. The platform only supports English natively. There is a work-around using their webhook API to pipe alerts into a translation service before delivery, but it adds latency and complexity that would be better handled natively.
The best use case for this system is mid to large-sized fintechs processing over 100,000 transactions per day who are currently struggling with false positive rates above 5 percent or cannot detect organized fraud rings. If you are smaller than that or your primary concern is straightforward AML screening, you are probably better off with a simpler rule-based solution or a dedicated AML provider. This platform shines when the problem is complex relationship-based fraud, not basic compliance checks.
If you want to evaluate it, the vendor offers a sandbox environment that you can access by requesting a trial through their website. The trial includes full access to the graph engine with a simulated data feed, so you can test it against your own historical transaction data before committing. I would recommend loading at least ninety days of your actual transaction history into the sandbox and running it alongside your current system for a side-by-side comparison. The numbers will tell you more than any sales pitch.
Gallery Revolutionizing Risk Management How Aj Soprano Is Redefining The Future Of Fintech Risk Systems
💸 How AI Is Redefining Fraud Detection and Risk Management in FinTech
The Ai Driven Compliance Revolution How Fintech Is Redefining Risk ...
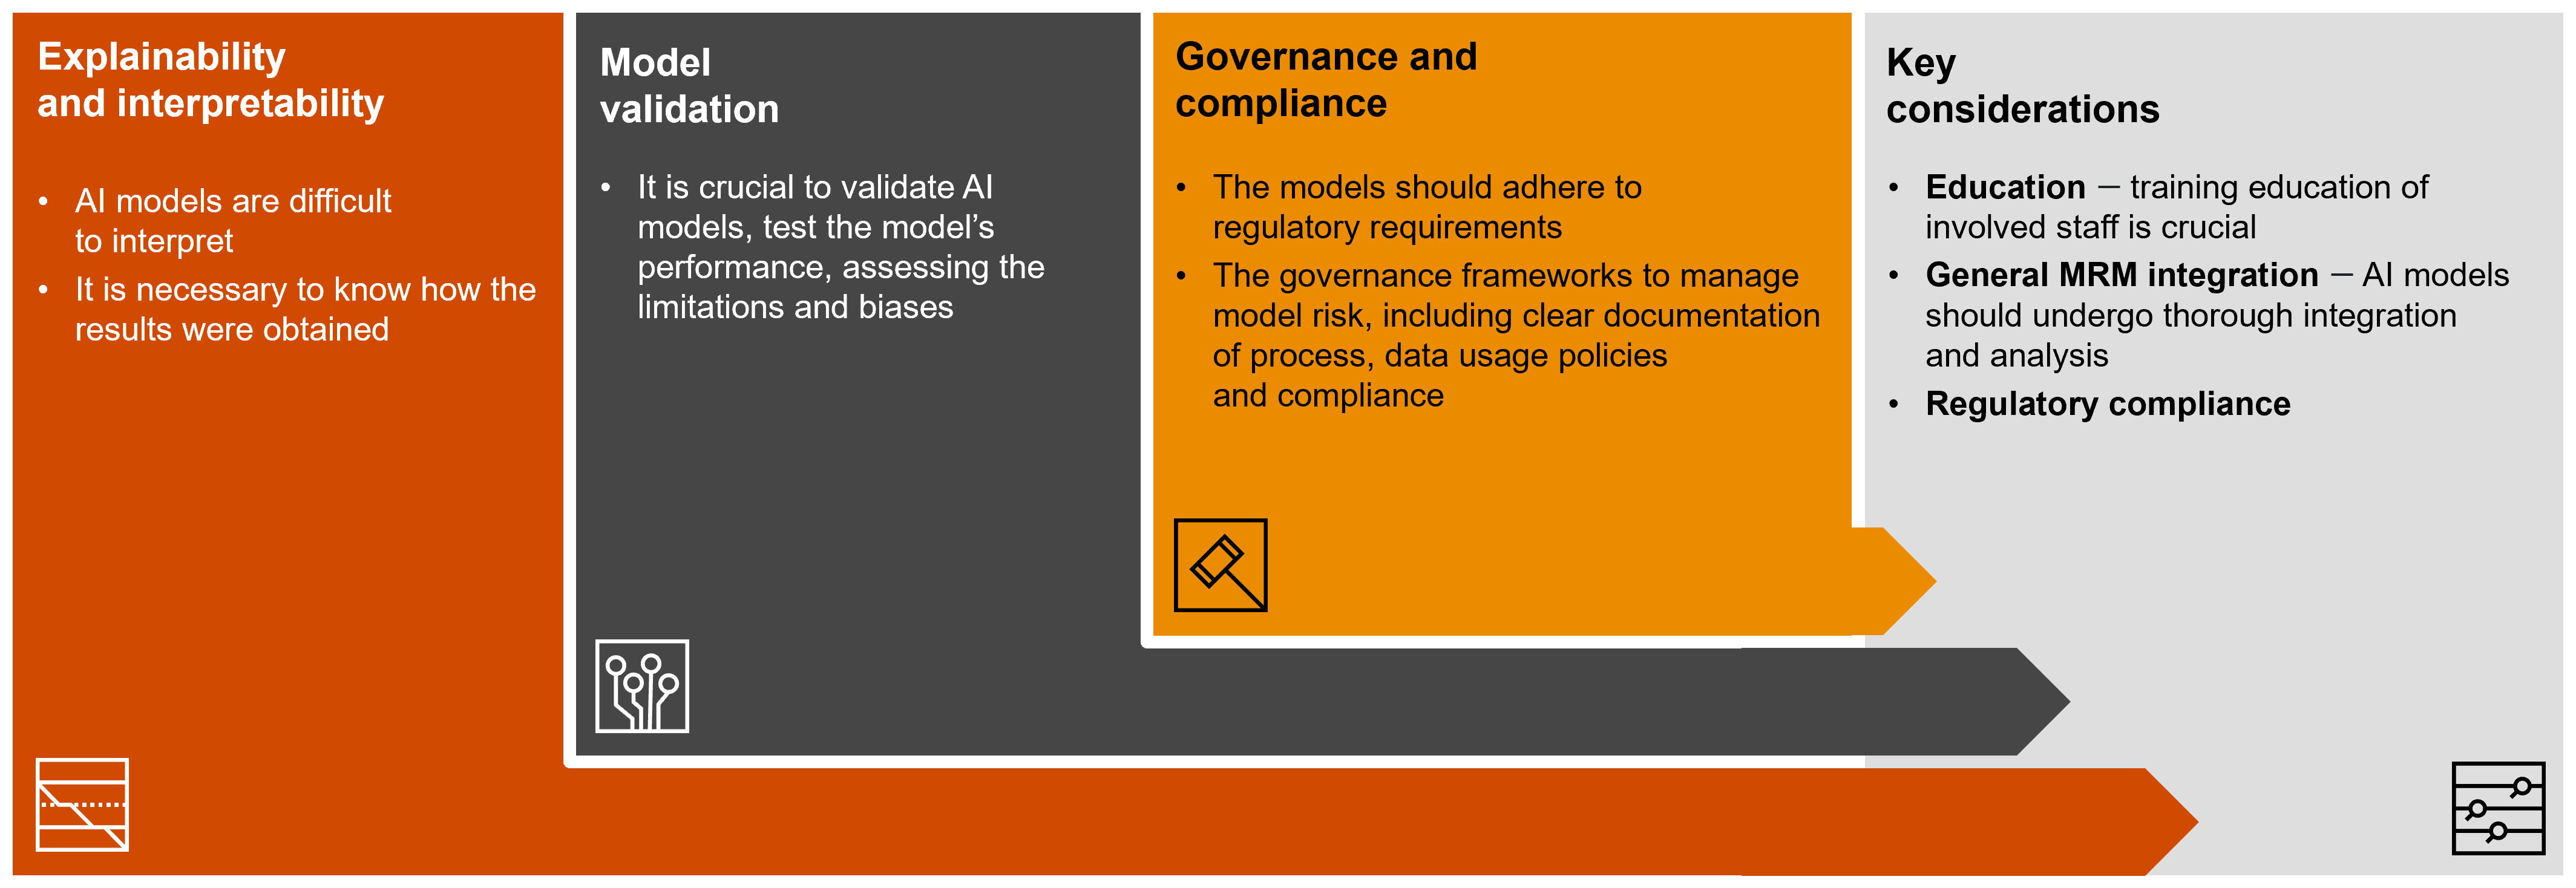
Navigating the future of financial risk management: A business leader’s ...
Why AI-Powered Fintech Solutions Are the Future of Risk & Compliance ...
Revolutionizing Risk Management in Fintech with AI