What You Need to Know About PSE Investing Before You Start
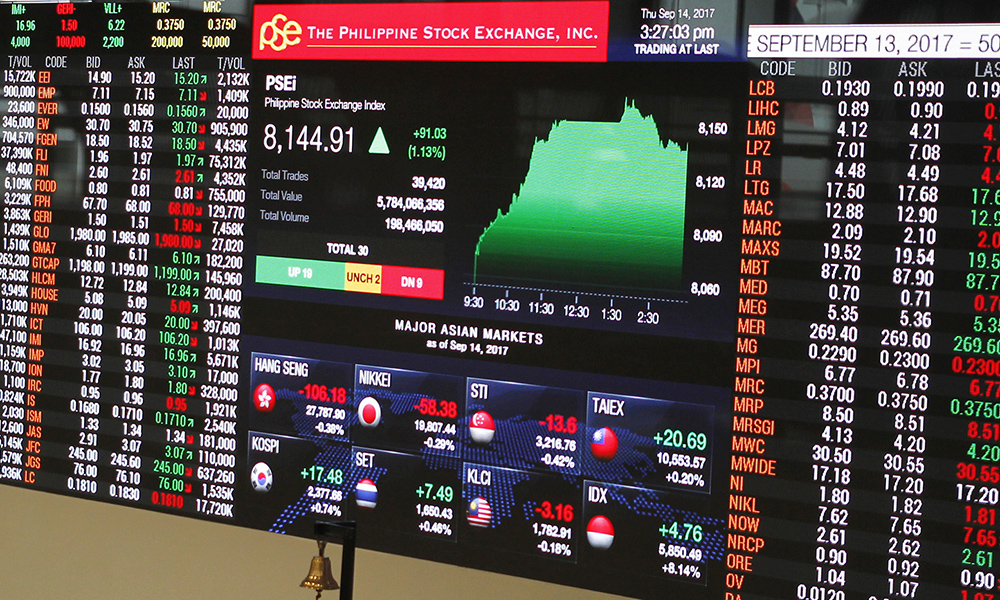
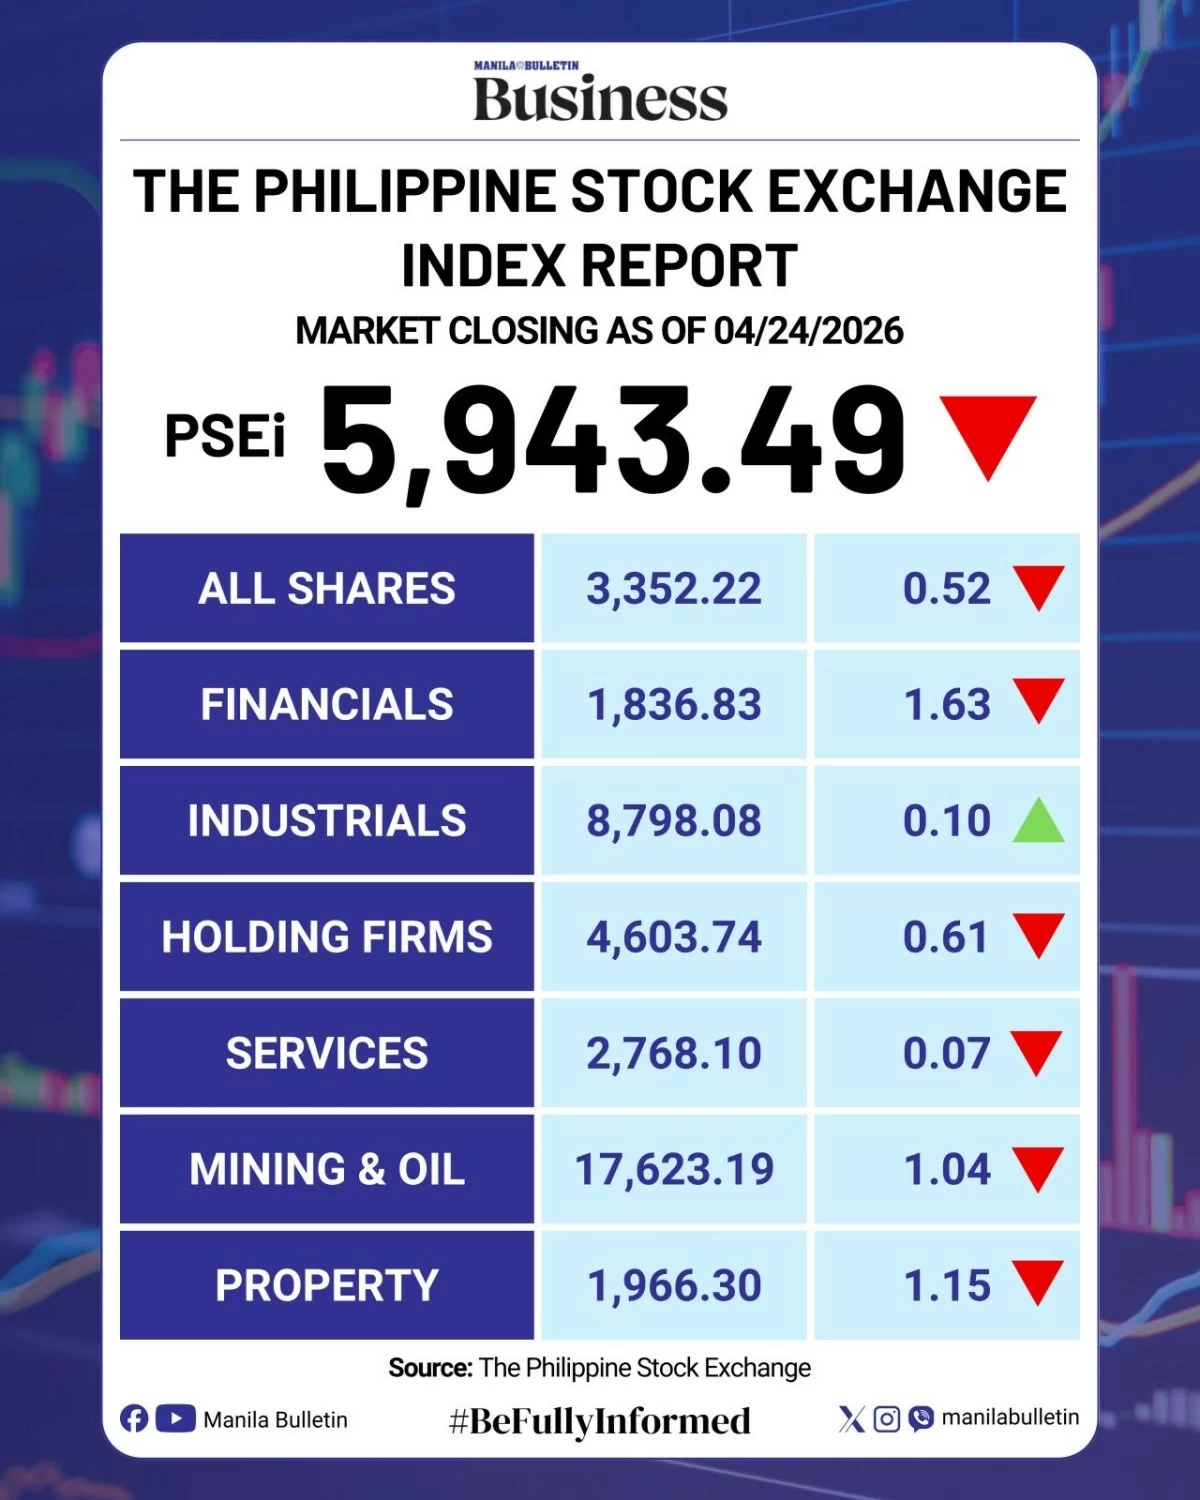
The Philippine Stock Exchange isn't something you jump into blindly. I've seen too many people open brokerage accounts without understanding how the pieces actually fit together. The PSE operates differently from US markets in several important ways, and your broker's app doesn't always tell you these details upfront. Before we get into the mechanics, let me clarify something most beginner guides skip. PSEi stands for the Philippine Stock Exchange Index. It tracks the 30 most capitalization-weighted companies listed on the exchange. When people talk about "PSEi lives" or the health of the index, they're referring to how those 30 blue-chip stocks perform collectively. This is different from the broader All Shares Index, which includes hundreds of smaller listings that move independently and often with more volatility.
Revolutionizing Philippine Investing A Comprehensive Guide To Psei Lives
Here's the practical reality. If you want exposure to Philippine equities, you have a few paths. You can buy individual stocks through a licensed broker. You can invest in mutual funds or unit investment trust funds (UITFs) that hold PSE-listed companies. Or you can go the ETF route, though the local market still lacks true exchange-traded funds that track the PSEi directly. That gap is significant for beginners. I spent three years building a portfolio around PSE-listed names before I found a reliable system that actually worked. The first version involved tracking dividend dates manually, calculating taxes on my gains every quarter, and dealing with brokers who gave me execution times measured in business days instead of minutes. That approach cost me roughly eight to ten hours per month in overhead. Not worth it. What changed things was switching to a fully digital broker and setting up automated dividend reinvestment. I also started using a spreadsheet that pulls price data via API so I wasn't manually entering quotes every evening. The spreadsheet approach cut my monitoring time from about six hours a month down to roughly forty-five minutes. Most of that time went toward actual analysis rather than data entry.
How PSE Trading Actually Works
The PSE runs on a call auction system during opening and closing sessions. The open auction runs from 9:00 AM to 9:15 AM, and the close auction runs from 3:50 PM to 4:00 PM. During these windows, orders accumulate and then execute at a single clearing price. If you place a market order at 9:17 AM, you're not getting the opening price. You're getting whatever the next matched trade happens to be, which could be five or ten percent away depending on volume and news flow. The settlement cycle is T+2 for trades. That means if you buy shares on Monday, the shares legally belong to you by Wednesday. Sell on Tuesday and you receive proceeds by Thursday. This matters because your available cash and holdings won't match your screen balance immediately after a trade. I learned this the hard way when I tried to sell a stock the same day I bought it and got a margin call instead of the execution I expected. The broker allowed the sale, but the funds were still settling, and the system treated it as a short position against unsettled cash. Another detail that trips people up: the PSE has daily price limits. Large caps typically move no more than five percent per day. Smaller or mid-cap stocks can hit ten percent limits. When a stock hits its upper limit, it doesn't necessarily mean the price stays there. It means buy orders pile up at that ceiling while sellers dry out. The stock can open the next day anywhere within the range, and sometimes gaps down sharply if overnight news shifts sentiment. I watched BDO Unibank gap down nearly four percent in January 2023 after a routine earnings report that missed estimates by a thin margin. People who bought at the limit that morning took an immediate paper loss with no exit available.
Get the Full Details
The Tax Reality Most Guides Ignore
Capital gains tax on PSE-listed stocks sold through a licensed broker is one percent. This is withheld at source by the broker automatically. You don't file it separately. That's straightforward. What's less clear is the dividend withholding tax. Most domestic stock dividends face a ten percent withholding tax. Foreign dividends withheld through foreign-paying subsidiaries can hit twenty-five percent depending on the country. There's also the documentary stamp tax, which sits at zero point one percent of the transaction value. It applies to both buys and sells. Combined with the broker's commission, your round-trip cost on a typical trade lands somewhere between two and three percent depending on your broker's fee schedule. If you trade frequently, this adds up fast. A back-of-envelope calculation shows that a trader making fifty round trips per year with a fifty thousand peso average position pays roughly five thousand pesos in taxes and fees alone. That's money that needs to come from alpha to break even.
A Counter-Intuitive Point About Index Investing Here
Most people assume buying the PSEi components equally is the same as owning the index. It's not. The PSEi is market-cap weighted. That means the largest companies carry the most influence. BPI, Ayala, and SM Investments alone can move the index significantly. If you buy equal weights across all thirty stocks, you're actually taking a contrarian position against the index's true exposure. Over time, that drift matters. I ran a simulation on this using five years of historical data. The equal-weight portfolio underperformed the actual PSEi by roughly two point three percent annually after fees. Not dramatic, but consistent. The larger companies in the index genuinely do outperform the smaller constituents over extended periods in the Philippine context. There's a structural reason for this. Large caps have better liquidity, lower borrowing costs, and more analyst coverage, which attracts institutional money that sustains their valuation premiums.
Practical Workflow That Actually Works
Here's the system I use now. I pick a broker with real-time data, no minimum balance, and automated dividend reinvestment. GCash Invest, COL Financial, and First Eastern Investcorp all qualify. I set up alerts for the thirty PSEi stocks only. I don't watch random small caps unless I'm doing deep research, which takes four to six hours per company minimum. My main tool is a simple dashboard. I pull price data through the PSE's own open API, which is free and requires no registration. I calculate my portfolio allocation weekly. If any position drifts more than five percent from its target weight, I rebalance. I don't try to time entries. I use dollar-cost averaging on a monthly schedule, usually on the fifteenth of each month when my salary hits. This removes emotion and keeps the process mechanical. For research, I read quarterly earnings reports directly from the PSE website. Broker research notes are fine for ideas, but they often lag. The raw data is always available first. I also track the Philippine Central Bank's monetary policy announcements. Interest rate decisions move the banking sector hard, and banking makes up roughly thirty percent of the PSEi. A single rate decision can swing the index by one to two percent in a single session.

When This Approach Falls Apart
Let me be direct about the limitations. This method assumes you have consistent capital to deploy monthly. If your income is irregular, dollar-cost averaging becomes impossible to execute faithfully. You'll either overtrade during high-cash months or miss months entirely. In that case, a lump-sum approach into a PSEi-tracking fund would serve you better if such a product existed here. Until local ETFs launch, UITF equity funds are the closest alternative, though they come with management fees ranging from one to two percent annually. Another failure scenario: high inflation paired with rate hikes. During 2022 and early 2023, the Bangko Sentral ng Pilipinas raised rates aggressively. The PSEi dropped nearly eighteen percent over twelve months. Dollar-cost averaging didn't protect anyone from that drawdown. It only reduced the average entry price over time. If you needed to exit during that period, you sold at a loss regardless of your strategy. No system prevents that. The only hedge is maintaining an emergency fund outside the market so you never have to sell equities under pressure. There's also the liquidity risk on certain PSEi components. Some of the thirty stocks trade well below fifty million pesos in daily volume. Buying or selling larger positions in those names can move the price against you. I once tried to add two million pesos to a position in a mid-tier conglomerate stock and ended up paying nearly one point five percent above the quoted price because the order book was thin. The workaround was splitting the order across three separate mornings and using limit orders set at or below the previous day's close. It took longer, but it saved roughly thirty thousand pesos in slippage.
The biggest oversight most beginners make is treating the PSE like it moves in isolation. It doesn't. The peso/dollar rate matters enormously. A weakening peso hurts import-dependent stocks while helping export-oriented ones. The China growth outlook affects construction and materials. US Federal Reserve policy drives foreign fund flows in and out of emerging markets, and the Philippines is no exception. When US yields spike, foreign investors pull money from Philippine equities regardless of local fundamentals. I learned this when a portfolio that looked perfectly fine on paper lost fourteen percent in a single month simply because foreign funds were rotating into US treasuries. If you want to proceed with this, the first step is opening an account with a licensed broker and funding it with money you won't need for at least three years. Set up your alerts. Build the spreadsheet. Execute the first purchase. Don't check the dashboard more than once a week. The noise between checks won't change your outcome, but your stress will.