Paying It Over Time: My Experience With Affirm
I first signed up for Affirm back in 2021 because I needed a new laptop and the one-time hit to my checking account wasn't something I wanted to take. The process was embarrassingly simple, and that should have been my first warning sign. Fast forward three years and a few too many installment plans for things I didn't actually need, and I have some opinions. Here's what the product actually is without the marketing gloss. Affirm offers point-of-sale financing at checkout. You select a payment schedule, they run a soft credit check that doesn't dent your score, and you get your purchase immediately while paying it back over two to thirty-six months. The Affirm Card extended this model to general retail use, essentially giving you a line of credit you can tap at any merchant that accepts their payment network. The math is straightforward. If you buy something for $500 on a 12-month plan with 0% APR, you pay $41.67 per month. If the plan carries an interest rate, say 15%, you'll pay roughly $44.76 per month, totaling about $537 over the year. The fees are disclosed upfront, which is more than I can say for every credit product out there. That transparency is genuinely useful, but it doesn't change the underlying behavior problem.
I learned this the hard way. Last year I used Affirm for a $2,400 furniture purchase on a 24-month plan at 0% APR. Everything seemed fine until I missed a single payment because of a banking glitch on my end. What happened next wasn't dramatic, but it was annoying. They reported the delinquency to the credit bureaus after just 30 days. No grace period explanation in the terms that I could find. My credit score dropped about 45 points within a month. I fixed it by paying the full overdue amount plus the remaining balance on the next statement, but the damage to my credit history stuck around for seven years.
How It Actually Works
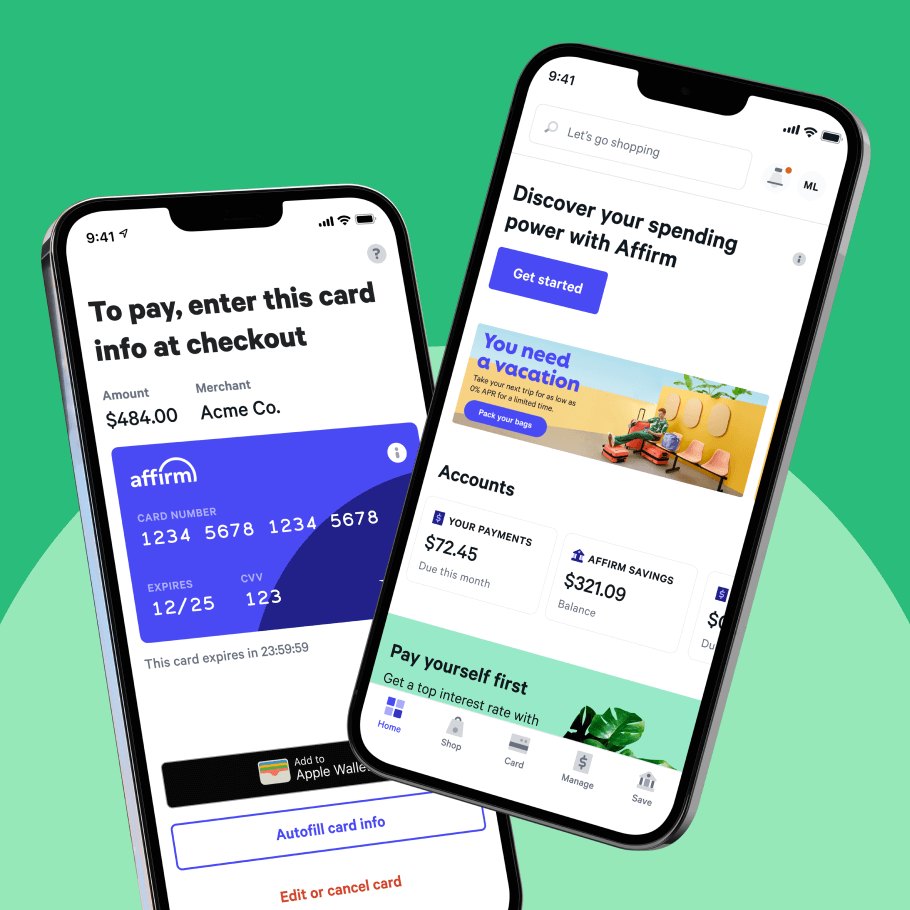
When you apply, Affirm runs a soft pull that shows up on your credit report but doesn't affect your score. The approval decision is automated and usually instant. They look at your income, existing debt obligations, and payment history with them specifically. Unlike a traditional credit card, each purchase gets its own separate loan agreement. This means each installment plan appears as a separate account on your credit report. The app lets you track all your active loans in one place, which is convenient. You can refinance multiple payments into a single plan, though the rates on refinanced loans tend to be slightly higher than your original terms. Payment options include automatic deduction from your bank account or manual payment through the app. One thing most people don't realize: the merchant pays Affirm a fee, typically between 5% and 9% of the purchase price. This cost gets baked into the pricing structure. Products sold through Affirm sometimes carry slightly higher prices compared to paying cash, though the difference is usually small. The 0% APR promos are genuine, but they only apply to specific purchase amounts and timeframes. A $50 purchase on a 3-month plan at 0% is different from a $5,000 purchase on a 36-month plan that might carry 20%+ APR.
Get the Full Details
Common Pitfalls
The biggest issue isn't the math, it's the psychology. Splitting a $300 purchase into 12 monthly payments of $25 makes the expense feel manageable, even though you're paying the same total. This friction reduction is intentional, and it works exactly as designed. People spend more when the pain of payment is distributed across time. I've seen friends accumulate thousands in Affirm loans for things they'd never buy outright. Another trap: the pre-qualification tool. You can check your eligibility without affecting your credit score, which is legitimate. But the displayed payment schedules sometimes show 0% APR options that aren't available for your specific purchase amount or merchant. The final terms at checkout can differ from what you saw during pre-qualification. Always verify the actual APR and total cost before confirming the purchase. Here's something counter-intuitive: using Affirm responsibly can actually help your credit score over time, but only if you pay on time consistently. Each on-time payment gets reported to the credit bureaus as a positive installment loan. But one missed payment can hurt more than a missed credit card payment because installment loans carry different weighting in some scoring models. I switched to automatic payments specifically to avoid this risk, and it's saved me from accidental late payments at least twice.
When It Makes Sense
The 0% APR plans are genuinely useful for purchases you need within a specific timeframe. If you're buying a refrigerator that costs $1,200 and you can pay it off in 6 months without interest, the monthly payment of $200 is manageable. This is better than using a credit card with 20% APR and carrying a balance. The key constraint is discipline: you must pay off the full amount before the promo period ends. For larger purchases, the math changes significantly. A $5,000 plan over 36 months at 20% APR costs about $1,215 in interest, totaling $6,215. This is expensive financing, even though the monthly payment of $172.64 feels reasonable. Compare this to a personal loan from a credit union at 8% APR, where you'd pay roughly $415 in interest over the same period. The convenience of point-of-sale financing comes with a genuine cost premium. I recommend using Affirm primarily for short-term, 0% APR plans on essential purchases. Avoid the longer-term, higher-interest options unless you've compared the total cost against alternative financing. Keep your total Affirm obligations below 10% of your monthly income, and maintain at least one traditional credit card with a low balance for emergency use. This balance between convenience and cost control has worked for me over the past three years.
Alternatives Worth Considering
If you qualify for a traditional credit card with a 0% intro APR period, that often beats Affirm on larger purchases. Cards like the Citi Double Cash or Chase Freedom Unlimited offer 15-18 month intro periods with no annual fee. The application process takes longer, and the credit check is a hard pull, but the cost savings over a 36-month Affirm plan can be substantial. Personal loans from credit unions or online lenders like SoFi or LightStream offer lower rates for qualified borrowers, though the minimum loan amounts (usually $1,000+) might not suit smaller purchases. The approval process takes 1-3 business days, and you receive the funds as a lump sum rather than point-of-sale financing. This delay is the main tradeoff against Affirm's instant approval. Payday alternative loans from community credit unions offer 0% to 10% APR for members, with membership fees around $20-$25. The qualification requirements are looser than traditional banks, and the credit-building benefits are similar to Affirm's reported payments. This option works best if you can commit to automatic payments and have a stable income source.
I've found that combining multiple strategies works best: use Affirm for small, 0% APR purchases under $500, rely on credit cards with intro APR for medium purchases, and take personal loans for large essentials. This approach minimizes interest costs while maintaining the convenience of point-of-sale financing when needed.