Understanding Mortgage Calculators: A Practical Guide for Homebuyers
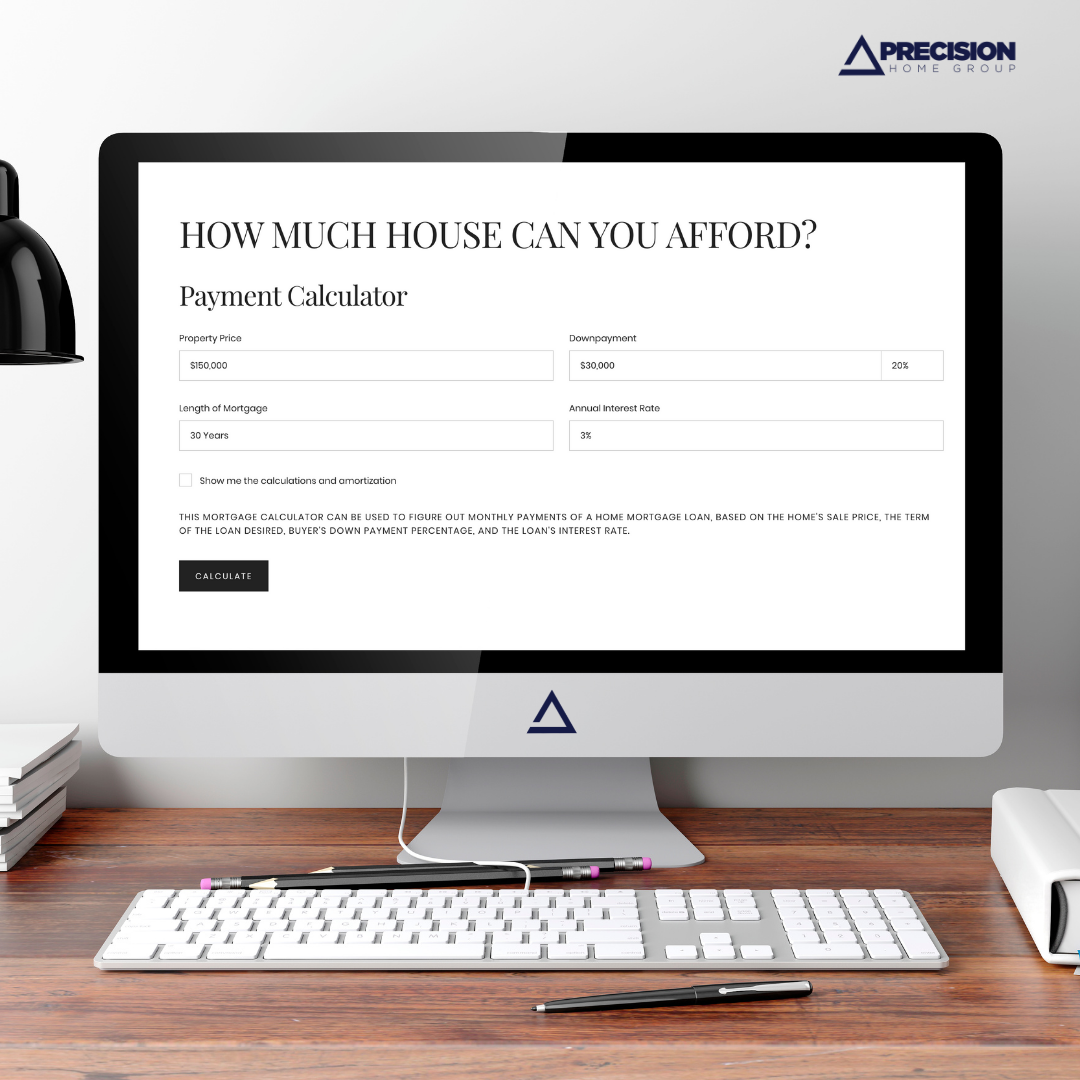
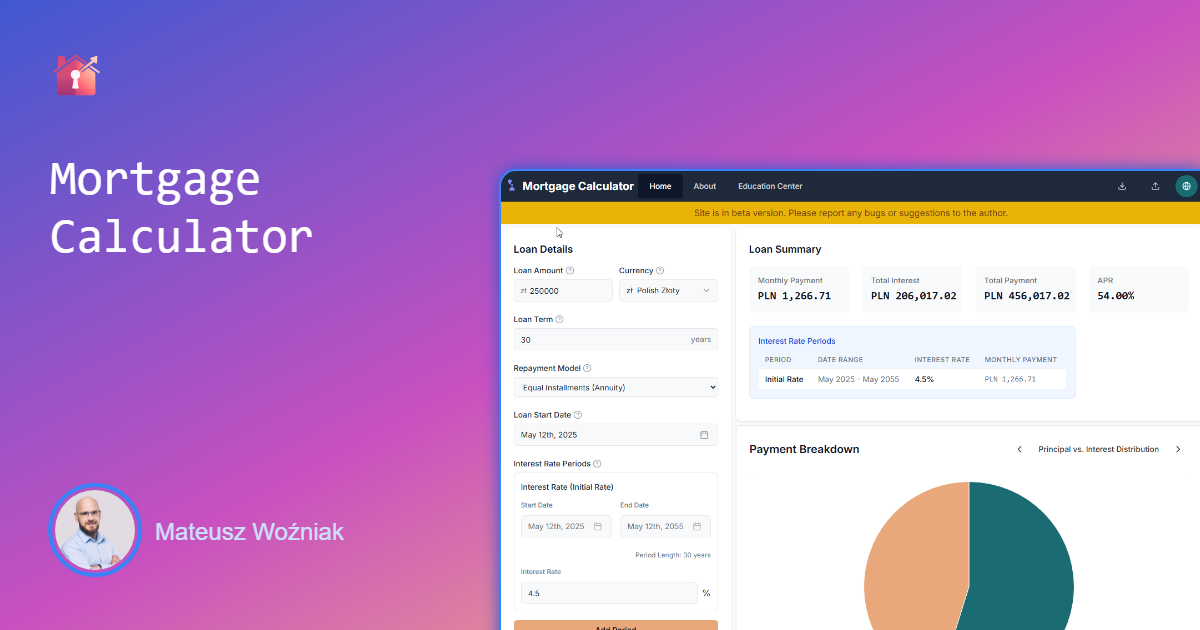
Most people don't think about monthly payments until they actually sit down with a loan officer. I remember standing in a cramped office in 2019, watching a spreadsheet flash numbers I couldn't reconcile. The property tax estimate was off by three hundred dollars a month. That gap between what the calculator showed and what the real closing disclosure would later reveal is where most first-time buyers get caught. A mortgage calculator takes your principal, interest rate, and loan term, then applies an amortization formula to spit out a monthly payment. The basic math is straightforward—most tools use the standard formula where monthly payment equals principal times the monthly rate divided by one minus one over one plus monthly rate all raised to the negative number of payments. What most people skip over is the escrow component. Property taxes, homeowners insurance, and sometimes private mortgage insurance all fold into that single monthly figure. The real precision comes from understanding which inputs actually move the needle. A twenty-year-old buyer once told me they had been adjusting the interest rate slider by points, trying to find the perfect number. I explained that a half-point difference on a three hundred thousand dollar loan over thirty years changes the payment by roughly one hundred eighty dollars, but it barely affects the total interest paid enough to justify the upfront cost unless they planned to stay in the house for at least seven years.
Revolutionizing Homebuying With The Drift Boss Mortgage Calculator Precision At Your Fingertips
Modern mortgage calculators have evolved past simple payment estimates. The best tools now incorporate real-time data feeds for local tax rates, insurance premiums by zip code, and even adjustment frequency for ARMs. When I use these calculators, I start with the worst-case scenario first, then dial down to realistic assumptions. This approach usually catches edge cases that casual users miss. One specific problem I encountered last year involved a borrower with a jumbo loan in a high-tax county. The calculator showed a comfortable payment, but when I pulled the actual millage rate from the county assessor's website, the property tax component jumped by four hundred dollars monthly. The workaround was straightforward—I added a fifteen percent buffer to the tax estimate and ran the numbers again. The payment stretched beyond what they thought they could afford, and we adjusted the loan amount before any paperwork was signed.
Common Pitfalls in Mortgage Calculation
Beginners often focus exclusively on the base payment while ignoring how loan structure affects long-term costs. An interest-only period might show a payment thirty percent lower than a traditional amortizing loan, but that relief comes with a massive principal balance that never shrinks during those initial years. I've seen buyers lock into this structure thinking they were getting a deal, only to face payment shock when the amortization kicked in. Another counter-intuitive insight involves rate locks versus float-down options. A locked rate protects you from market movement, but in a declining rate environment, that lock becomes a liability. The workaround I recommend is negotiating a float-down clause during application, which typically costs one-eighth of a point but gives you the option to capture lower rates if the market shifts before closing.
Get the Full Details

When Calculators Fail You
No calculator can account for every variable in a mortgage transaction. HOA special assessments, flood zone reclassifications, and municipal fee increases all slip through the cracks. The precision these tools offer is impressive, but it has hard boundaries. I learned this the hard way working with a client who purchased in a newly mapped flood zone—their calculator showed zero water damage coverage, but their actual policy required five hundred dollars in annual premiums they never budgeted for. If you're dealing with non-traditional loans like FHA streamlines, VA funding fees, or renovation mortgages, standard calculators often fall short. These programs have unique cost structures that require manual adjustment. I usually switch to running separate worksheets for each program type, adding line items that generic tools omit entirely.
Building Your Own Margin of Safety
The most reliable approach combines calculator output with independent verification. Cross-reference property tax estimates using county records, call your insurance agent for current rate quotes, and add a contingency buffer of ten to fifteen percent to any monthly figure the calculator produces. This process typically adds twenty minutes to your research time but prevents the kind of surprises that derail deals during underwriting. I track three specific metrics when evaluating any mortgage scenario: the debt-to-income ratio after payment, the cash-to-close requirement including reserves, and the break-even point if considering rate buydowns. Most buyers focus on only the first metric and ignore the others until closing day, when they discover their actual resources fall short of what the calculator projected. The tools available today make mortgage analysis significantly faster than they were a decade ago. A comprehensive calculation that used to require three hours of spreadsheet work now takes about fifteen minutes, depending on how thorough you need to be with verification. But speed means nothing without accuracy, and accuracy requires understanding what the numbers actually represent in your specific situation.