
What Oanda Exchange Conversion Actually Is
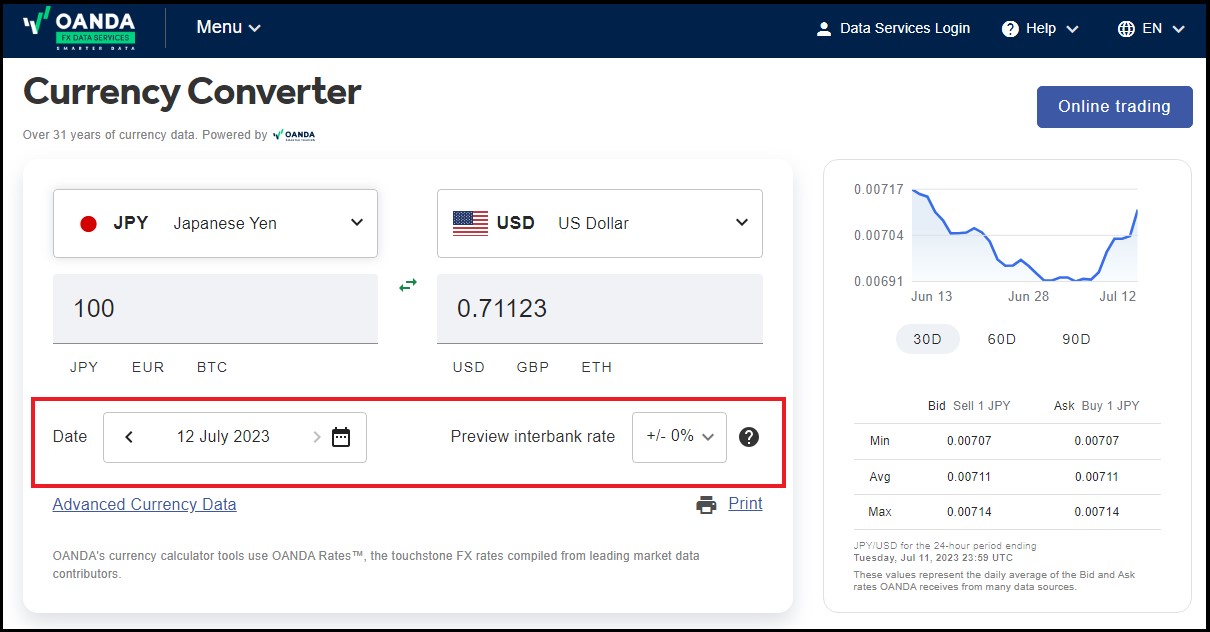
Oanda is a retail forex and CFD broker based in Canada with licensing across multiple jurisdictions. When you open a position in a currency pair that doesn't match your account currency, the platform performs an automatic exchange conversion at the moment of trade execution. That's the basic mechanism. It's not particularly revolutionary, but the scale of volume Oanda processes makes the details worth understanding if you're actually trading. The conversion happens at the rate the platform quotes you at the time of entry, which includes a spread and possibly a commission depending on your account type. Standard accounts typically have wider spreads but no per-trade commission, while the Institutional account layer offers tighter pricing with a disclosed commission structure. Your actual conversion cost depends heavily on which tier you're on.
Revolutionizing Global Transactions How Oanda Exchange Conversion Is Redefining The Financial Landscape
The phrasing above reads like marketing copy, but the underlying shift is real enough. What changed over the last few years isn't the concept of currency conversion itself, it's the speed, transparency, and accessibility. Twenty years ago, a retail trader converting USD to JPY to buy a pair like USD/JPY would get a quoted rate from a bank, wait for settlement, and absorb a wide spread. Today, Oanda and similar brokers execute conversions in milliseconds with rates pulled directly from their liquidity providers. The difference in execution quality matters more than most people admit. Let me walk through what actually happens when you place a trade. Say your account is denominated in USD and you want to go long EUR/USD. You enter your position size. Oanda's system calculates the notional value in USD, pulls the current bid-ask rate from their primary liquidity pool, applies the spread for your account type, and executes the trade. The EUR you receive and the USD you pay are converted simultaneously at that single executed rate. There's no separate FX transaction happening behind the scenes, the trade execution itself is the conversion. If you're trading a cross pair like GBP/JPY with a USD account, it gets slightly more complex. The platform needs to route through a USD intermediary because GBP/JPY doesn't directly involve dollars on the quote side. The conversion effectively becomes GBP/USD plus USD/JPY bundled into a single execution. Oanda handles this transparently, but the implied cross rate can occasionally deviate from the pure mathematical product of the two individual pairs, especially during volatile periods when liquidity thins out on one leg.
I ran into this exact issue during the Swiss franc unpegging event in early 2015. I had pending orders sitting in GBP/JPY and the cross rate blew out compared to where it should have been based on the individual legs. The execution was technically correct from Oanda's side, but the slippage was wider than normal because the liquidity providers were simultaneously restructuring their books. My workaround was straightforward: I stopped using limit orders on crosses during high-impact news events and switched to market orders with a tight slippage tolerance, or better yet, I simply stayed out of the market entirely until volatility settled. That single event taught me more about cross-rate conversion mechanics than any tutorial ever did.
Get the Full Details

Account Types and Their Conversion Costs
This is where most traders get confused, so let me be direct. Oanda offers at least three account tiers in most regions, and the FX conversion cost structure differs between them in ways that aren't obvious from the marketing material. Standard account — No commission. Spreads start around 1.0 pip on EUR/USD but can widen significantly on exotic pairs. Your effective conversion cost is baked entirely into the spread. For a retail trader moving $10,000 per trade, this usually means roughly $1 to $3 in implicit FX cost per round trip on major pairs. Standard Plus account — Same no-commission model but with tighter base spreads, typically starting around 0.6 pips on EUR/USD. The spread widening on crosses is still noticeable but less punishing than the base Standard tier.
Institutional account — Commission-based pricing. Spreads can drop to 0.0 pips on EUR/USD but you pay a commission per side, usually around $3.50 per $100,000 notional. At higher volumes, this becomes materially cheaper than paying the spread. If you're turning over $500,000+ per day in FX trades, the Institutional tier typically saves you enough in spread costs to more than offset the commission charges.
The Hidden Frictions Nobody Talks About
Exchange conversion at a broker level sounds simple, but there are friction points that trip up even experienced traders. Swap rollover calculations. If you hold a position overnight, you're not just carrying the trade, you're earning or paying interest on the two currencies involved. The swap rate is calculated using the overnight forward points published by the respective central banks, not the spot rate. This means your effective conversion cost over time diverges from the entry rate. A long position in AUD/JPY during a period of positive interest rate differentials could generate a small credit, while the reverse carry trade in JPY/AUD during tightening cycles generates a meaningful drag. I've seen traders ignore swap costs entirely and then wonder why their backtest didn't match live results. The difference is usually 10 to 30 pips per month in swap alone on directional positions. Currency denomination mismatches on partial closures. When you close only part of a position, the conversion back to your account currency uses the current market rate, not your average entry rate. This is standard across the industry, but it creates a psychological accounting problem. If you bought at 145.50 and close half at 147.20, the realized conversion gain feels like a win, but the remaining half is now exposed at a less favorable level. Traders sometimes overtrade to "lock in" gains, which generates additional conversion costs that eat into the profit.
islamic swap-free accounts. Oanda offers swap-free accounts for qualifying traders, which eliminates overnight interest but typically replaces it with a wider spread or a fixed administrative fee. The conversion mechanics are identical, but the cost structure shifts. If you hold positions for weeks or months, the swap-free option can be cheaper despite the wider spreads, depending on the interest rate environment of the two currencies involved. The math changes every time central banks move, so this isn't a static decision.
Execution Quality and Liquidity Access
Oanda aggregates pricing from multiple liquidity providers including major banks and electronic communication networks. The platform quotes a consolidated rate, but the actual fill can differ from the displayed price, especially on larger orders or during market hours when certain liquidity pools dry up. Asian session hours on pairs like AUD/NZD or USD/TRY see notably wider spreads and less aggressive fills compared to the London-New York overlap. I keep a simple spreadsheet tracking my execution quality by session and pair. Over a six-month period, the average slippage on EUR/USD during London hours was 0.1 to 0.3 pips against me on market orders, while the same pair during the Asian session averaged 0.4 to 0.8 pips. On exotics like USD/ZAR, the difference was even starker, with Asian session slippage sometimes exceeding 2 pips. This isn't unique to Oanda, every broker experiences this, but quantifying it matters when you're building a strategy around tight stop levels.
When Oanda's Conversion Model Falls Short
Let me be honest about the limitations. Oanda is a solid choice for retail and intermediate traders, but it's not the right tool for everyone. Large institutional flows. If you're moving $1 million+ per trade consistently, Oanda's liquidity aggregation won't match what you'd get from a prime brokerage relationship or a dedicated institutional desk. The execution quality degrades noticeably above certain size thresholds, and the commission structure on the Institutional account still trails what dedicated FX dealers offer for high-frequency or high-volume participants. Exotic and emerging market pairs. While Oanda lists a reasonable number of crosses, pairs involving currencies like the Turkish lira, Nigerian naira, or Vietnamese dong often have spreads that make frequent trading uneconomical. The conversion cost alone can exceed 50 pips on some of these pairs, which eliminates most short-term strategies. I'd recommend using a specialized emerging market broker or routing through a bank for these, not Oanda.
Algorithmic trading at scale. Oanda supports API access through REST and FIX protocols, but the platform isn't designed for ultra-low-latency algorithmic strategies. If your edge depends on sub-millisecond execution, you'll want infrastructure closer to the exchange or liquidity provider. For discretionary or moderately automated strategies with second-level timing, Oanda's API is perfectly adequate.
Practical Steps to Optimize Your Conversions
Here's what actually moves the needle for most traders, no fluff. Pick the right account tier for your volume. If your average daily turnover is under $200,000, the Standard account's spread cost is usually competitive with the commission model. Above that threshold, run the numbers yourself using your actual fill rates and typical pair mix. The break-even point varies, but it's often between $200,000 and $500,000 in daily notional. Trade major pairs during active sessions. EUR/USD, GBP/USD, USD/JPY, and AUD/USD all see their tightest spreads and best fills between 8 AM and 5 PM Eastern Time, Monday through Thursday. Avoid trading these pairs during the first and last hour of the session when order flow is thin and spreads inflate.
Monitor your swap costs if you hold positions overnight. Calculate the annualized carry as a percentage of your position size. If the swap drag exceeds 2 to 3 percent annually on a particular pair, consider whether a shorter holding period or a different pair makes more sense for your strategy. Use Oanda's rate notification tools strategically. The platform allows you to set alerts for specific exchange rates, which can help you avoid emotional entry decisions. I use this feature primarily for cross pairs that I'm monitoring for mean-reversion opportunities, not for my core directional trades. The alerts prevent me from chasing prices during low-liquidity periods when conversions are most expensive. Keep a conversion cost log. Track every trade's entry rate, the executed rate, the spread paid, and the swap charged. After 50 to 100 trades, you'll see patterns in your execution quality that you can't detect by looking at individual trades. This is the single most practical thing a trader can do to understand their true cost of doing business with any broker, including Oanda.


