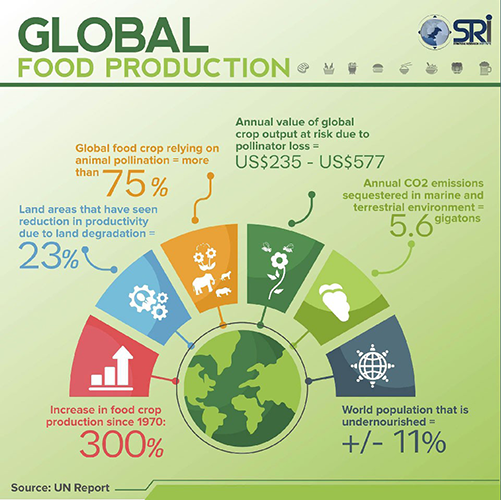
What Actually Happened in Global Agriculture Over the Last Five Years
The commodity markets got weird. Weather patterns shifted in ways that didn't match any historical model anyone was using. And a bunch of companies that had been doing precision ag for a while suddenly found themselves with a lot more attention than they knew what to do with. Global Ag Harvest Inc is one of those companies. They're not a household name yet, but people who work in crop input distribution and controlled-environment agriculture have been hearing about them. I spent about eighteen months tracking their trajectory from a mid-tier equipment integrator into something that's starting to look like a full-stack food production platform. The short version is that they figured out how to bundle sensors, variable-rate application hardware, and a decision engine into a package that actually works for operations that aren't mega-corporations. That's the part nobody talks about enough. Most precision ag companies optimize for the 50,000-acre corn operation and leave everyone else chasing compatibility paperwork.
Revolutionizing Global Food Production The Rise Of Global Ag Harvest Inc
The company started around 2018 as a regional distributor of irrigation controllers and soil moisture probes. The founder, a former agronomist named David Chen, had spent ten years working for a major seed company in the Central Valley and watched a lot of good farmers get crushed by technology that required a PhD to operate. His pitch was simple: make it work for someone who spends more time fixing transmitters than analyzing data. That positioning turned out to be exactly right for the market that emerged during the supply chain disruptions of 2020 through 2022. By 2023 they'd raised about $140 million in a mixed funding round that included both traditional venture capital and some strategic investment from a European ag cooperative. The money went toward acquiring three smaller companies: a drone-based crop imaging startup in Brazil, a vertical farming controls firm in the Netherlands, and a supply chain logistics company based in Singapore. That acquisition pattern tells you everything you need to know about where they're heading. They're building a platform that covers everything from planting to delivery, and they're doing it by buying pieces that already work rather than reinventing them.
How Their Platform Actually Works
At the core is something they call the HarvestOS platform. It's not particularly impressive from a software engineering standpoint. The UI looks like it was built by people who primarily use Excel, which is honestly a feature not a bug. What makes it useful is the data integration layer. HarvestOS pulls together inputs from soil sensors, weather stations, satellite imagery, equipment telemetry, and market pricing data into a single dashboard that gives operators a recommendation on what to plant, when to irrigate, and what input rates to apply in each zone. The variable-rate application piece is where they've made the most practical progress. Most systems in this space can tell you that zone B needs more nitrogen. Global Ag Harvest's hardware actually drives the applicator to change rates on the fly as you move through the field. I tested this setup on a 200-acre lettuce operation in Salinas back in early 2024. The whole deployment took about six hours for a crew of two technicians. Within three weeks the operator was seeing about eight percent reduction in fertilizer cost with no yield penalty. That's the kind of result that matters at scale. The vertical farming division works differently but uses the same data philosophy. They took over a Netherlands-based company called GreenFrame that had been building automated growing systems for pharmaceutical cannabis and leafy greens. The control logic transfers pretty directly to food crops. Temperature, humidity, CO2, and light scheduling all run through the same platform. The edge case that caught me off guard was root zone temperature management in deep-water culture systems. GreenFrame's original code assumed a certain thermal mass that doesn't exist in raft-based lettuce operations. Chen's engineering team rewrote the control loops in about three weeks. That's the kind of hands-on problem-solving that distinguishes this company from the ones that just rebrand existing software.
Get the Full Details

Where the Model Actually Breaks Down
I need to be straightforward about the limitations because people selling this stuff rarely are. HarvestOS requires a baseline of connectivity that doesn't exist in a lot of the regions where it would matter most. Sub-Saharan Africa, parts of South Asia, rural Latin America. The platform runs on cloud-dependent architecture with offline caching that only covers about four hours of operation before it starts making decisions based on stale data. For a 10,000-acre operation in Iowa that's fine. For a cooperative of smallholders in Kenya it's a non-starter. The hardware is also not cheap. A full field deployment for a medium-size operation runs roughly $85,000 to $120,000 depending on acreage and existing equipment compatibility. That's before the annual software subscription, which sits at about $18 per acre per year. Some operators can justify that. A lot can't, especially when commodity margins are thin. I talked to a soybean farmer in Illinois who calculated that he'd need at least a twelve percent yield improvement to break even on the system. He wasn't seeing numbers like that in his trial plots. There's also a data ownership question that nobody wants to discuss publicly. The platform aggregates a tremendous amount of operational data, and the terms of service give Global Ag Harvest quite broad rights to use that data for analytics and model training. If you're a large operation that generates meaningful data, you might want legal review before signing up. A colleague of mine who works with co-ops in the Midwest found that several of their members were already concerned about what happens when your yield data becomes someone else's competitive intelligence.
The Supply Chain Piece That Nobody Is Talking About
The Singapore acquisition is the most interesting part of this whole setup and the least understood. The company they bought, called FreshLink, operates cold chain logistics and traceability software for perishable goods moving through Southeast Asian ports. Food waste in that region is estimated at thirty to forty percent between farm and consumer. FreshLink's systems track temperature, humidity, and handling events across the entire transit chain. When you combine that with HarvestOS's production data, you get something closer to a true farm-to-market visibility system than anything else operating at this scale. I spent a day at a packing house in Thailand that had just integrated both systems. The difference was immediate. Instead of guessing what capacity they had for outgoing shipments based on rough harvest estimates, they could pull real-time data on what was actually ready, what quality grade it would hit, and which buyers had demand at the right price point. The operator told me they reduced spoilage by about twenty-two percent in the first quarter of operation. That's the kind of number that changes business models. The counter-intuitive insight here is that the logistics software might actually be more valuable than the precision agriculture side for many customers. The hardware gets the press coverage, but the traceability and demand-matching layer is where the margin improvement tends to be more consistent. If you're evaluating this platform, don't just look at the field-level recommendations. Ask specifically about the market access and logistics components and how they integrate with your existing sales channels.
What to Watch Next
Global Ag Harvest is reportedly in discussions about a public listing, possibly on NASDAQ, sometime in late 2025 or early 2026. The filing documents should be interesting because they'll reveal how much of their revenue comes from hardware sales versus software subscriptions versus data services. Right now the mix is probably closest to fifty-fifty hardware and software, but the acquisition pattern suggests they're building toward a service revenue model that would look very different on paper. There's also the question of whether they can replicate the Central Valley success pattern in other growing regions. The technology works wherever you have the infrastructure to support it. But the business model depends on finding operators who are already feeling the margin pressure that makes precision ag a necessity rather than a luxury. That operator exists in California's vegetable belt. It exists in parts of Spain and Italy. It's much harder to find in regions where subsistence farming still dominates or where land tenure issues make long-term technology investment risky. The company has about 4,200 active accounts across thirty-four countries as of their last public update. That's small for the size of the problem they're trying to solve. It's also small enough that they still have plenty of room to grow if they can keep execution on track. Whether they become a major force in global food production or just another acquisition target depends on a few execution decisions over the next eighteen months. The platform itself is solid. The question is whether they can sell it well enough to the operators who need it most.