Why I Switched to OANDA for Business Cross-Border Payments
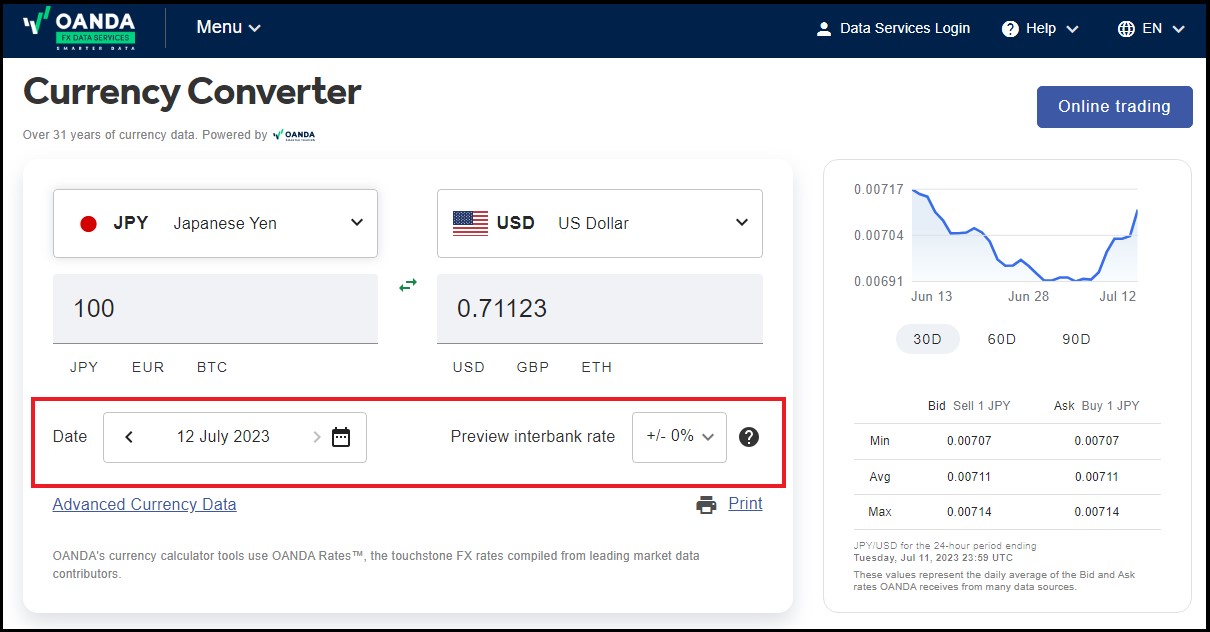
I ran a small export business for about seven years, moving money between Europe, Southeast Asia, and North America on a near-weekly basis. The first thing you learn is that almost nobody tells you the real cost of a cross-border payment until it hits your bank statement. That's why I moved my primary currency conversion to OANDA a few years back. It wasn't a dramatic realization. It was just watching another wire fee eat into a €400 invoice and deciding to stop accepting that kind of loss silently. OANDA is a regulated forex broker that also runs a currency exchange service. What makes it stand out for business users isn't any single feature. It's the combination of tight spreads, a transparent fee structure, and the ability to lock in rates before you need the funds. Most small businesses don't realize they can hold a foreign currency balance in their account and convert it when rates are favorable, rather than panic-converting at the moment an invoice is due. The platform handles major currency pairs and a solid range of exotic pairs too. You can set up scheduled conversions, rate alerts, and limit orders that execute automatically when you hit a target rate. For someone processing payments across three or four currencies every month, those tools turn a daily administrative headache into something you set up once and then check on weekly.
Here is how the process actually works in practice. You open a business account with OANDA, which involves standard KYC documentation — incorporation papers, proof of address, director identification. Once approved, you fund the account via bank transfer. Then you either convert on the spot or set up a pending order. When the invoice arrives in the foreign currency, you execute the conversion and send the payment through OANDA's payout options or withdraw to your own bank account. Most conversions settle within one business day for major currencies. Exotics can take longer depending on the destination country's banking infrastructure. I learned the hard way that not all payouts are created equal. Early on I sent a payment to a supplier in Vietnam using OANDA's standard bank transfer route. The money sat in transit for four business days instead of two because the routing through intermediary banks added friction. The workaround was straightforward — I switched to using a local payment method for that corridor. OANDA supports various payout options depending on the currency and destination, including local bank transfers in some regions. Once I matched the payout method to the corridor instead of defaulting to the generic SWIFT route, delivery times dropped noticeably. There is a specific detail most people miss when comparing OANDA against traditional banks. Banks advertise zero transfer fees but embed their profit in the exchange rate. They might quote you an EUR/USD rate that looks competitive but is actually 1.5 to 3 percent worse than the mid-market rate. OANDA's spreads are typically much tighter. On EUR/USD during normal market hours you might see a spread of one pip or less. That gap between a tight spread and a bank's hidden markup is where the real savings live, and it compounds quickly if you're moving significant volume.
Rate alerts are another underused feature. You can set a notification when a currency pair hits a specific level. I remember last year the British pound was hovering around 1.22 against the dollar for weeks. I had three invoices coming due in GBP, so I set a limit order at 1.24 and converted automatically when the rate hit. If I had just checked the board manually each morning, I would have converted at 1.22 and missed about half a percent on three separate payments. Half a percent sounds small. On a monthly run rate of $50,000, it adds up fast. The main limitation is timing. OANDA, like any FX provider, cannot guarantee a rate. Markets move while you are thinking about whether to convert. I once spent twenty minutes debating whether to execute a JPY conversion and watched the rate shift unfavorably by about 0.4 percent in that window. The practical solution is to use limit orders or set recurring conversions rather than trying to time the market manually. You will not beat the market consistently. You can only remove emotion from the equation. Another bottleneck worth noting is minimum transfer amounts. Some corridors have lower thresholds than others. If you are making frequent small payments rather than occasional large ones, the per-transaction cost structure changes. OANDA is generally competitive on smaller amounts compared to bank wires, but if your average transfer is under $500, you might want to compare against specialized services like Wise or Revolut Business, which can sometimes undercut on the low end.
Get the Full Details

For larger businesses moving six figures monthly, OANDA becomes much more efficient. The account manager access, the ability to negotiate slightly better spreads at volume, and the automation features all tip the scale. A mid-size company I consulted for was converting roughly €200,000 per month across five currencies. After switching from their bank, they reduced their effective conversion cost by about 1.2 percent, which translated to over €2,000 saved per month. That is not a theoretical estimate. It was based on actual trade confirmations over a four-month comparison period. The platform also offers a mobile app that lets you execute conversions on the go, which matters more than you might expect. There was a period when my supplier in Poland changed her banking details and needed payment the same day. I was traveling and could not sit at my desk. The app allowed me to convert PLN and send the payment within an hour. Had I been locked to my desktop, the invoice would have been delayed by a couple of days. If you are just starting out with cross-border payments, the onboarding process is the only part that requires patience. Expect to spend a few days waiting for account approval, especially if your business structure is unconventional. Multiple entities, offshore registrations, or unusual source-of-funds documentation can trigger additional review. One client of mine with a holding company structure in two jurisdictions spent nearly a week waiting for clearance. The workaround was to provide the documentation upfront in a single package rather than responding to requests sequentially. It cut the approval time roughly in half.
OANDA is not ideal for every situation. If you need instant same-day conversions for retail-sized amounts, the settlement time might feel slow. If your transaction volume is very low and you prefer simplicity over optimization, a mainstream bank or a consumer-focused service might feel more convenient. But if you are processing regular international payments and want to keep more of your money, OANDA is a solid choice that rewards people willing to use its features deliberately rather than treating it like a basic remittance app.