Setting Up a Budgeting Workflow That Actually Sticks
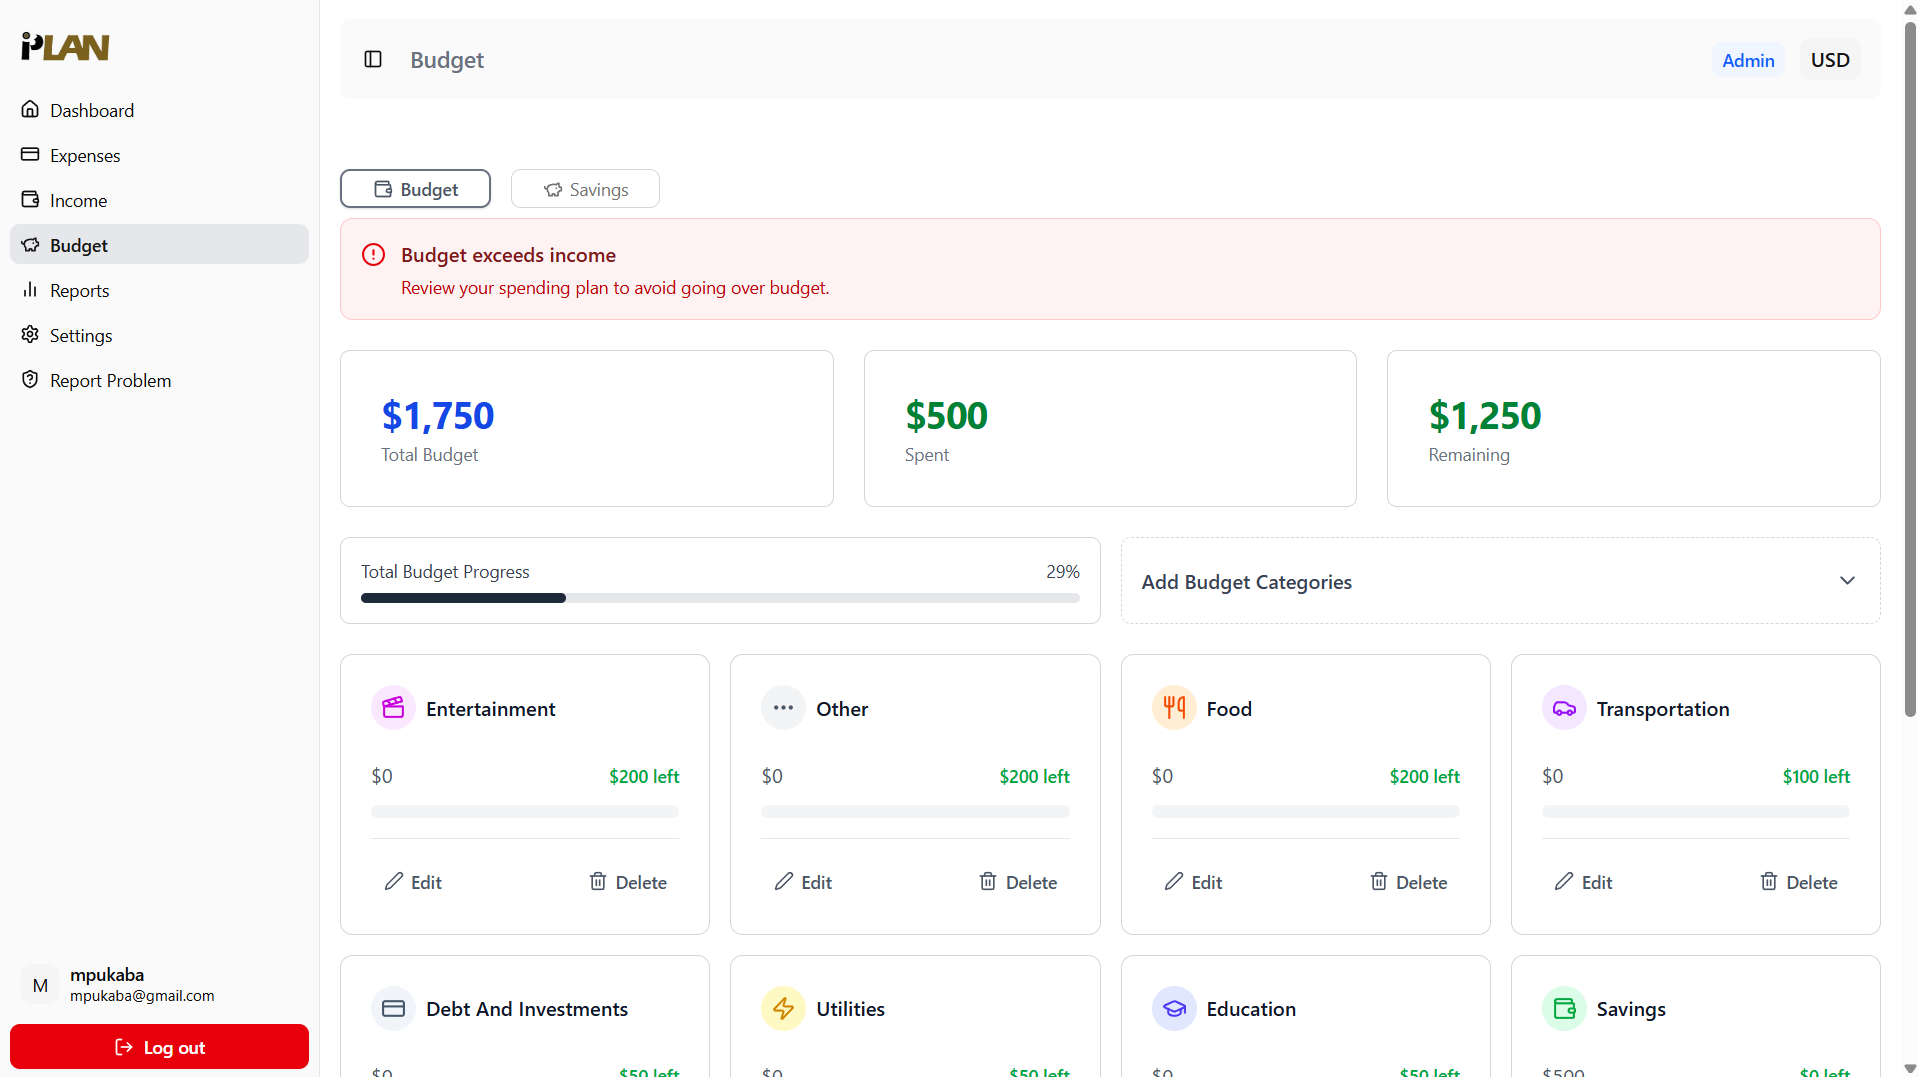
The problem with most personal finance apps is that they ask you to do too much upfront. You spend three hours categorizing transactions from last month, trying to get everything perfect, and then you never open the app again because it feels like homework. My approach is different. Start with the bare minimum and let the system grow organically over time. Myplanpusd works as a middle layer between your bank feeds and your actual spending decisions. The key insight most people miss is that budgeting apps fail when they try to predict the future instead of tracking the past. Here is what actually happened to me when I set this up for the first time. I connected my checking account and two credit cards on a Tuesday evening. The app pulled about fourteen months of transaction history automatically. That part is straightforward. Where things got messy was the recurring subscription category. Myplanpusd classified my Spotify, Adobe, and gym membership all under one "entertainment" bucket initially, which made my monthly discretionary spending look way higher than it actually was. I spent twenty minutes going through each recurring transaction individually and creating sub-categories. You have to do this manually for the first thirty transactions or so before the algorithm gets enough data to sort correctly.
The real utility comes from the cash flow forecasting feature, which estimates your available balance three weeks out based on known bills and average spending patterns. This is where the edge case hit me. I had a $400 quarterly insurance payment that got flagged incorrectly as a monthly expense because it hit my account on the same day each month. The forecast was off by nearly a thousand dollars for two months running. The workaround was simple but not obvious. You need to go into the transaction settings and mark it as a "one-time" recurring with a custom frequency rather than monthly. Took me a week to figure that out after my actual balance dipped lower than predicted. Another thing nobody tells you about this kind of tool. The categories matter less than the cadence. Most people check their budget once a week. That is too late. What actually changes behavior is checking it every two to three days during the first month of use. You are essentially retraining your brain to notice spending before it becomes habit. After about forty-five days, the weekly check-in becomes sufficient because you already know roughly where your money went. The setup process itself takes about twenty-five minutes if you already have your account credentials handy. Importing historical data is automatic. Manual categorization of outliers is where the time goes. I would budget an hour for the initial setup and another thirty minutes the following weekend to clean up anything the auto-categorizer got wrong.
Limitations. The app does not handle joint accounts well. If you share a checking account with a spouse or partner, the transaction splitting feature creates duplicate entries that you have to manually merge. I ended up just setting up a separate tracking account for my half and transferring the data over manually each month. It is tedious but accurate. Also, the free tier caps your linked accounts at two. If you have more than two bank accounts, you are looking at the paid plan, which runs about eight dollars a month. The paid features include goal tracking and investment integration, which are nice but not essential for basic budgeting. If you are dealing with variable income, like freelance work or commission-based pay, this tool struggles. The forecasting model assumes steady monthly deposits. I worked around it by setting up a separate "income buffer" category and manually adjusting it each month based on what I actually earned. Not ideal, but it keeps the numbers from looking wildly inaccurate. The download and setup link is straightforward. Go to the official Myplanpusd website and create an account. The mobile app syncs with the web version in real time, so you can log expenses on the go. I recommend using the mobile app for quick entries and the web dashboard for the weekly review. The mobile interface is faster for adding transactions. The desktop view gives you the full picture with charts and projections.
Get the Full Details

One last thing. Don't obsess over being perfectly accurate in week one. Your budget will be wrong. That is normal. The system learns from your corrections over the first six to eight weeks. By the end of that period, your forecast accuracy should be within five to ten percent of your actual spending, which is good enough for making real financial decisions.