How Amazon Pay A Bill Actually Works When You're Not Reading the Marketing Copy
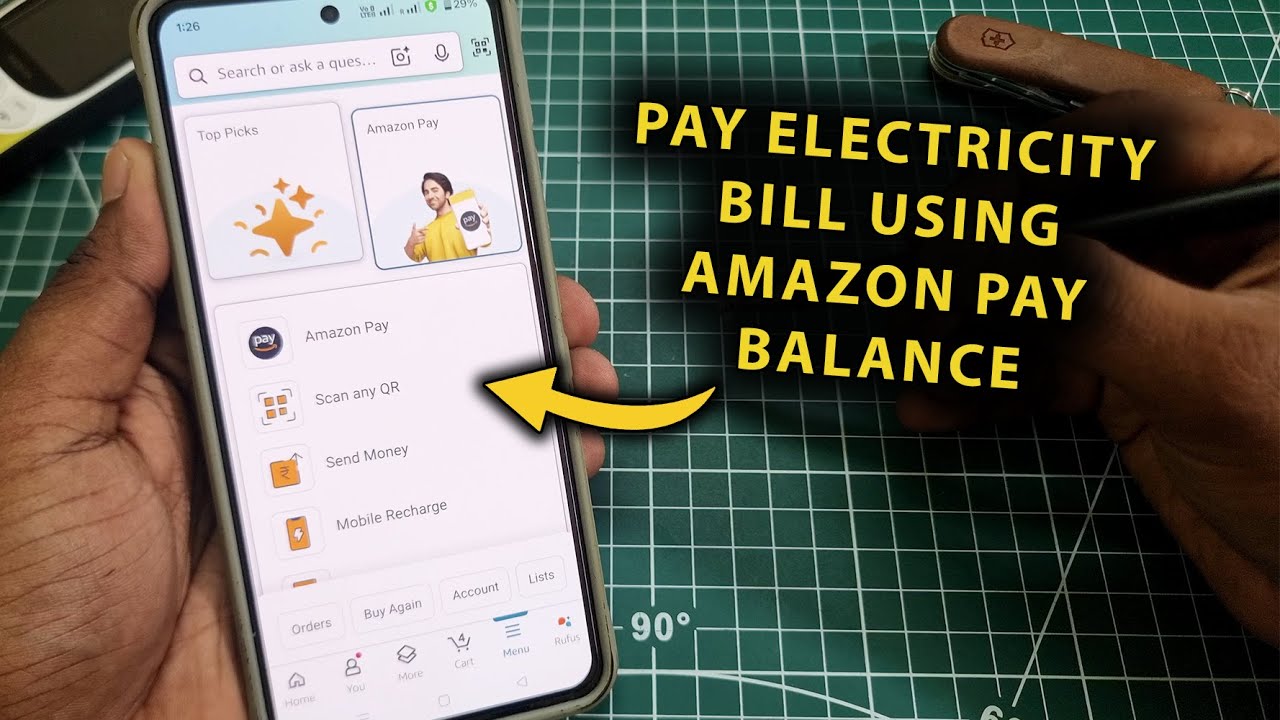
I've been dealing with utility payments, credit card bills, and subscription charges since before most of these platforms existed, so I have a pretty clear sense of what changes and what is just rebranding. Amazon Pay A Bill is not a new payment rail. It is a aggregator interface that routes your bill payments through existing networks, mostly ACH and real-time payments depending on the payee. The convenience is real. The control is real too, mostly because you get a single dashboard instead of thirty separate logins. To actually set this up, you start by navigating to the Pay section in the Amazon app or on the website. You enter the payee name or search for your utility company, mortgage servicer, or credit card issuer. Amazon maintains a database of supported billers, and it is fairly comprehensive but not universal. Some smaller cooperatives and regional institutions are missing. Once you add a payee, you link your funding source. You can use a bank account, debit card, or credit card. The default flow routes ACH from your bank account. If you choose a credit card, you will likely see a convenience fee around two to three percent on most transactions. The real workflow advantage shows up after the initial setup. Most people spend roughly an hour each month bouncing between portal logins, password resets, and payment confirmations. With Amazon Pay A Bill, that drops to maybe ten minutes the first month for setup, then about two minutes per month going forward. That is a legitimate time savings, not marketing hyperbole. You get calendar reminders, payment history exports, and a single receipt trail. The receipts are actually useful. They include confirmation numbers and payment dates that match what shows up on your statement.
Here is where things get specific and slightly annoying. I ran into an issue with a municipal water utility that accepted payments through Amazon but processed them as third-party originations. My local government's system flagged the payment as suspicious because it came from a corporate entity rather than directly from my bank account. The payment held for four business days. I had to call the water department's billing line, give them the Amazon confirmation number, and manually reconcile it on their end. The workaround was straightforward: I switched to scheduling payments three days earlier than necessary, which gave the ACH buffer it needed, and I saved a screenshot of every confirmation email in a dedicated folder. It added about twenty seconds to each payment cycle, but it eliminated the occasional anxiety spike when a bill did not post on time. There is a common misunderstanding about how Amazon Pay A Bill handles posting dates. People assume that scheduling a payment on the 15th means it posts on the 15th. It does not. ACH payments typically take one to three business days to settle. If your due date is the 15th and you schedule for the 15th, you are gambling. I always schedule payments four business days before the due date, unless the platform explicitly shows an estimated posting date that is already confirmed. Amazon sometimes displays that estimate during checkout. If it does, you can trust it. If it does not, fall back to the four-day buffer rule. Another thing most guides skip over: the credit card convenience fee structure is not uniform. Some billers absorb the fee. Most do not. The ones that do tend to be larger national banks and major credit card issuers. Smaller regional utilities, insurance companies, and especially some property management firms will pass the fee directly to you. Before you link a credit card to earn rewards, calculate whether the reward rate exceeds the convenience fee. A two percent fee with a one percent cash back card is a net loss. Do the math out loud. It takes five seconds and saves real money.
Integration with budgeting tools works better than you might expect. You can export payment history as a CSV file, which most spreadsheet software and personal finance apps like Mint alternatives can ingest without parsing issues. The export includes merchant name, date, amount, and confirmation ID. That last field is important for dispute resolution. If a payment does not post, that confirmation ID is your primary evidence. Without it, you are relying on bank records alone, which sometimes lag. Security-wise, Amazon Pay A Bill operates within the same infrastructure as standard Amazon checkout. Tokenization is used for stored payment methods, meaning your actual card or account number is not transmitted to the biller. This is a meaningful improvement over websites that ask you to re-enter card details for every transaction. That practice is still common and it is unnecessary risk. The one security note that matters: enable two-factor authentication on your Amazon account immediately if you have not already. A compromised account with stored billers is a worst-case scenario for identity theft because the attacker has both your payment routing information and your billing address history. There are scenarios where Amazon Pay A Bill simply does not work, and you should know about them before assuming it will. Government tax payments, certain tuition payments, and a handful of specialized lenders do not integrate with the platform. Mortgage servicers are a mixed bag. Some allow Amazon Pay A Bill for standard escrow payments but not for additional principal paydowns. If you are trying to make a biweekly mortgage payment or a one-time extra payment, check whether the platform allows partial amounts. Some billers set a minimum payment threshold that is higher than your intended contribution, and Amazon will reject the transaction silently. I learned this the hard way with a loan servicer that required a minimum of five hundred dollars per payment. My partial principal contribution of two hundred and fifty dollars was declined, and I only noticed when I checked the actual account balance a week later.
Get the Full Details
If you have billers that do not support Amazon Pay A Bill, you can still consolidate your view by linking those accounts through a separate aggregator service or by using manual entry in a spreadsheet. It is not ideal, but it is workable. The main thing is to keep your payment strategy documented somewhere so you are not guessing on due dates or missing a cycle because the portal was confusing. Another nuance worth mentioning is the difference between same-day and next-day processing for ACH. Amazon offers accelerated funding in some cases, particularly when you use a debit card as the source. Debit card payments can post the same business day if you initiate them before the cutoff time, which is typically around 3 p.m. Eastern Time. Bank account ACH payments do not get this acceleration. If you are paying a bill with a tight deadline and you have a debit card available, use it and verify the posting time on the biller's side before the cutoff window closes. If you are unsure whether the biller even accepts same-day postings, call them first. Some do not process same-day transactions regardless of how fast your payment method is. Customer support is another practical consideration. Amazon's support is generally competent, but they are intermediaries. If a payment fails or posts incorrectly, Amazon can reverse the transaction on their side, but they cannot force your biller to accept it retroactively. You still need to contact the biller directly to resolve the underlying issue. I keep a running list of customer service phone numbers for my top ten recurring bills. When something goes wrong with a payment through Amazon, I call the biller first, not Amazon support, because the biller controls whether the account is marked current.
The bottom line is that Amazon Pay A Bill is functional infrastructure, not magic. It consolidates payments, reduces login fatigue, and provides a reliable audit trail. It also has friction points around missing billers, convenience fees, and the ACH delay gap that catches people who do not plan ahead. If you schedule payments with appropriate lead time, avoid credit cards when the fee exceeds the reward, and keep your confirmation receipts organized, it is a solid system. If you treat it like instant payment for everything and do not read the fine print, you will have a bad month. Both outcomes are within your control.