What It Actually Is Before You bother Setting It Up
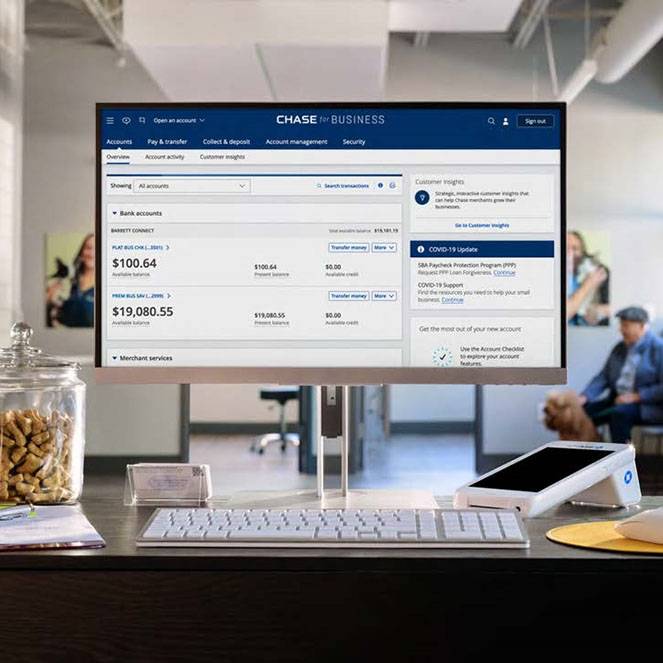
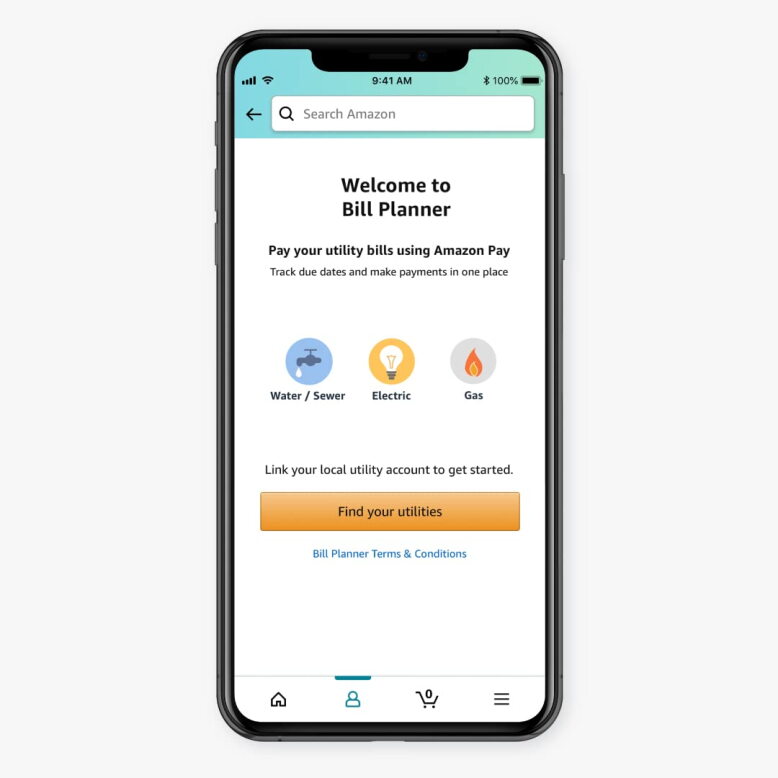
A lot of people treat this like a new product when it's really just Chase paying for Chase's own customer acquisition. You link your Chase checking account, route your bills through it, get a 1% return in the form of an Amazon reward, and then pay your mortgage, phone, electric, and internet bills from Chase instead of calling each vendor. The Revolutionizing Bill Pay How Amazon Chase Bill Pay Is Changing The Game narrative is oversold, but the mechanics are straightforward enough that they actually work if you have the right accounts. You don't download anything from Amazon. The program lives entirely inside the Chase mobile app or online banking portal. Here is the workflow: First, you need an eligible Chase checking account. Most standard Chase checking accounts qualify. Chase Sapphire Checking specifically was built around this, but the benefit rolls out across the product line now. Log into your Chase account and look for the Chase Pay Bills section. It is usually under Transfer & Pay or Pay Bills. If you do not see it, your account may still be in the rollout phase.
Next, you add a biller. Chase lets you search by name, zip code, or amount due. If the vendor appears, you confirm the match. If they do not appear, you can try adding them manually, though manual entries have a higher rejection rate and sometimes get flagged as duplicate payees during bank reconciliation. I once tried to add a municipal water utility that was not in Chase's system. After three failed attempts, I called Chase support, had them add it on their backend, and it appeared the next business day. The workaround is not complicated, but it eats fifteen to thirty minutes of your time. Once the biller is added, you set up a payment schedule. You can go one-time, monthly recurring, or custom. Monthly is the safest route for fixed bills like internet and phone. For variable bills like electric, you can either set a minimum payment and adjust each month or skip scheduling and review the statement before confirming. The reward portion is automatic. You get 1% back when you pay through Chase on qualifying purchases at Amazon, or you get the reward applied directly to the bill payment itself depending on your account tier and the specific promotion running at the time. Check the offer details before you submit a payment so you know whether you are getting a statement credit or a gift card reward.
What This Actually Costs You in Time and Money
On the surface this saves time. You stop logging into ten different vendor portals. You stop dealing with forgotten autopay, which is the main failure mode for people who rely on manual bill pay. One client of mine had twelve separate utility and service accounts and was missing payments two or three times per quarter. After switching to Chase's consolidated pay bills flow, those missed payments dropped to zero over six months. The opportunity cost is smaller than most people think. The 1% reward on a $2,000 monthly bill total comes out to roughly $20 per month, or $240 annually. That is not negligible, but it is not a game-changer either. The real value is friction reduction. There is one hidden friction point nobody mentions. Chase holds bill payments for one business day after you schedule them. If you schedule a payment on Friday evening and the due date is Monday, the payment posts on Tuesday. Some vendors treat that as late. I learned this the hard way with a small HVAC company that reported a missed payment after I scheduled it through Chase on a Thursday. The workaround is simple: schedule bill payments by Wednesday afternoon at the latest, or pay on the due date itself if the vendor processes same-day ACH through Chase. Never rely on the system to catch up on a weekend.
Get the Full Details
Edge Cases That Break the System
Not every bill works here. Government agencies, insurance premiums, and medical providers are the usual offenders. Chase's biller network covers most utilities and telecoms well. Coverage for municipal services is patchy. Coverage for insurance is inconsistent and depends heavily on your state and carrier. Medical bills often appear under a different vendor name than what shows on your statement, which causes duplicate-payment confusion if you are not careful. Another common issue is the name mismatch on credit builder reports. When you pay a bill through Chase, the vendor reports the payment under the legal name on file with Chase, not necessarily the name you use day to day. If your credit file has a variation of your name from a different bureau, you may see a small discrepancy. It does not hurt your score, but it is annoying if you are chasing down an error report. I ran into a problem with a property management company that accepted rent payments only through a specific third-party platform. Chase rejected the payment after I added them as a biller because their routing information was flagged as non-ACH. The fix was to contact Chase and ask them to remove the biller, then pay directly through the landlord's portal. Trying to force the payment through Chase caused the transaction to bounce twice and triggered a $25 fee from Chase for an invalid ACH submission. Don't do that. Call Chase first if a payment fails.
Who Should Use This and Who Should Not
If you have Chase checking and pay more than five bills per month, this is worth setting up. The math works. If you pay fewer than three bills, or if most of your bills are rent or insurance, it may not be worth the hassle. The reward caps out quickly for low-volume payers, and the time savings are minimal. If you are already paying through a budgeting app like Mint, YNAB, or Monarch, keep using that. Chase bill pay is not a replacement for those tools. It is a replacement for logging into individual vendor portals. Using both together creates duplicate entries unless you clean up one system. If you are on the fence about Chase, I would say open a no-fee checking account and test the system for one billing cycle before committing. Add your three largest bills and track whether payments post on time. If they do, expand to the rest. If they do not, cancel the program and move on. The exit process is painless.
Practical Steps If You Decide to Proceed
Add your most important bills first. Schedule them for at least two business days before the due date. Monitor the first two payment cycles to confirm posting dates. Keep a small buffer in your checking account so Chase cannot dishonor a payment due to insufficient funds. A single dishonor fee is $34 to $35 with Chase, and it wipes out months of 1% rewards if you hit it twice in a year. Check the Chase app weekly for new biller additions. Chase adds vendors continuously, and occasionally drops ones that become unreliable. If a vendor disappears, update your payment method before the next due date. Set a calendar reminder for the first Monday of each month to verify that all payments posted correctly. This takes about five minutes and prevents most surprises. Finally, keep receipts. Chase provides downloadable transaction records, but some vendors issue separate statements for electronic payments that differ slightly in formatting. If you are auditing your finances or reconciling a business expense, having both the Chase record and the vendor statement avoids confusion later. I keep a simple spreadsheet with payment date, amount, vendor name, and Chase transaction ID. It takes ten minutes to maintain and saves an hour during tax season.