The Reality of Repo Mobile Homes
Most people think they are getting a deal when they buy a repossessed mobile home. They see the price, do a quick calculation, and pull the trigger. The problem is that repossession sales are one of the least regulated corners of the real estate market, and the scammers know exactly which gaps to exploit. I spent about four years working with mobile home parks across the Southeast before I stopped taking calls from people who had been burned. It was not pretty. The basic setup involves a homeowner who has fallen behind on payments, the lender or park owner seizes the unit, and then attempts to sell it through an auction or private sale. That process itself is legal. The scam happens because there is almost no oversight on how these sales are conducted. Titles get lost. Encumbrances go un disclosed. Units are sold that were never actually repossessed. I have seen the same trailer flip three times in sixty days through different "repo" listings, each time with a new buyer handing over cash they could never get back. One specific case sticks out. A buyer in Alabama came to me after purchasing a double-wide listed as a repo sale for eighteen thousand dollars. The seller had a title, the paperwork looked fine, and the price was twenty percent below market. Everything checked out on the surface. The problem was that the mobile home was sitting in a park where the lot rent was already in default, and the park had a lien on the unit that was senior to whatever the buyer was paying off. I caught it because the buyer had not run a title search through the state DMV and had not pulled the park's rental ledger. The workaround was straightforward but something almost nobody does before wiring money: pull the VIN number off the HUD data plate, run it through the state titling system, and then physically visit the park or call the office to confirm there are no outstanding balances or liens recorded against that specific unit. It took me about twenty minutes once, compared to the two hours most people waste on paperwork after the fact.
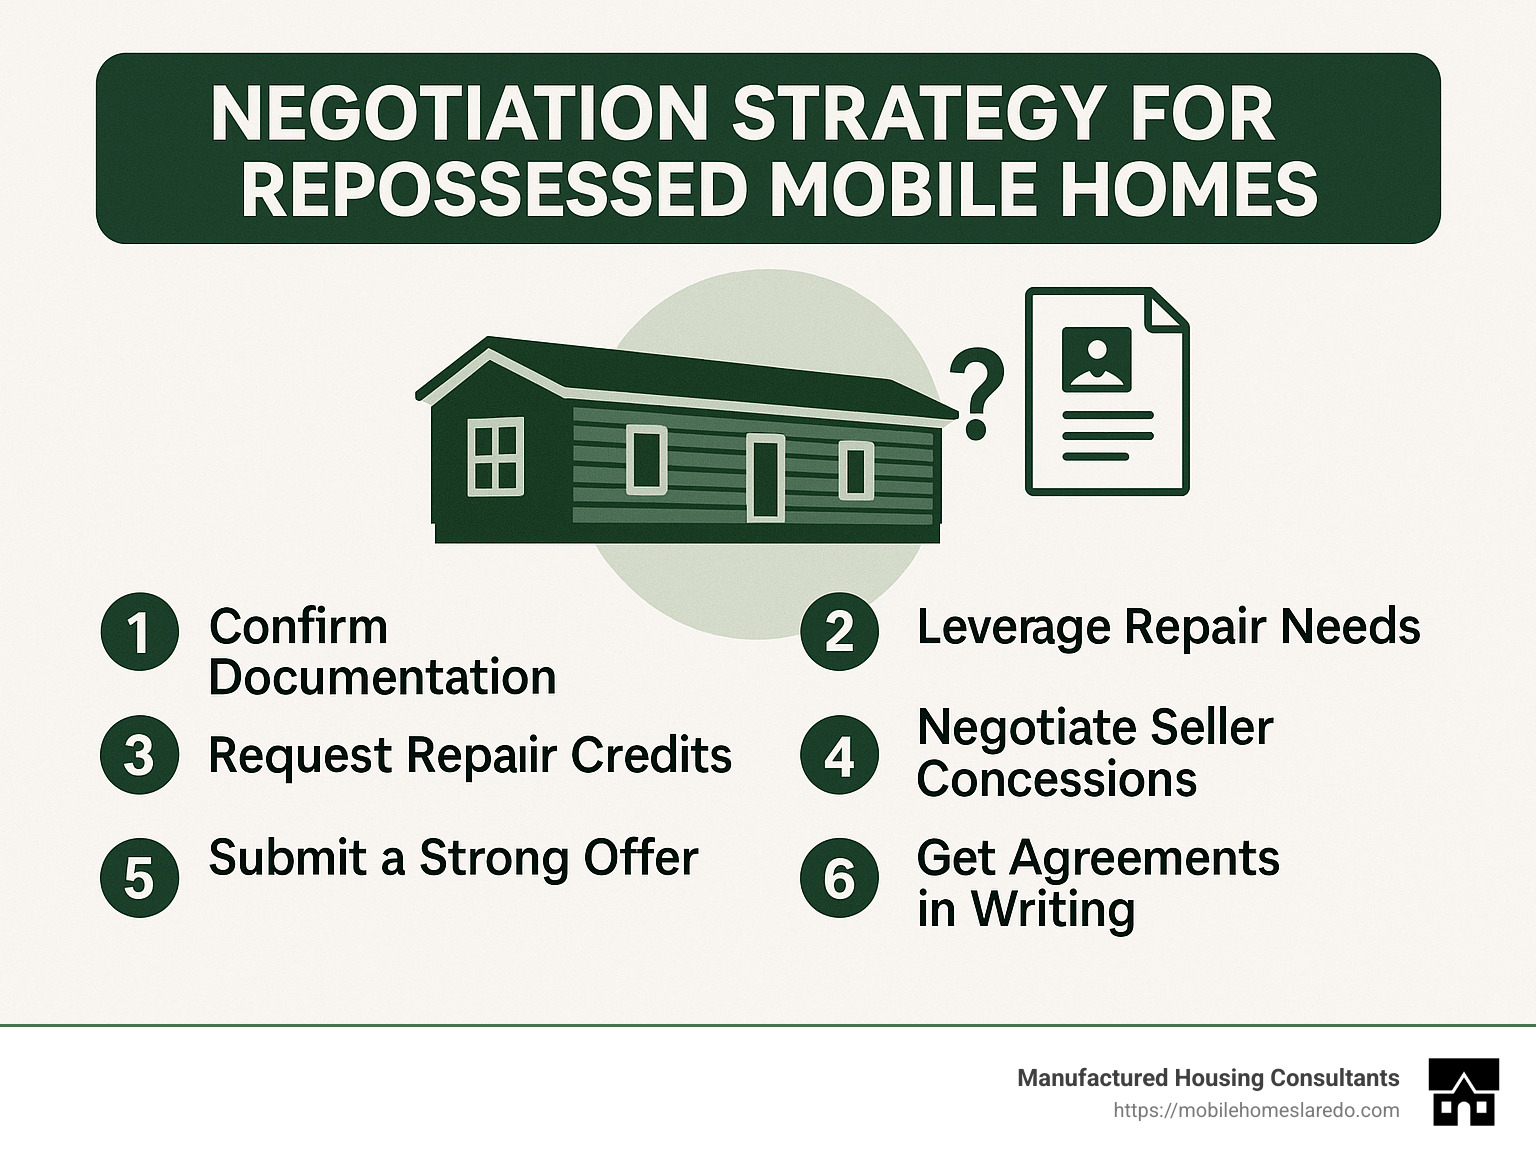
Here is the counter-intuitive part that nobody talks about. The actual repossession process is rarely the issue. The issue is what happens after the seizure. Lenders and park owners often sell these units quickly because they want the space vacated and the account closed. That urgency creates pressure on buyers to skip due diligence. You will hear things like "we need an answer today" or "another buyer is coming at noon." Most of the time that is manufactured. I have watched the same listing sit untouched for three weeks and then suddenly become urgent once a serious inquiry came in. The trick is to move at your own speed. If a seller cannot give you forty-eight hours to clear title and inspect the unit, walk away. That is not a deadline, that is a red flag. Another thing beginners consistently miss is the distinction between a manufactured home title and a real property title. When a mobile home is affixed to a foundation and zoned as real estate, it gets a deed, not a certificate of origin. Some scammers list repo mobile homes that are actually tied up in probate or being sold by someone with no authority over the property. I had a case where the listed seller was the brother of the deceased owner, not the executor, and he had absolutely no right to sell the unit. The paperwork he provided was forged. The fix here is simple: verify that the seller is either the legal owner, the authorized agent on the title, or the court-appointed executor. If they are any of those things, ask for documentation. If they hesitate, that is your answer. There are also scams where the unit being sold is not the one being repossessed. A seller might list a trailer that was properly repossessed and clear on title, then take your money and show you a different, problem-ridden unit. Or they sell you a unit that has been stripped of its own title and replaced with a duplicate. This happens more often than you would think. I found one instance where a vendor had created a duplicate title using a online service that does not cross-reference state databases. The original title was still active and held by the actual lender. By the time the buyer discovered this, the unit had been reclaimed and the duplicate title was worthless paper.
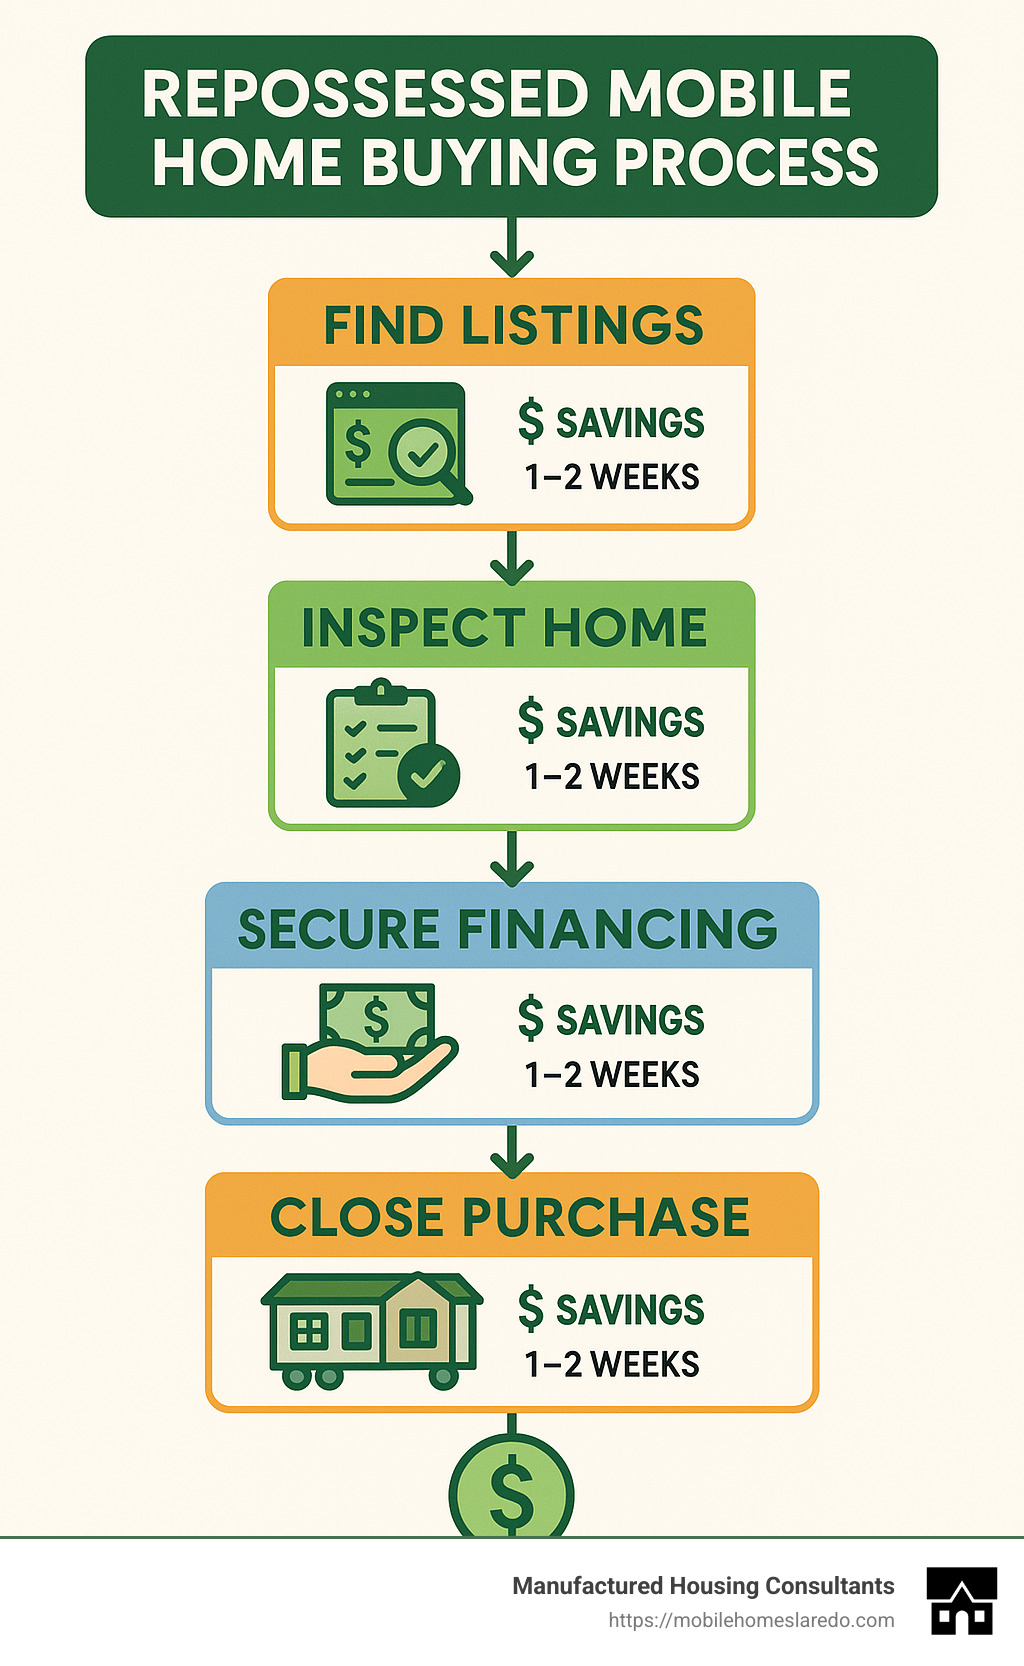
Not every repo sale is a scam, but the risk is skewed heavily toward fraud because the market operates with minimal standardization. There is no central listing database, no licensing requirement for sellers, and no mandatory disclosure framework for used mobile homes. The closest thing to protection is your own diligence. Run the VIN through three separate sources before you even schedule a viewing. Check the county recorder's office for any liens or judgments tied to the property address or the seller's name. And if the price looks too good, it almost always is. I recommend working with a mobile home specific title company if you can afford it. They charge somewhere between two hundred and five hundred dollars per transaction, and that money will save you ten times over if a problem surfaces. Most general title companies do not have the bandwidth or expertise to handle manufactured housing properly, which is why you see so many botched closings in this space. A mobile home title specialist will know to check for OEM numbers, verify the chassis serial against the HUD plate, and confirm whether the unit has ever been moved between counties or states, since each move can trigger a new titling requirement that may not have been completed. The bottom line is that repo mobile homes can be a legitimate path to a below-market purchase, but only if you treat every listing with the same skepticism you would apply to a foreclosure auction. The people making money in this space are not the ones buying the cheapest units. They are the ones who verified their titles before handing over a single dollar.
Get the Full Details