Getting Out From Under What You Owe at Desert Financial
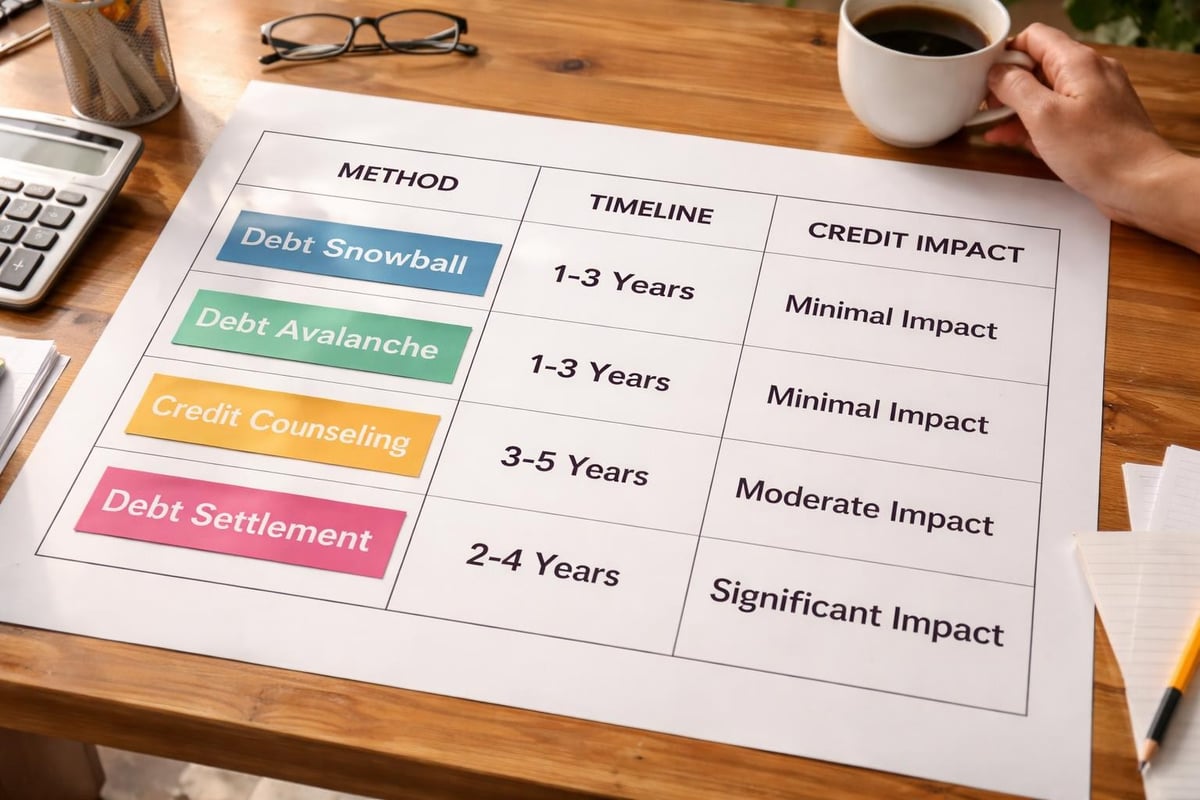
I've helped a handful of people sort through this over the years, mostly because the credit union industry doesn't always make its own processes obvious. Desert Financial is a legitimate Arizona-based credit union, and their debt repayment options are functional but not particularly intuitive if you've never navigated them before. The process works, it's just buried under enough menus that people often give up or fall for third-party debt management companies that charge fees for something you can do yourself. Let's start with what actually happens when you sit down to pay off debt there. Desert Financial offers several paths, and they're not all equal. You've got standard debt consolidation loans, balance transfer options on certain credit cards, and the default route of just paying minimums until you're forty-five years old and still paying for that furniture purchase from 2016. The consolidation loan is usually the move most people should consider, but there are catchments that nobody warns you about upfront. A debt consolidation loan from Desert Financial typically runs between 6.99% and 15.99% APR depending on your credit tier and employment verification. That might sound fine until you factor in the origination fee structure. Some loan products here tack on a 1% processing charge, which eats into the savings immediately if you're moving high-interest credit card balances onto a lower rate. Do the math before you sign anything. A $10,000 balance at 22% APR moved to a 9% loan with a 1% origination fee saves you roughly $1,280 in interest over three years, minus the $100 fee. The numbers still work in your favor, but barely, and only if you stick to the payment schedule without slipping.
Now, the actual process. Log into your Desert Financial account and navigate to the loan section. You'll find the debt consolidation product listed under personal loans. The application requires standard documentation: proof of income, Social Security number, current debt balances, and lender account details. Most people finish the online application in about twelve minutes. Funding takes three to five business days once approved, which is slower than some online lenders but faster than a traditional bank. Here's something that trips people up regularly. Desert Financial allows co-borrowers on consolidation loans, which can help if your credit score is stuck in the sub-700 range and you need someone with better standing to bring the rate down. But I learned this the hard way with a client last year. They added a sibling as a co-borrower to secure a lower rate, and when that sibling's financial situation shifted two years later, the entire debt became tangled in a way that made refinancing impossible. The co-borrower relationship means both parties are equally liable. There's no clean exit from that arrangement without paying off the loan in full or refinancing solely in one person's name, which usually requires the original co-borrower's credit to still be solid. Take that into account before you add anyone. If you're dealing with multiple Desert Financial accounts instead of external debts, the process simplifies considerably. You can pay off credit cards, auto loans, and personal loans all from within the same online banking portal. The key detail most people miss is the payoff quote request. When you want to clear a loan, don't just look at your current balance and assume that's what it costs to zero it out. Request an official payoff statement. The difference between your current balance and your payoff amount includes accrued daily interest, which for a typical auto loan or personal loan adds up to maybe twenty to forty dollars depending on how long you wait. It sounds small, but if you're being precise about this, the distinction matters.
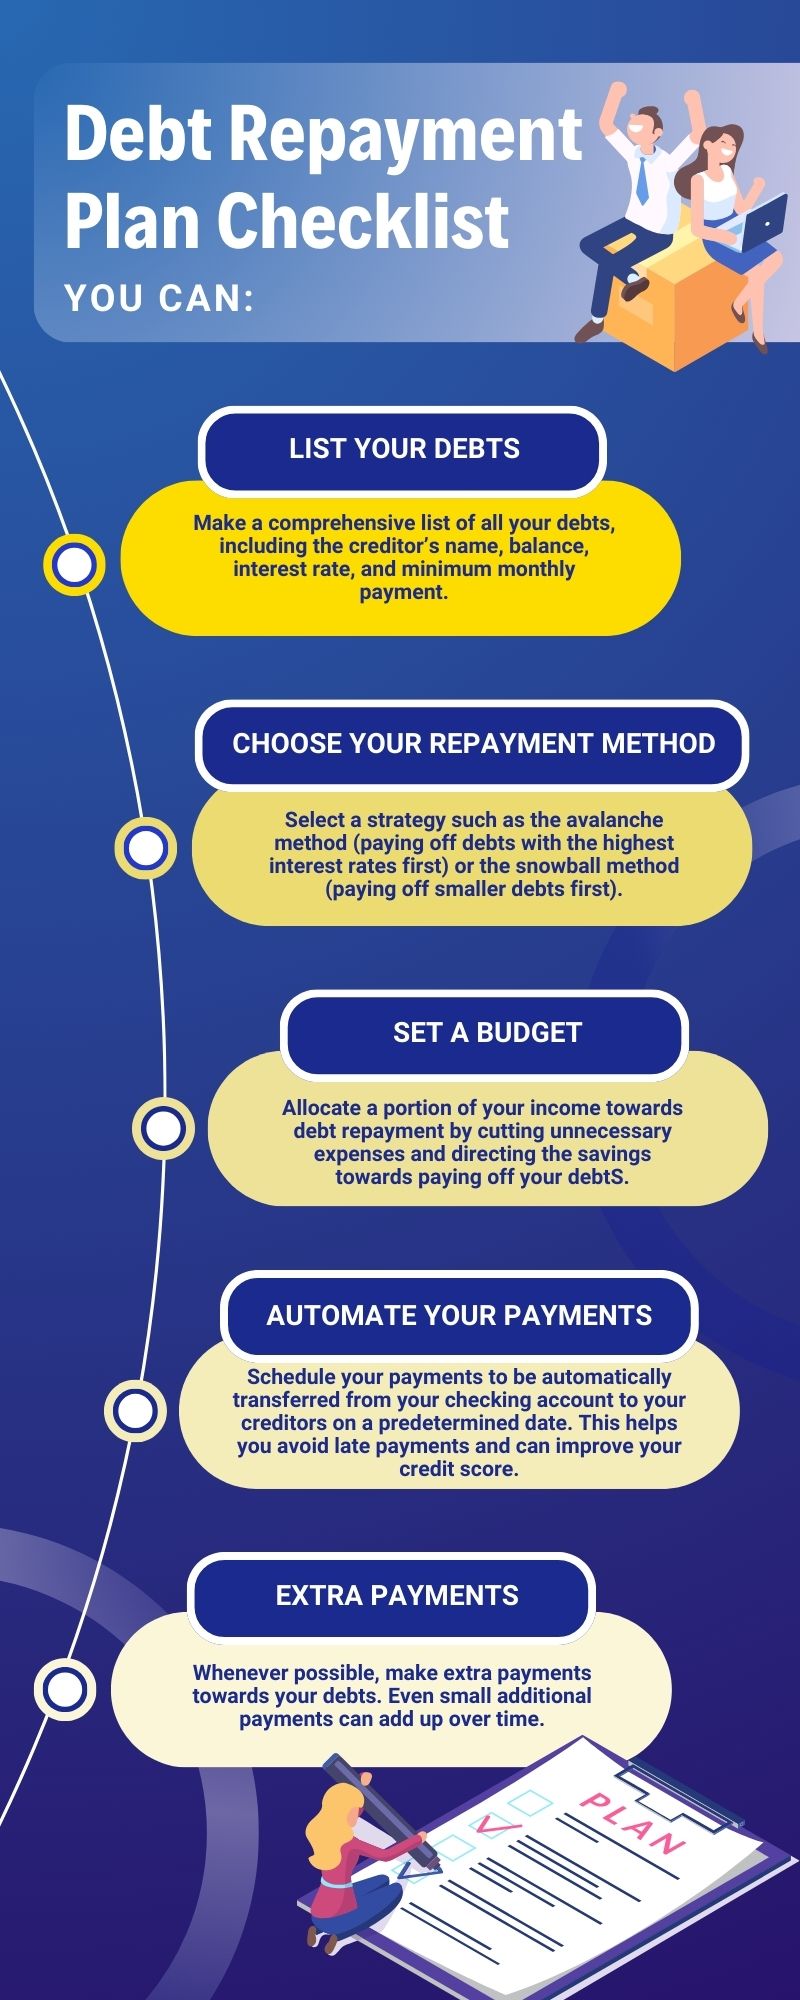
Balance transfers on Desert Financial credit cards operate differently. Some of their card products offer introductory 0% APR periods on balance transfers, usually ranging from twelve to eighteen months. The catch is the balance transfer fee, which typically sits at five percent of the transferred amount. Moving a $5,000 balance at 18% APR to a card with 0% for fifteen months and a 5% fee costs you $250 upfront but saves roughly $675 in interest over that period. The net gain is about $425, assuming you don't run the balance back up during the promotional window. And if you do, the standard purchase APR kicks in retroactively on some card agreements, which is a brutal clause that deserves a careful read before you proceed. One more thing worth noting. Desert Financial has a hardship program, but it's not advertised prominently. If you're facing genuine financial difficulty, you can contact their member services directly and request a review for temporary payment modifications or reduced interest rates. This isn't something you'll find in the FAQ section. It requires a phone call and documentation of your hardship, but I've seen people get their rates dropped by two or three percentage points for six to twelve months, which can make the difference between staying current and falling further behind. The approval rate isn't high, maybe thirty percent of requests, but it's free and there's nothing to lose by asking. The biggest mistake I see people make is trying to consolidate without first auditing every debt they hold. Pull your credit reports, list every creditor, note the interest rate and minimum payment on each, and then decide which ones actually make sense to move. Sometimes the math says keep your student loan where it is. Sometimes it says pay off the smallest balance first regardless of rate. There's no universal rule, just numbers that tell you what to do if you're willing to look at them honestly.
Get the Full Details