Getting Your Rental Property Financed Without Losing Your Mind
I spent three years trying to figure out rental property financing before I stopped treating it like regular residential mortgages. The difference isn't subtle, and most people don't realize it until they've already filled out five applications and gotten rejected by three lenders. The core problem with financing investment properties is that lenders see you differently than they see someone buying a home to live in. When you're applying for a mortgage on a property you'll occupy, the underwriter cares about your credit score, your debt-to-income ratio, and whether you have reserves. For a rental property, they also want to know if the numbers work on their own without your personal income propping them up. I learned this the hard way in 2019. I had a duplex in Columbus, Ohio that I wanted to buy. My credit was solid at 742, I made about $95,000 a year as a project manager, and I had about $60,000 saved. I went to a local bank, filled out the application, and thought I'd have an answer within a week. Four weeks later, they still hadn't decided because the appraised value came in $18,000 below the purchase price, and they wanted to re-evaluate my debt-to-income ratio including the potential rent from the second unit.
The workaround was simpler than I expected once I understood the process. I switched to a credit union that specialized in small multifamily loans, and they used a different calculation method. Instead of requiring the full mortgage payment on the property to count against my debt-to-income ratio, they allowed me to use 75% of the projected rental income from the unit I wasn't occupying. That single change turned a rejection into an approval with terms I could actually afford.
How the Numbers Actually Work
Most people approach rental property financing thinking they need 20 to 25 percent down. That's not wrong, but it's also not the whole picture. The real constraint is usually the lender's required debt service coverage ratio, which I'll explain in a moment. The down payment matters, but it's secondary to whether the property generates enough income to cover the debt. A debt service coverage ratio is calculated by dividing the net operating income by the annual debt service. If a property has an NOI of $24,000 and the mortgage payments total $30,000 a year, your DSCR is 0.80. Most conventional lenders want to see at least 1.20, which means the property needs to generate 20 percent more income than the mortgage requires. Some lenders will accept 1.00 for owner-occupants buying a multifamily property, but you're paying a higher interest rate for that flexibility. Here's what nobody tells you about this calculation: lenders often use the lower of two rental income figures. They'll take either the current rent roll or the market rent as determined by a comparative market analysis, whichever is smaller. If you're buying a property where the current tenant is paying below market rate, the lender will still use the market rate for qualification purposes, but the current actual rent is what counts toward your debt service coverage ratio. This discrepancy trips up a lot of first-time investors.
Get the Full Details
I encountered this exact situation with a triplex in Dayton. The previous owner had long-term tenants paying $850, $900, and $950 per month, totaling $2,700 monthly. The market rents for similar units in the area were closer to $1,100, $1,150, and $1,200. The lender qualified the loan using the current rents, which meant my DSCR was 1.08 instead of the 1.35 I would have had with market rents. I needed an additional $12,000 in cash reserves to compensate for the lower ratio, which was the difference between approval and a request to increase my down payment.
Loan Types and When to Use Each One
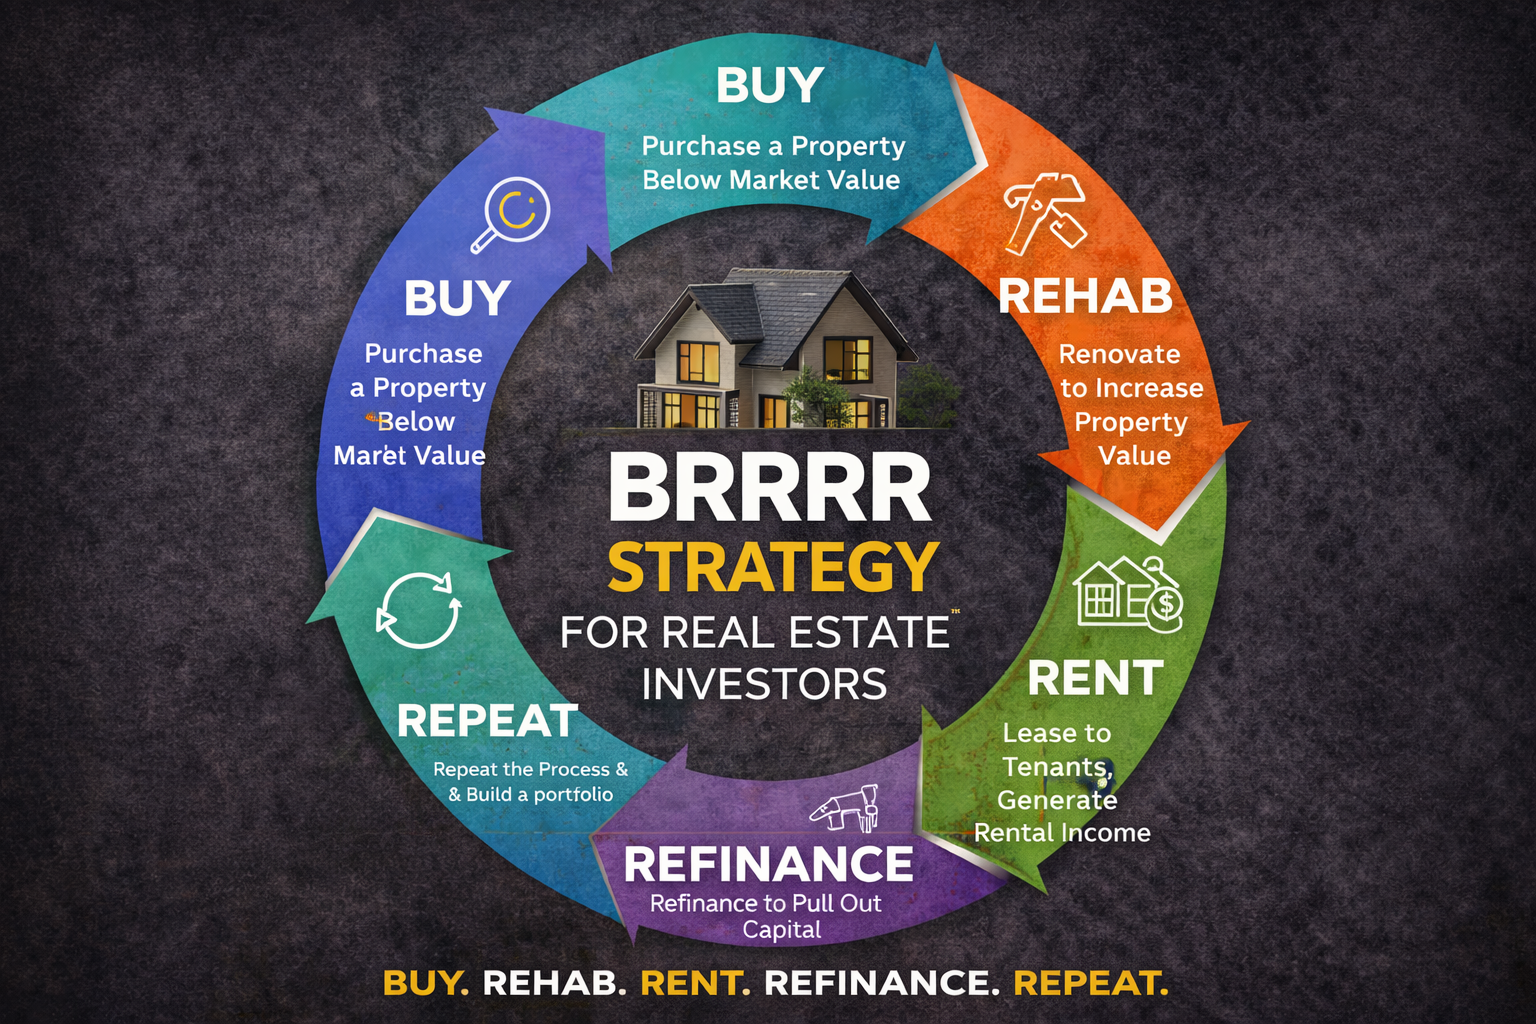
Conventional investment property loans typically require 25 percent down and carry interest rates about 0.5 to 0.75 percent higher than owner-occupant rates. Fannie Mae and Freddie Mac back these loans, and they have strict guidelines about what counts as rental income. You need to show that the property has been owned for at least 12 months before you can use 100 percent of the rental income, or you'll be limited to 75 percent of the projected rent. Portfolio loans are another option, particularly if you're working with a regional bank or credit union. These loans stay on the lender's books instead of being sold on the secondary market, which means they can be more flexible with their criteria. I've seen portfolio loans approved with DSCRs as low as 1.00 and down payments around 20 percent. The tradeoff is higher interest rates and sometimes prepayment penalties that can cost you several thousand dollars if you refinance within the first few years. Hard money loans exist for situations where you need speed over savings. If you're bidding on a foreclosure auction and need to close in 14 days, hard money might be your only option. The rates are brutal—often 10 to 14 percent—and the points can add 3 to 5 percent to your closing costs. I used a hard money loan once for a property that needed $40,000 in repairs before I could refinance into a conventional loan. The total cost of the hard money loan, including points and interest, was about $8,500 over nine months. That felt steep at the time, but it was cheaper than losing the deal entirely.
Common Pitfalls That Waste Money
One mistake I see repeatedly is underestimating vacancy rates. Lenders typically use a flat 5 to 10 percent vacancy allowance when calculating rental income, but some markets have seasonal vacancies that spike much higher. If you're buying in a college town with summer vacancies, the lender's standard 5 percent assumption might leave you underprepared for the actual cash flow shortfall. Another issue is property management fees. Most lenders don't include property management in their calculations, but if you're not living near the rental property, you'll likely need a management company. The standard rate is 8 to 10 percent of collected rent, which significantly impacts your net operating income. I learned this with a property in Cincinnati that I managed remotely. The lender approved the loan based on $1,800 monthly rent with no vacancy or management deductions. My actual cash flow after paying a property manager and accounting for summer vacancies was only $450 per month instead of the $800 I had projected. Capital expenditure reserves are the third silent killer of rental property deals. Lenders rarely require you to set aside money for roof replacements, HVAC failures, or appliance breakdowns, but these expenses happen regardless of what the underwriter says. A good rule of thumb is to reserve 5 to 10 percent of gross rental income for capital expenditures, which translates to about $150 to $300 per month for a typical single-family rental.
When Rental Property Financing Doesn't Make Sense
Sometimes the numbers simply don't work, and continuing to pursue financing is just delaying the inevitable. If a property requires a down payment larger than 30 percent, carries an interest rate above 8 percent, and still produces a negative cash flow after all expenses, you're better off walking away. I passed on a four-unit property in 2021 that met all three of these conditions. The seller wanted $450,000, the lender required 35 percent down due to the property's age and condition, and the rent rolls barely covered expenses even at full occupancy. Walking away felt uncomfortable at the time, but staying in that deal would have drained my reserves within the first year. Analogous situations occur when the local market shows signs of deterioration that aren't yet reflected in national data. If you're seeing increasing days on market, rising vacancy rates, and declining rent growth in your target neighborhood, financing terms might still be favorable even though the fundamentals are weakening. In those cases, I recommend either avoiding the purchase altogether or structuring the deal with seller financing to reduce your upfront capital requirement.
What I Wish I Knew Before Starting
The most valuable lesson from my experience is that rental property financing is not a one-size-fits-all process. Different lenders have different risk tolerances, and the same property can receive completely different approvals depending on which institution you approach. I've seen identical properties approved at one bank with a 1.25 DSCR requirement and rejected at another bank that demanded 1.35. Shopping around between five or six lenders before committing to one application saves time and often reveals significantly different terms. The second insight is that your personal financial situation changes how lenders evaluate you. If you have a stable job with three or more years of continuous employment, you'll receive more favorable treatment than someone who recently changed positions. Similarly, if you have existing rental properties with strong DSCRs, lenders may view additional acquisitions more positively than they would a first-time investor.
Practical Steps for Your First Rental Property Loan
Start by gathering your financial documents before you even look at properties. You'll need W-2s or tax returns for the past two years, bank statements showing your assets and reserves, a list of all current debts and monthly payments, and documentation of any rental income from existing properties. Having these ready speeds up the pre-approval process significantly and signals to sellers that you're a serious buyer. Next, get pre-approved with at least two lenders before making offers. Pre-approval isn't the same as pre-qualification, and the distinction matters when you're competing against other buyers. A pre-approval letter from a specific lender carries more weight than a generic statement from a mortgage broker. I've seen offers rejected because the seller preferred buyers with pre-approvals from established local banks over those with pre-qualifications from national online lenders. Finally, budget for closing costs beyond the down payment. Rental property closing costs typically range from 2 to 5 percent of the purchase price, which includes origination fees, appraisal costs, title insurance, and various lender-required inspections. On a $300,000 property, expect to pay between $6,000 and $15,000 at closing, which is money that comes out of your reserves instead of going toward the down payment.