Understanding the Land of Rent-to-Own
Most people looking into rent to own mobile homes in ohio don't realize how many ways this can go sideways before you even sign a lease. I've spent years watching people get locked into agreements that looked like home ownership on paper but ended with them owing money they didn't have. The basic idea is straightforward: you rent a manufactured home with a portion of your monthly payment going toward a future purchase option. The tricky part is that everything hinges on the fine print, and the fine print is where most deals fall apart.The typical structure involves three main components: the monthly rent, an option fee paid upfront, and a lease term that can range from one to five years. During that time, a predetermined portion of your rent builds equity toward the eventual purchase price. At the end of the term, you either buy the home at the agreed-upon price or walk away, losing whatever payments went toward the option credit.
Rent To Own Mobile Homes In Ohio A Brief Guide To Affordable Housing Options
Ohio has specific regulations around manufactured housing that make this process different from buying a traditional home. Under Ohio Revised Code Section 4501, manufactured homes can be classified as personal property or real property depending on whether they're attached to land you own. This distinction matters enormously because if the home is personal property, your rent-to-own agreement functions more like a vehicle lease than a traditional real estate transaction. The credit reporting, financing options, and even your ability to sell the home later all change based on that classification.I learned this the hard way back in 2019 when I worked with a family in Hamilton County who signed a five-year rent-to-own contract for a 1998 single-wide in a private park. The park owner told them the home would transfer to their name at the end of the lease. It didn't matter that the deed to the home was still under the park owner's name and that the zoning classified the structure as personal property. When the family completed their payments, the park owner refused to transfer the title, and since the home was legally personal property with no land owned, the family had almost no legal standing to force the sale.
The Two Types of Rent-to-Own Agreements
There are two fundamentally different structures out there, and confusing them is a common mistake. The lease-option agreement gives you the right but not the obligation to buy the home at the end of your lease term. You can walk away at any point without penalty beyond losing any option credits. The lease-purchase agreement, on the other hand, legally commits you to buying the home at the end of the term. Walking away under a lease-purchase means breach of contract, and the seller can pursue legal action to recover damages.Most legitimate rent-to-own arrangements in Ohio lean toward lease-options because they protect both parties reasonably. I've seen far fewer problems with lease-option agreements than lease-purchase contracts, which often contain clauses that favor the seller significantly. A lease-purchase agreement basically guarantees you'll own the home, but it also means you can't escape even if you lose your job or the home needs major repairs. The tradeoff feels worth it until it isn't.
Get the Full Details
How Monthly Payments Actually Work
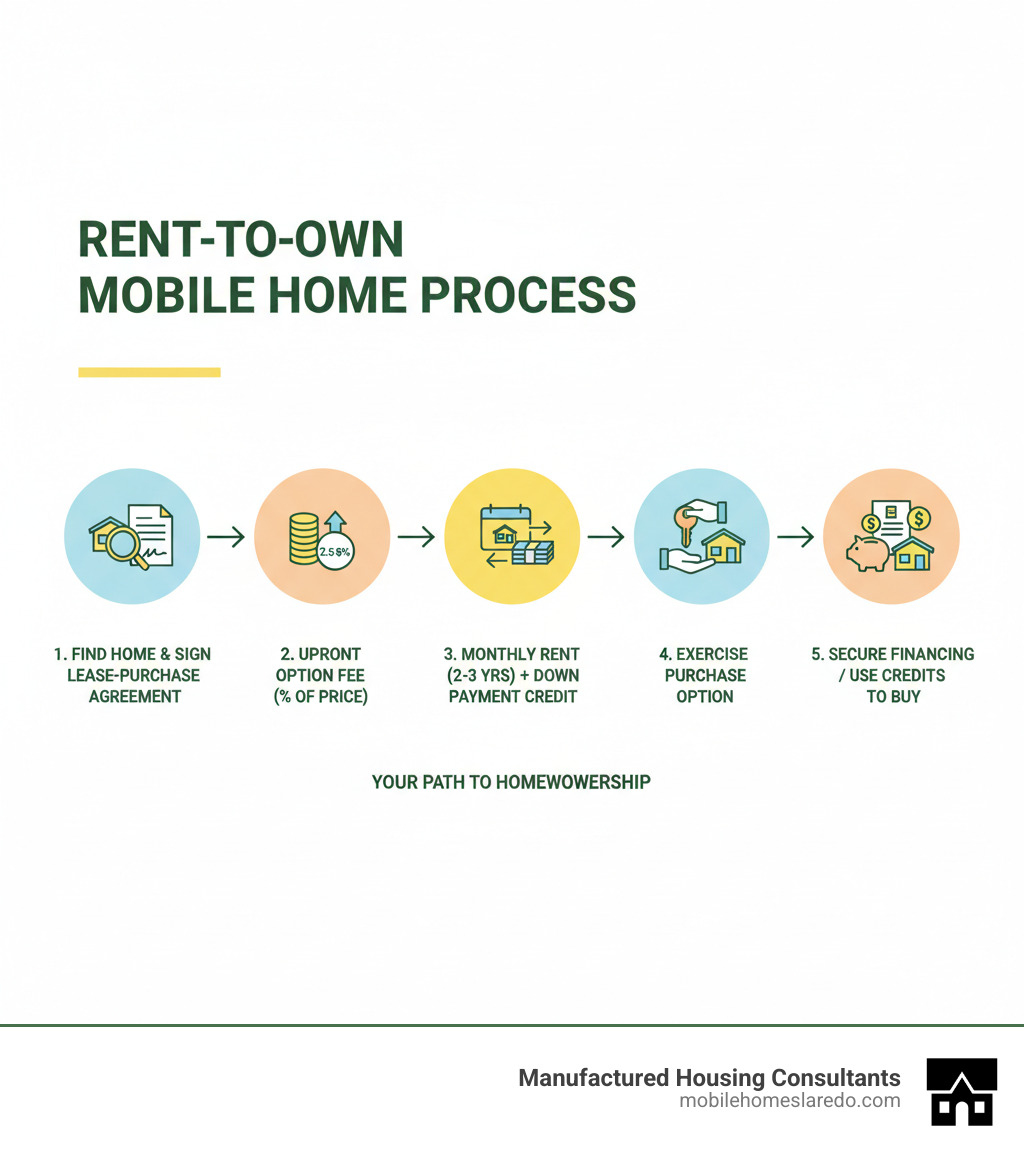
The rent portion of your payment covers the use of the home and the land it sits on. The option credit portion is what builds toward your purchase price. A typical split might look like six hundred dollars going toward rent and two hundred dollars going toward the option credit each month. Over a three-year term, that twenty-four thousand dollar credit accumulates, and your purchase price is locked in at the start of the agreement regardless of market changes.The purchase price you agree to upfront is critical. In a seller's market, locking in a price three years early can be a huge advantage. In a declining market, you might end up agreeing to pay more than the home is actually worth by the time your lease ends. I've seen instances where the original purchase price was set at market value, but over three years of depreciation on a used manufactured home, the actual market value dropped by fifteen to twenty percent. The buyer was still obligated to pay the higher price under a lease-purchase structure.
What to Look for in a Legitimate Deal
A legitimate rent-to-own agreement in Ohio should clearly state the monthly rent amount, the option credit amount, the purchase price, the lease duration, and who is responsible for maintenance and repairs. The contract should specify whether the home is classified as personal or real property. It should also outline what happens if you miss a payment and whether there's a grace period. If any of these details are vague or missing, you should treat the deal as a red flag.The title status of the manufactured home is the single most important factor. Before signing anything, you need to verify the title with the county auditor's office or through the Ohio Bureau of Motor Vehicles if the home is classified as personal property. A clean title with no liens means the seller actually owns the home and can sell it to you. A title with active liens means you could inherit debt along with the home, and a title held by a third party like a bank or the park owner means you might never get clear ownership regardless of how many payments you make.
Maintenance Responsibilities and Hidden Costs
One area where renters often get caught off guard is maintenance responsibility. Some agreements place all repair costs on the tenant while others split responsibility. In a standard residential lease, the landlord handles major structural repairs. In a rent-to-own agreement, the terms can be negotiated, and sellers often shift more responsibility onto the buyer-tenant. A roof leak that costs three thousand dollars to fix becomes your problem if the contract says you're responsible for all repairs.Additional costs to budget for include homeowners insurance, property taxes if the home is real property, park fees if the home sits in a manufactured housing community, and utilities. These expenses are separate from your monthly rent and option credit payments. I once encountered a situation in Dayton where the buyer was unaware that the manufactured home park charged a separate lot rent of four hundred fifty dollars per month on top of the rent-to-own payment. That pushed the total monthly cost nearly sixty percent higher than what was advertised, and the buyer couldn't move out until the lease term ended because of the lease-purchase clause.
Financing Your Purchase at the End of the Lease
The whole point of a rent-to-own agreement is that you eventually buy the home, so having a realistic plan for financing is essential. Most buyers in rent-to-own programs are working to rebuild their credit or save for a down payment during the lease term. By the end of the agreement, you'll likely need a conventional mortgage, an FHA loan, or a manufactured home loan to complete the purchase. If your credit hasn't improved enough by then, or if your income has changed, you might not qualify for financing when it matters most.The good news is that a portion of your rent payments may appear on your credit report if the seller reports them to the major credit bureaus. Not all sellers do this, so it's worth asking upfront whether they report payment history. Consistent on-time payments can help improve your credit score over the lease term, which directly affects your loan options and interest rate when you're ready to buy. A higher credit score could mean the difference between a five percent interest rate and an eight percent rate on a twenty-year manufactured home loan, which translates to tens of thousands of dollars over the life of the loan.
Steps to Take Before Signing
Start by verifying the title status of the manufactured home and checking for any liens or encumbrances. Have a real estate attorney review the contract before you sign, even if it costs a few hundred dollars. Get a professional inspection of the home to assess its condition and estimate future repair costs. Research comparable sales in the area to confirm the purchase price is fair. Ask the seller about their reporting practices for credit bureau payments. Finally, understand exactly what happens if you can't continue making payments before the lease term ends.I always tell people to calculate the total cost of ownership including all monthly payments, option credits, maintenance, insurance, taxes, and park fees over the full lease term. Compare that total to what you would pay renting a comparable home in the same area. The numbers sometimes favor rent-to-own, especially if your credit is limited and traditional financing is difficult to obtain. But in other cases, renting and putting the difference into a dedicated savings account for a down payment turns out to be the smarter financial move.
When Rent-to-Own Makes Sense and When It Doesn't
Rent-to-own works well for people who want to live in a manufactured home but need time to improve their credit or save for a down payment. It works for buyers who have found a home they love and want to lock in a price before the market moves further. It also suits people who prefer the stability of a longer-term arrangement over month-to-month renting. What it doesn't work for is people who aren't financially disciplined enough to maintain consistent payments or who can't afford the additional costs beyond the base rent.It also doesn't work well if you're not certain about your long-term plans. Moving for a new job after two years into a three-year lease-purchase agreement means you're on the hook for the remaining payments or you lose all your option credits. Buying a used manufactured home is already risky because these structures depreciate like vehicles rather than appreciate like site-built homes. Adding a lease structure on top of that risk compounds the uncertainty significantly.
Resources and Where to Find Deals
Ohio's manufactured housing resources include county auditor offices for title searches, the Ohio Manufactured Housing Association for industry information, and the Ohio Attorney General's consumer protection division for filing complaints about deceptive practices. Online listings on sites like Zillow and Manufactured Housing Digest can surface rent-to-own opportunities, but they often list deals from both legitimate sellers and predatory operators. Working with a local real estate agent who specializes in manufactured housing is usually the most reliable way to find vetted opportunities.The Ohio Housing Finance Agency occasionally lists affordable housing programs that may include rent-to-own options or down payment assistance programs that could make a traditional purchase feasible sooner than expected. It's worth checking their current offerings before committing to a rent-to-own arrangement, because qualifying for a conventional loan with a modest down payment assistance program might be cheaper than paying option credits on an overpriced home over three years.