How Rent-To-Own Actually Works in Princeton, West Virginia
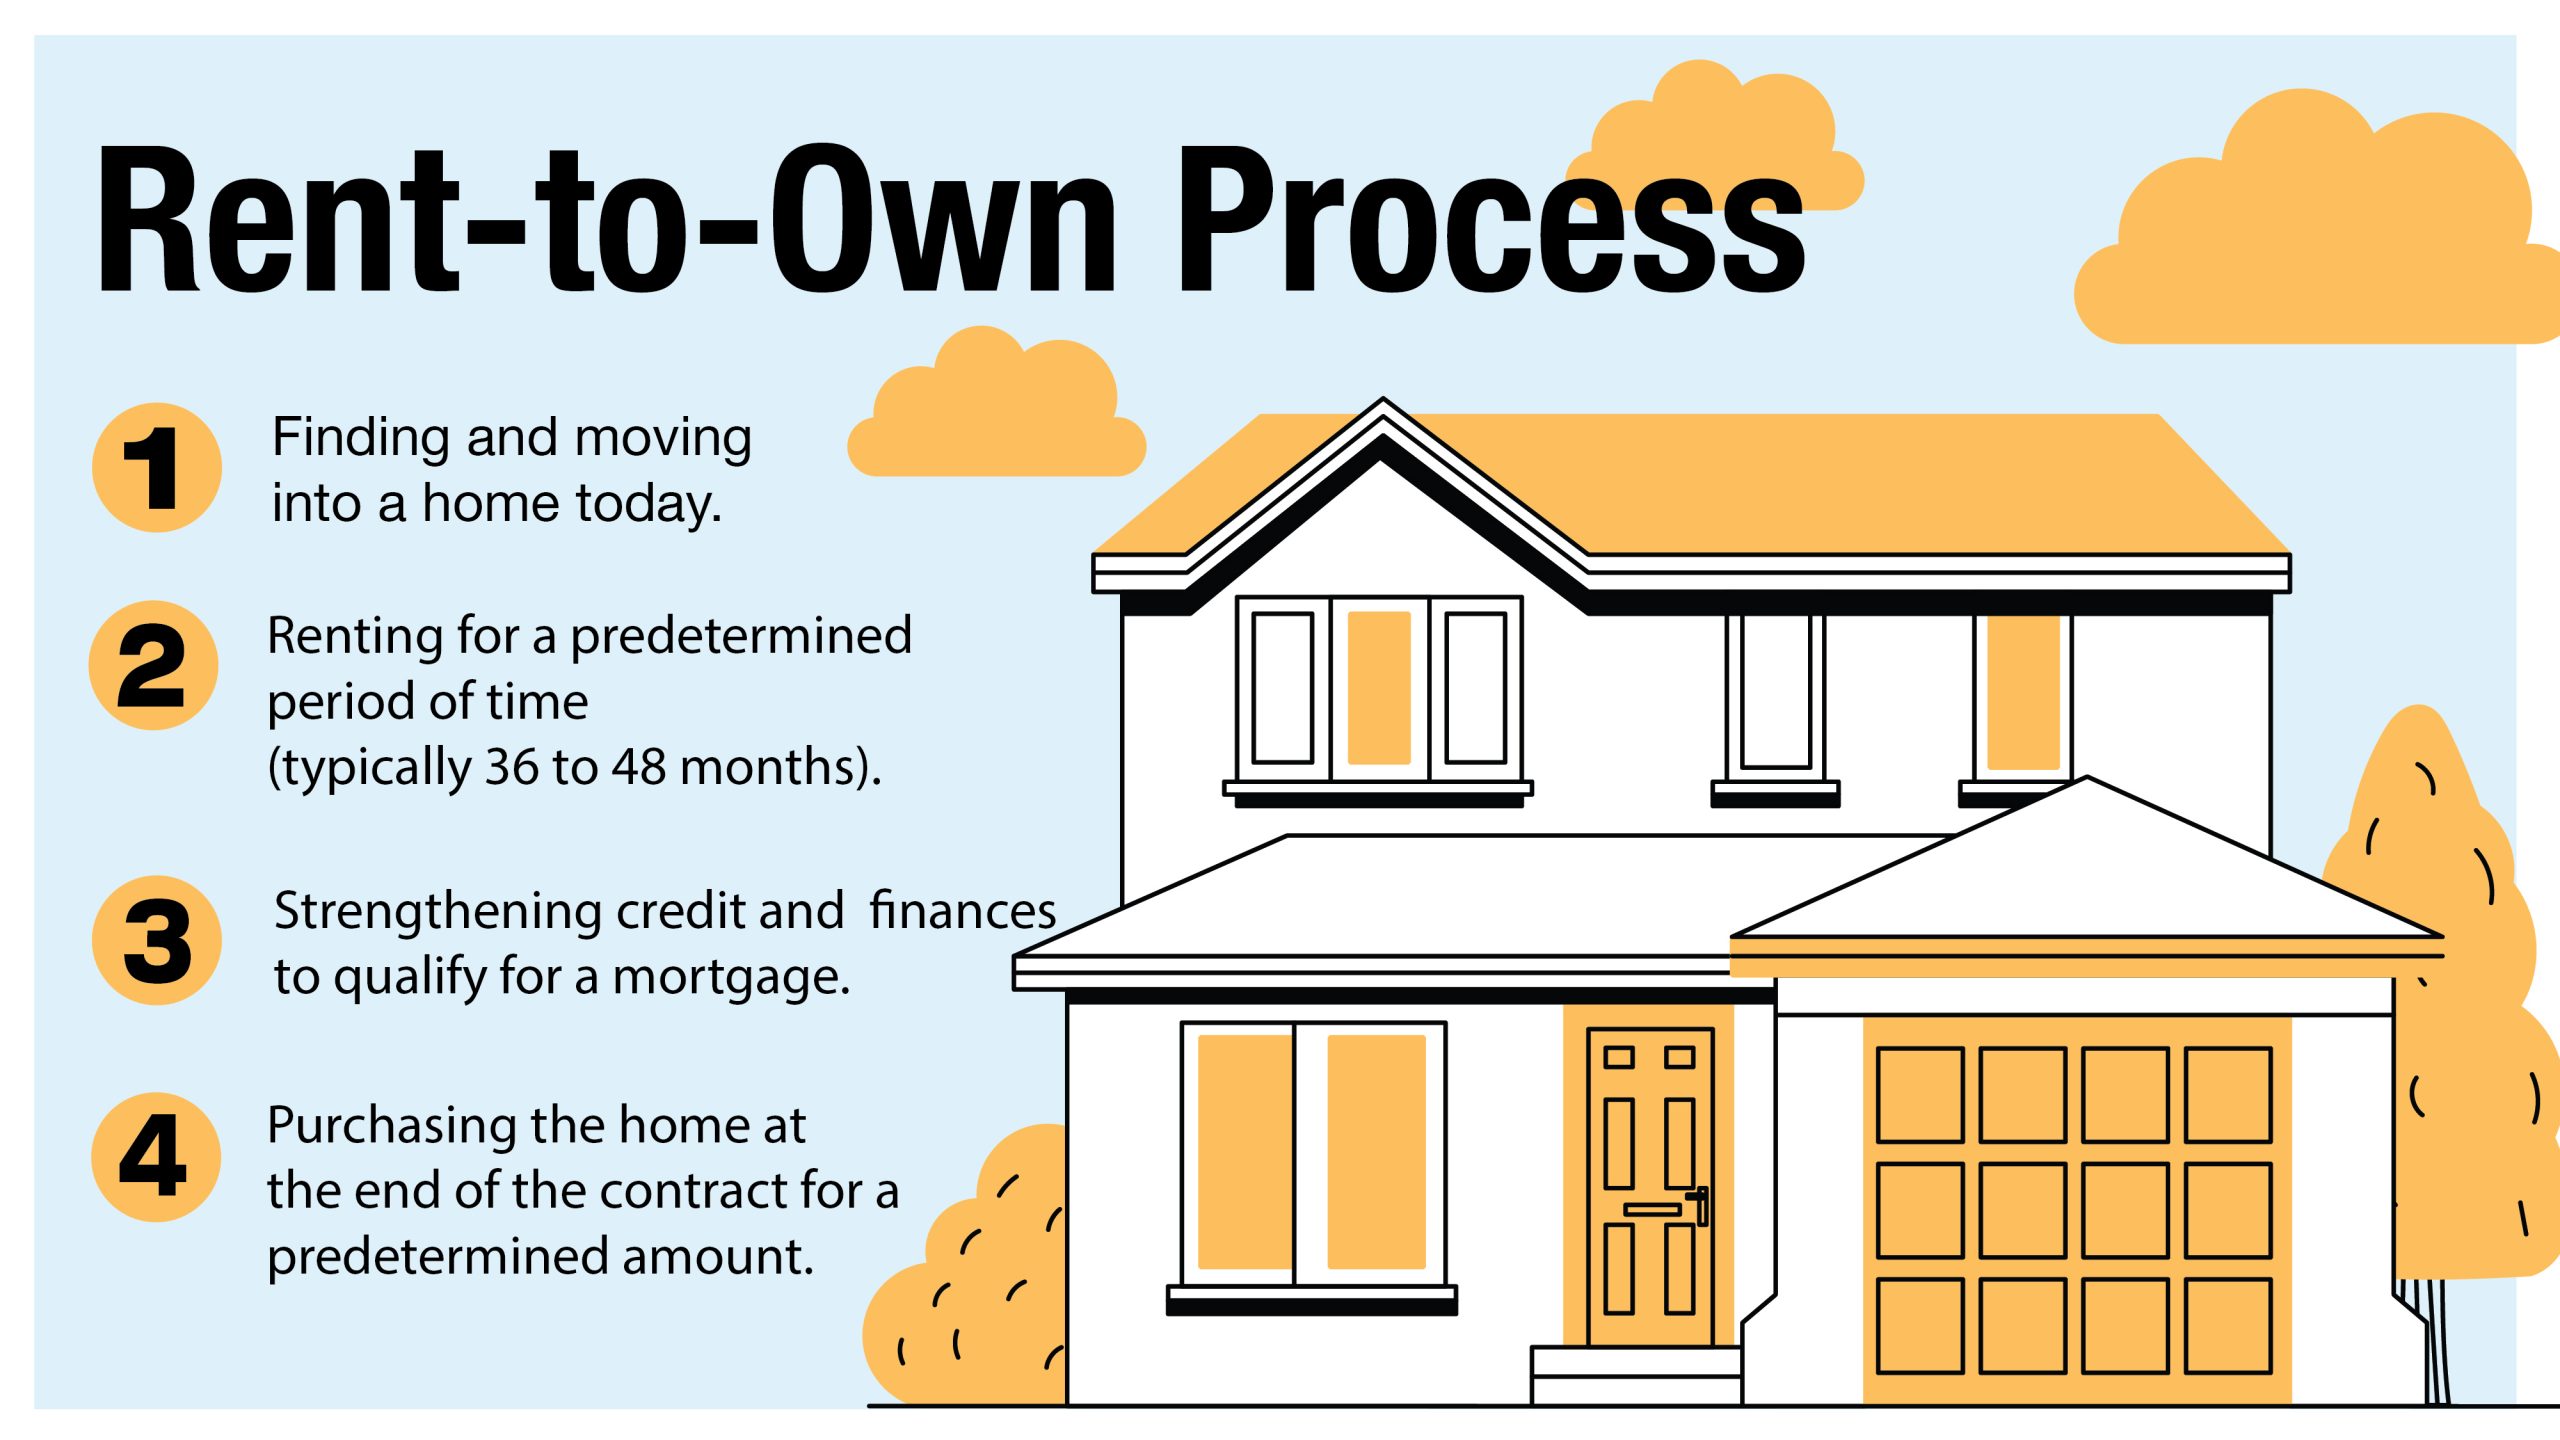
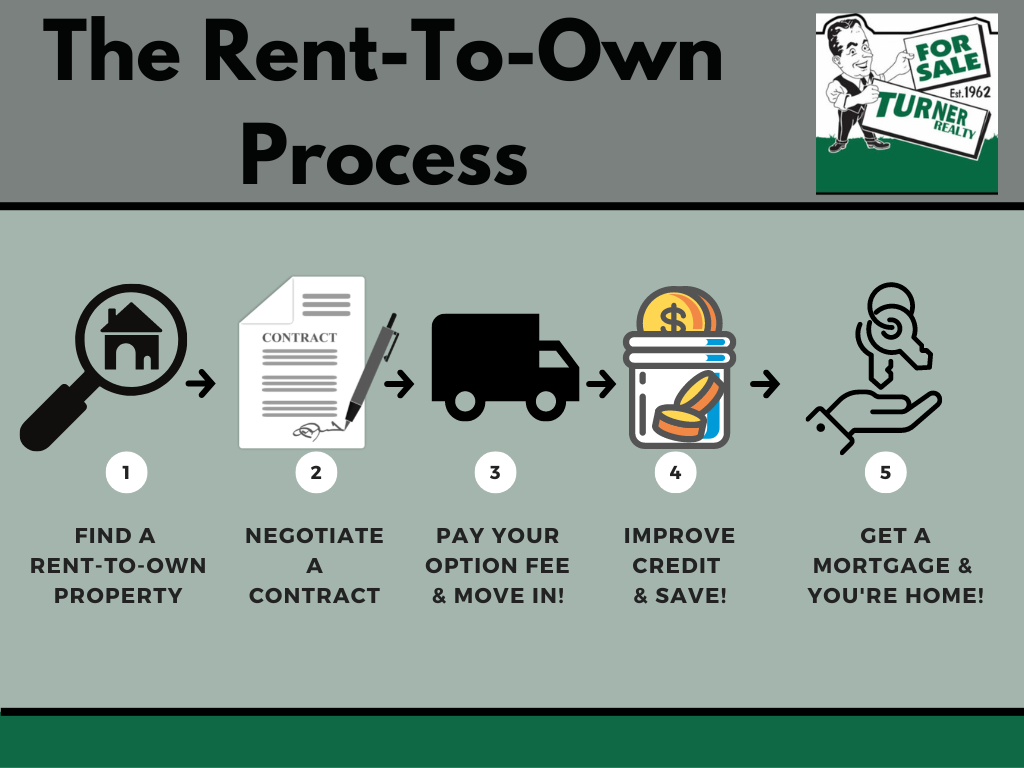
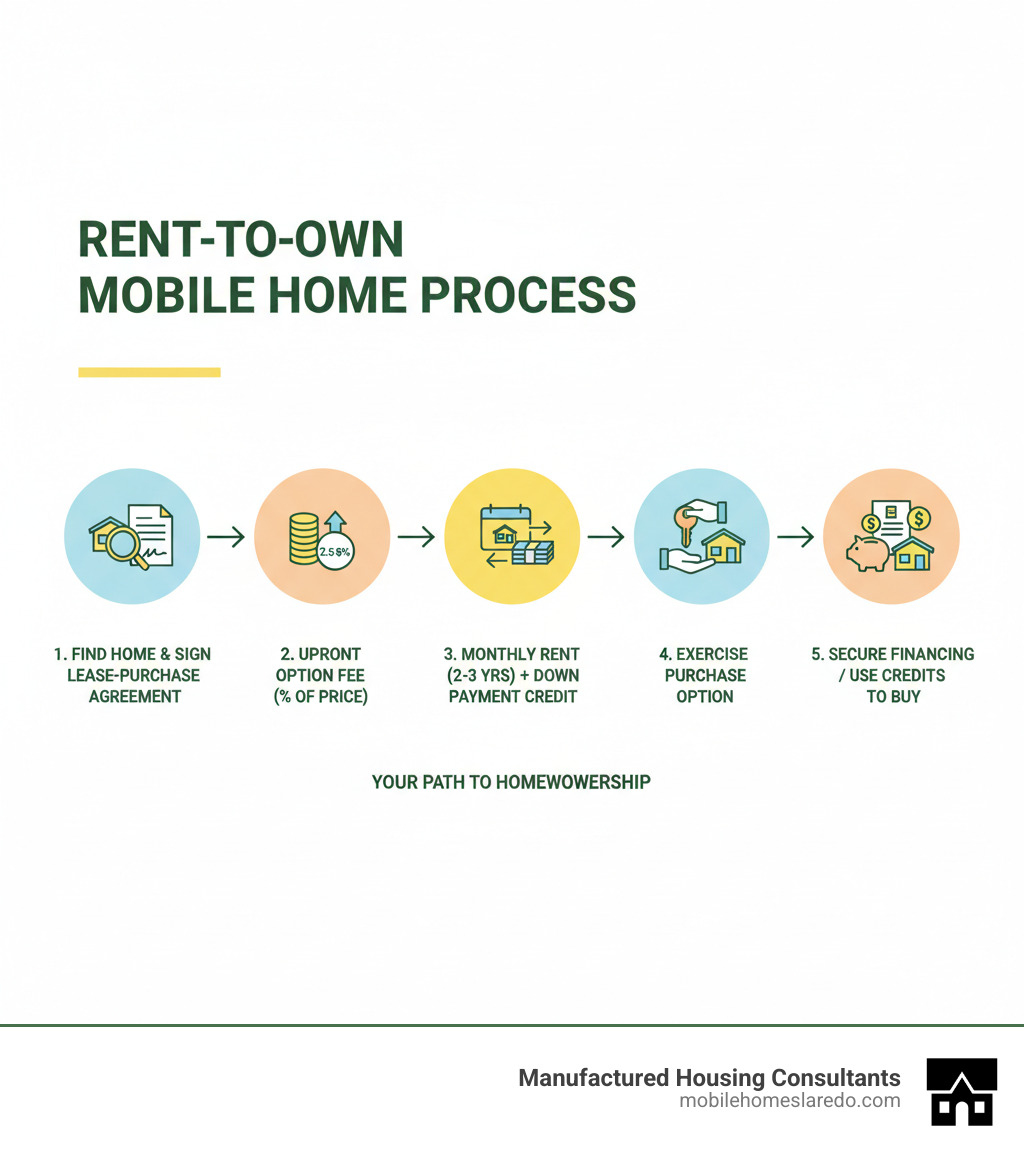
Princeton is a small market, which means rent-to-own deals here don't move fast. When a property hits the rent-to-own pool, it's usually because the seller has been trying to sell it the traditional way for six to twelve months and hasn't found a buyer. That's the starting point. Understanding that context changes how you approach the deal. The structure is straightforward on paper. You sign two documents simultaneously: a lease and an option to purchase. The option gives you the right, but not the obligation, to buy the home at a predetermined price within a set window. During the lease period, a portion of your monthly rent goes into an escrow account as a rent credit toward your down payment. At the end of the term, you either exercise the option and secure a mortgage, or you walk away and lose the credits you accumulated. The option price is negotiated upfront. In Princeton, most sellers lock in today's market price or add a modest escalation clause of two to four percent per year. I've seen some push for five to seven percent escalations in hot micro-markets, but that's rare here. The rent premium you pay above market rate typically funds the option consideration and the rent credits. A standard credit runs one to three percent of the monthly rent. So if you're paying $1,100 a month with a two percent credit, you're banking roughly $22 each month toward the purchase.
The term length is another variable. Most deals run two to three years. Longer terms give you more time to repair credit or save, but they also tie up the option price longer, which increases your exposure if the market shifts against you. Shorter terms compress everything and can work if you're close to qualifying for a loan on your own.
What to Watch for Before You Sign
The first document to scrutinize is the option agreement, not the lease. The lease governs your day-to-day responsibilities. The option agreement is where the money lives. I had a client, let's call him Marcus, who signed a three-year rent-to-own in a neighborhood just off US-60. He spent the first eighteen months focusing on getting his credit score from 560 to 620 because that's what he thought mattered most. He was right about the score, but he completely missed the maintenance clause. The agreement stated that any repairs over $500 were his responsibility, and the property needed a new roof within the first year. That was a four-thousand-dollar hit he never anticipated because nobody pointed it out during walkthrough. His workaround was simple: he hired a local inspector who specialized in older homes, spent about three hundred dollars, and discovered the roof and a couple of other issues before signing. He renegotiated the credit percentage and got the seller to cover the roof. It took two extra days of negotiation and maybe an hour of phone calls, but it saved him thousands. Here's something most people don't consider. In Princeton, property taxes can shift during your lease term. The county reassesses values periodically, and while that doesn't immediately change your rent, it can affect the overall cost structure if the seller passes tax increases through the lease. One deal I reviewed had a clause that adjusted the monthly payment whenever the annual property tax bill changed by more than ten percent. Over a three-year term, that added about forty dollars a month. Not catastrophic, but it's a detail that quietly eats into your budget. Another thing to check is the default clause. Standard language says if you miss one or two payments, the option is void and you lose all credits. Some sellers, especially individual landlords rather than companies, will write in a more forgiving cure period of thirty to sixty days. In a tight market like Princeton, that flexibility matters more than you'd expect. A single late payment due to a Paycheck Protection Program delay or a temporary job gap shouldn't erase every dollar you've banked.
Get the Full Details

The Financing Reality
This is where rent-to-own trips people up. The whole point is that you can't get traditional financing right now. But at the end of the lease term, you absolutely need to qualify for a loan. FHA, conventional, VA — pick one and start preparing before you sign the lease. Here's the practical timeline that works in my experience: begin credit repair and debt reduction at least eighteen months before your intended purchase date. That gives you a buffer for unexpected dips. Pull your credit reports from all three bureaus and dispute anything inaccurate. Disputes can take forty to ninety days to resolve. If you wait until month twenty-three to start that process, you'll be scrambling. Save for more than the option price requires. The rent credits might cover five to eight percent of the purchase price over three years. Most lenders want a minimum of three to five percent down for FHA, and conventional loans often require more depending on your score. In Princeton's current market, a three-bedroom house in decent condition runs roughly $130,000 to $180,000. Eight percent down on a $150,000 home is $12,000. If your credits only generate $6,000, you need an additional $6,000 from savings. Budget for that gap from day one. Get pre-qualified before the lease ends. Not pre-approved, just pre-qualified. This tells you early if your financial profile is on track. If the numbers look bad six months before the option expires, you have time to adjust. If they look bad one month before, you don't.
When Rent-To-Own Makes Sense and When It Doesn't
In Princeton, rent-to-own works best for people who have a clear path to homeownership within two to three years but need the extra time to stabilize their finances. Maybe you're finishing school. Maybe you're recovering from a medical event. Maybe you have a steady job but inconsistent credit history. The structure buys you time. It doesn't work if you're unsure about staying in the area. The credits you lose if you walk away are real money. They don't come back. If there's any chance you'll relocate for a job or family reason, skip the rent-to-own and rent normally. You'll save money and avoid the complexity. It also fails when the property has significant deferred maintenance. I've seen homes listed as rent-to-own that needed foundation work, updated electrical, and outdated plumbing. The rent credit structure doesn't account for those costs. You're paying a premium rent while simultaneously budgeting for major repairs. In one case, the option price was set at $145,000, but after repairs the home was easily worth $170,000. The deal looked good on paper, but the upfront repair capital required was nearly impossible to muster alongside the lease payments. The alternative for that situation would have been to rent the property while saving independently and buying through a conventional purchase later.
The biggest pitfall I see isn't financial. It's legal. Many rent-to-own agreements in this area are drafted by sellers using generic templates found online. Those templates often omit key protections for the tenant-buyer. Hiring a real estate attorney in Mercer County to review the contract before you sign costs about eight hundred to fifteen hundred dollars. It's not optional. That review catches clauses that would otherwise cost you significantly more down the line. A thirty-minute call with a local attorney can identify problems that save you thousands. If you're looking at specific listings, start with local sources. The Princeton Daily Clatter, local Facebook groups, and the Mercer County real estate offices tend to list rent-to-own properties before they appear on national platforms. National sites like HomeFinder or RentToOwnLabs sometimes have Princeton inventory, but the selection is thin and the listings are often outdated. By the time you see them online, the deal may already be under contract. Local brokers and direct seller contacts move faster and provide more accurate information about the actual status of a property.