What Recourse Actually Means In Practice
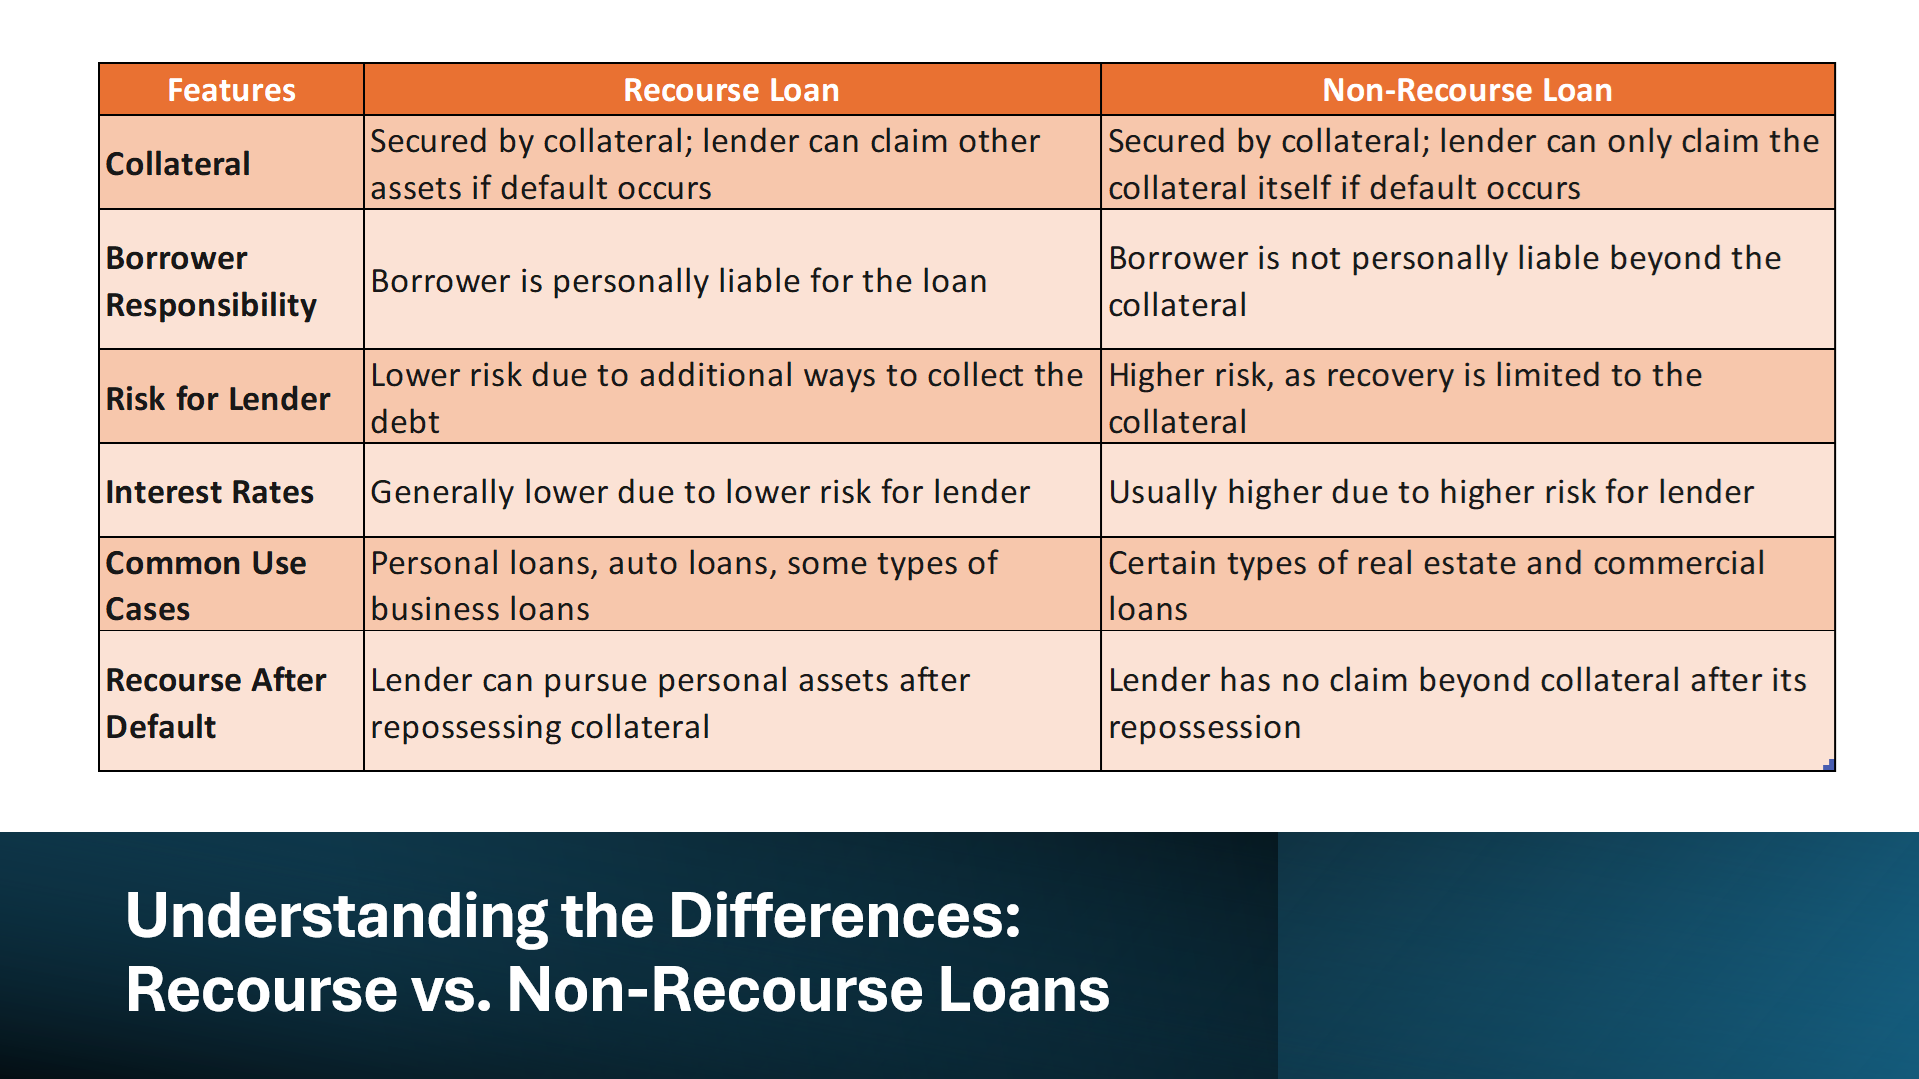
When people talk about recourse, they usually mean the legal right to seek a remedy or compensation after something goes wrong. In contract law, it is the mechanism that lets you force the other party to answer for their failures. Without it, a contract is just a piece of paper. With it, you have leverage. That is the basic idea. The details are where most people get tripped up. Recourse has a few distinct layers depending on the context. In lending, it means whether you can go after more than just the collateral when a borrower defaults. A non-recourse loan limits the lender to the asset. A full recourse loan lets them chase your other assets, your wages, anything. In commercial contracts, it refers to the right to demand performance or financial compensation from a party that breached. In securities, recourse provisions determine who bears the loss when underlying assets in a trust fail. The common thread is always the same: who picks up the tab when things break. I learned this the hard way about three years ago. I was reviewing a vendor agreement where the liability clause mentioned "recourse" without specifying whether it was limited or unlimited. My counterparty had structured it as a non-recourse arrangement, meaning if they delivered defective product, I could only claim the contract price back. I would have walked away with nothing for the damages my business suffered because of the failure. I caught it during a routine review. We renegotiated the clause to full recourse before signing. That one clause ended up protecting roughly two hundred thousand dollars in potential losses.
Here is a straightforward example. You hire a contractor to rebuild a deck. They use substandard materials and the deck collapses three months later. Your recourse is the legal pathway to recover costs. That could mean suing for breach of contract, filing a claim against their bond or insurance, or pursuing small claims court depending on the dollar amount. The existence of recourse is what separates a binding agreement from a handshake. Another example comes from commercial leases. A tenant signs a triple net lease where the landlord guarantees the building's structural integrity. If the roof fails and causes damage to the tenant's inventory, the tenant's recourse is to demand the landlord cover those losses as specified in the lease terms. Without a recourse provision, the tenant would have no contractual basis to make that claim and would absorb the cost entirely. Now let me tell you something most people miss about recourse. It is not automatic. Having a legal right to recourse does not mean you can simply exercise it on command. You have to structure it properly in the contract from the start. Courts will not read recourse into an agreement that is silent on the matter. If your contract does not explicitly state the scope of recourse, you are likely working with whatever the default state law provides, and default provisions are often weak and unpredictable.
The second thing people overlook is the difference between recourse and indemnification. They are related but distinct. Recourse is your right to demand performance or compensation. Indemnification is the obligation of one party to cover losses suffered by another. A well drafted contract includes both. Recourse gives you the tool. Indemnification tells you who pays. If you only have recourse without indemnification, you still have to prove fault and damages through litigation before you see any money. There is a practical workaround for the non-recourse trap that I use when negotiating contracts. I always insert a residual recourse clause that survives termination. Many agreements limit recourse to the term of the contract or to a narrow window after it ends. If a defect surfaces six months later, you might find your recourse period has expired. A survival clause extending recourse for two to three years after contract termination covers that gap. I added one to a software licensing deal last year and it saved us when a critical bug emerged after the renewal date. The vendor had already shifted to a new product line and was uncooperative, but the surviving recourse clause gave us leverage to get a implemented within two weeks. Where recourse falls apart is in bankruptcy. If the party you are pursuing files for Chapter 7 or Chapter 11, your recourse becomes theoretical until the court processes your claim. I have seen full recourse clauses reduced to pennies on the dollar because the debtor had no attachable assets. In those situations, the practical move is to secure your recourse upfront through payment bonds, letters of credit, or personal guarantees rather than relying on the contract clause after the fact. A recourse right against an insolvent entity is worth less than the paper it is written on.
Get the Full Details

Another limitation you should know about is the cost of exercising recourse. Filing a breach of contract suit in federal court typically runs between fifteen thousand and forty thousand dollars before you even get to discovery. For smaller disputes under fifty thousand dollars, the cost of enforcing your recourse often exceeds the potential recovery. In those cases, mediation or arbitration clauses embedded in the contract are far more practical. I recommend capping arbitration fees at a specific amount in the contract so they cannot balloon out of control. If you want to actually protect yourself, start with the contract language. Specify whether recourse is limited or full. Define the scope of recoverable damages including consequential and incidental damages if they matter to your situation. Set clear timelines for exercising recourse after a breach occurs. Include a survival clause. And if the counterparty has weak financials, require collateral or a guarantee before you sign anything.