Understanding Reason Code Pr177: What Actually Happens When You See It
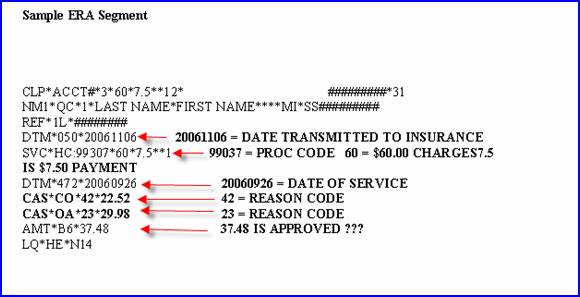
Reason Code Pr177 shows up when a transaction gets declined during the authorization stage, and it has nothing to do with insufficient funds or a lost card. It's one of those codes that sounds simple on the surface but actually masks several different underlying conditions depending on the processor, the merchant category, and the issuing bank's risk rules. I've seen it trip people up more than once because most guides just tell you to "try a different card" without explaining why it happened in the first place. At its core, Pr177 is an issuer-side decline code that indicates the cardholder's bank has blocked the transaction based on internal risk criteria or account restrictions. The reason isn't always clear from the code itself. Different payment networks and acquiring banks sometimes map Pr177 to slightly different error conditions, which is part of why it feels so frustrating to troubleshoot. The most common trigger is a mismatch between the billing address on file and the address entered during checkout. Some issuers treat this as a security check rather than a hard failure, while others decline immediately without warning. Another frequent cause is that the card has hit a daily or per-transaction limit set by the cardholder or the issuing bank. This is especially common with virtual cards or corporate payment cards that come with tight spending caps.
There's also the scenario where the issuer's fraud detection system flags the transaction as suspicious based on patterns like unusual purchase location, high-value items, or multiple rapid-fire attempts. In those cases Pr177 is essentially a soft hold rather than a permanent block. The cardholder might not even realize their card was flagged until they see the decline happen.
How to Troubleshoot Pr177 Without Wasting Time
When I'm dealing with a Pr177 decline, the first thing I check is whether the billing address matches exactly what's registered with the card issuer. Even a minor difference like "St" versus "Street" can trigger this code on certain processors. I then verify the transaction amount against any known limits on the card. If this is a recurring payment or subscription, I check whether the card has a per-authorization cap that the new charge exceeds. Here's a specific edge case I ran into last year that I still think about. A merchant was processing recurring subscription payments and suddenly started seeing Pr177 on about 12 percent of their attempts. The cards looked fine, the addresses matched, and the amounts were well under any reasonable limit. What was actually happening was that the merchant's payment gateway had recently been migrated to a new processor, and the new system was sending the merchant category code in a slightly different format. The issuing banks' fraud systems interpreted the changed MCC format as anomalous and started declining those transactions en masse. The fix wasn't on the customer side at all. It required the merchant to update their gateway configuration to ensure the MCC was being passed in the format the new processor expected. That took about three hours of back-and-forth with the gateway provider, but once it was corrected the decline rate dropped to near zero. Another practical step is to ask the cardholder to contact their bank directly. Sometimes the block is placed intentionally by the cardholder through their banking app's security settings. A cardholder might have set a temporary spending pause or a geofence restriction without realizing it would affect an online purchase. I've had situations where the same card works perfectly after the cardholder calls their bank and confirms the transaction is legitimate, lifting whatever temporary hold was in place.
Get the Full Details

Advanced Nuances Most People Miss
One counter-intuitive thing about Pr177 is that it doesn't always mean the card is dead. In many cases the decline is specific to that particular merchant or transaction type. A cardholder might be able to use the same card at a different merchant without any issues. This happens because fraud filters are often tuned to specific risk profiles per merchant category. If a card has a history of being used at grocery stores and gas stations, a sudden high-value electronics purchase might trigger a Pr177 decline even though the card is otherwise perfectly healthy. Another thing that catches people off guard is the timing of the decline. Some issuers don't apply risk checks until a transaction reaches a certain dollar threshold or occurs outside the cardholder's typical spending window. A customer making a purchase at 3 AM local time might get declined with Pr177 while the same purchase at 2 PM goes through without issue. This isn't arbitrary. The issuer's algorithms weight off-hours transactions higher on the risk scale, especially for amounts above the cardholder's historical average.
When Pr177 Actually Means Something Serious
I should be straight about the scenarios where Pr177 signals a real problem. If a cardholder is getting repeated Pr177 declines across multiple merchants and transaction types, the most likely explanation is that the issuing bank has placed a broader hold on the account. This could be due to suspected compromise, repeated failed authentication attempts, or the account flagging in a shared fraud database. In these cases telling the customer to "try again" won't help and might actually make things worse by triggering additional fraud alerts. There's also the possibility that the card has expired or been replaced and the updated card details haven't been propagated to the payment network yet. This is rare but it does happen, especially with corporate or insured cards where the replacement process can take several business days. The old card number is still active in some systems but flagged in others, creating an inconsistent state that surfaces as Pr177.
What Doesn't Work and What Actually Does
Asking the customer to reload the page and try again is one of the least helpful things you can do for Pr177. Unless the decline was caused by a transient network glitch, which is uncommon for this particular code, retrying the same transaction will produce the same result. The same goes for suggesting the customer delete and reinstall whatever app they're using. These suggestions don't address the actual cause. What tends to work better is a structured approach: verify the billing address and card details first, then check for known limits or restrictions, then have the cardholder contact their bank if the first two steps don't resolve it. For merchants dealing with a spike in Pr177 declines, the priority should be checking gateway and processor configurations, especially after any recent changes to the payment stack. Logging the decline responses with full details including the exact error message from the issuer, the MCC being sent, and the transaction amount can reveal patterns that point directly to the root cause. Some payment platforms offer alternative verification methods like 3D Secure or tokenized checkout that can sometimes bypass the conditions that trigger Pr177. These aren't guaranteed solutions, but they're worth testing if you're seeing a high volume of these declines and the basic troubleshooting steps haven't helped. The added verification step can satisfy the issuer's risk requirements in a way that a plain card-not-present transaction doesn't.
The Practical Bottom Line
Reason Code Pr177 is a broad-spectrum decline indicator that requires actual investigation rather than a generic fix. The code tells you the issuer blocked the transaction but rarely explains why in a way that's immediately actionable. The most effective approach combines checking the obvious things first like address mismatches and spending limits with more careful analysis of transaction patterns and gateway configurations if the simple fixes don't clear it up. Most Pr177 declines get resolved within a few minutes once you know which direction to look, but the ones that don't usually involve a configuration issue on the merchant side or a hold placed by the issuing bank that only the cardholder can lift directly.