Setting Up a Minor Account With Royal Bank of Scotland
I spent about three hours trying to sort out a 14-year-old's first banking account with RBS last year. What seemed like it should take twenty minutes turned into a back-and-forth that involved two phone calls, a printed form, and some head-scratching over what counts as acceptable proof of address for a kid who technically lives with their parents but goes to a boarding school forty miles away. That's the first thing you need to understand about RBS minors accounts: the process is straightforward until it isn't, and the edge cases are where people get stuck. RBS (now operating under the NatWest Group banner) offers a Junior ISA and a standard youth current account for children aged 11 to 17. The youth current account is the more commonly used product. It comes with a debit card, mobile banking access through the NatWest app, and importantly, no monthly fees. The Junior ISA, launched more recently, is a tax-efficient savings vehicle that allows up to £9,000 in contributions per tax year and grows free from income and capital gains tax. The practical difference between the two matters more than most parents realize. A youth current account gives the child spending autonomy with parental oversight built in. The Junior ISA is purely savings-oriented and the money is locked in until age 18. I've seen families set up both simultaneously, which is perfectly fine, but it's worth being clear about what each one is actually for before you open them.
How the Account Actually Works Day to Day
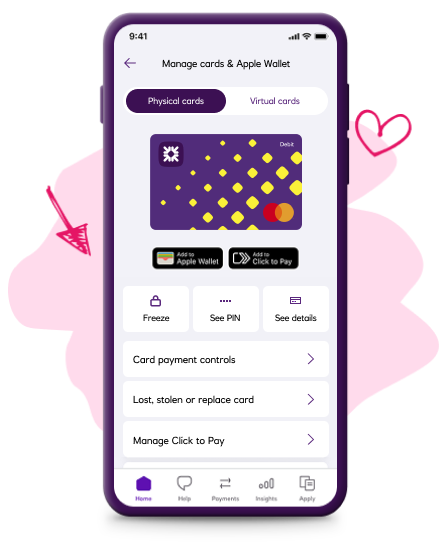
When the account is open, the parent or guardian is the Account Holder of Record. The child is the named account user. This distinction is important because it determines who can override decisions, who gets the statements, and who carries legal responsibility. If your 16-year-old maxes out their spending on things they shouldn't be buying, it's you who answers to the bank, not them. The NatWest app handles the account management. Parents can set up spending notifications, view transaction history in real time, and set daily withdrawal limits through the app's controls. The child gets their own login and can see their own balance and transactions independently. I found this dual-view setup genuinely useful when my nephew was learning to budget. He could see his balance without asking, and I got push notifications on anything above £20, which caught a few questionable attempts at online purchases before they went through. The debit card that comes with the account is a standard Visa debit. It works everywhere regular cards work. There are no special restrictions on where it can be used, which is both a benefit and a risk. Unlike some competitor products that block gambling or high-risk merchants by default, RBS relies on parental monitoring rather than category-level restrictions. That means you actually have to use the notification settings. I learned that the hard way when I missed a £45 charge at a betting site that slipped through on a Friday evening.
What You Need to Open the Account
The requirements are relatively light compared to adult account applications. The child needs proof of identity, usually a passport or birth certificate. The parent or guardian needs proof of identity and address. That's it. There's no credit check involved because the account is in the adult's name with the child as the user. The application can be started online but often requires a follow-up call or branch visit, especially if the child is under 16. I've opened accounts entirely over the phone and others where we had to go to a branch. The branch route tends to be slower but more thorough. Online can be done in about 15 minutes if you have all the documents scanned and ready, but the system will sometimes flag the application for manual review, which adds a few days to the process. One thing that catches people out: the child must be a UK resident. This sounds obvious until you're dealing with families who split time between the UK and another country, or children attending school abroad part of the year. RBS's terms require the child to live at a UK address for the majority of the tax year. If that's unclear in your situation, calling before you apply saves a lot of frustration.
Get the Full Details
The Junior ISA Side of Things
The Junior ISA operates separately from the current account, though you can link them for convenience. Contributions come from post-tax income, which is the standard UK ISA structure, but the growth and withdrawal at 18 are tax-free. This is a significant advantage compared to a standard savings account where interest is subject to the Personal Savings Allowance. For 2024 to 2025, the annual subscription limit is £9,000. Multiple people can contribute — parents, grandparents, anyone — as long as the total doesn't exceed the limit. The money belongs to the child but is held in trust until they turn 18, at which point it becomes theirs outright. There is no early withdrawal option, and unlike a regular savings account, you can't touch this money for tuition or anything else before the birthday. I recommended the Junior ISA to a colleague whose daughter was eight at the time. She was saving for university and wanted to start early. Nine years later, with consistent annual contributions and compound growth, the account had roughly doubled from what she put in. That's not a guarantee, but it shows what the structure can do when left alone. The counter-intuitive part is that leaving it alone is the hardest thing to do. The account is boring. It does nothing exciting. But it does exactly what it's supposed to do, which is grow quietly while everyone else is busy checking rates and moving money around for negligible gains.
Common Problems and Workarounds
Here's a specific edge case I ran into that the help pages don't really cover. If the child changes schools and their address changes mid-account, RBS treats this differently depending on whether it's still within the UK. An internal address change is straightforward — update it through the app or call center. But if the family moves abroad, the account typically needs to be closed and the funds transferred out. The child cannot maintain an RBS youth account as a non-UK resident. Another issue that comes up repeatedly is the link between the child's account and the parent's main account. Some parents expect automatic transfers or direct debits to work seamlessly between the two, and they usually do. But the reverse — the child initiating a payment to the parent — doesn't always go through the same channels. I had a situation where a 15-year-old tried to pay their parents back for groceries using the app's "pay someone" feature, and the transaction failed because the parent's main NatWest account wasn't registered as a contact in the system. Adding the parent as a payee resolved it, but it required a phone call to set up. There's also the matter of joint accounts. RBS does not offer joint youth accounts in the traditional sense. If two children in the same family need accounts, they each get their own. There is no shared account structure like you might find with some building societies or smaller banks. This is a limitation if your goal is to teach sibling cooperation around a shared pot of money, but it's also simpler from an administrative standpoint and reduces the risk of one child draining the other's funds.
What the Account Doesn't Do
Be honest about this upfront. A youth account with RBS is not going to transform your child's financial future on its own. It's a tool, nothing more. The actual benefit comes from how consistently you use it alongside conversations about money. I've seen too many parents open the account, set it and forget it, and then act surprised when the teenager treats it like an ATM with no consequences attached. The app's notification system is only as good as the settings you configure. Default settings are minimal. You need to actively choose to turn on spending alerts, low balance warnings, and large transaction notifications. If you don't, you're flying blind until you see the statement at the end of the month. Setting these up takes about five minutes and prevents most common problems. Another limitation: the youth account has no overdraft facility. This is actually a good thing for most families, but it means if the child needs to make a purchase that exceeds their balance, the transaction simply declines. There's no safety net. Some parents see this as frustrating; most will agree it's a feature, not a bug, at this age.
Alternatives Worth Considering
If RBS isn't the right fit, there are other options. Monzo's Under 18s account is highly regarded for its interface and parental controls, though it lacks the Junior ISA integration. Halifax offers a similar youth product with a slightly more generous approach to joint accounts for siblings. For pure savings focus, the First Direct Junior ISA competes directly with RBS's offering and sometimes has promotional rates on the cash component. The choice between these largely comes down to whether you already bank with the provider, how much you value mobile app quality, and whether you want an integrated savings-and-spending ecosystem or separate accounts for different purposes. RBS wins on integration if you're already a customer. It doesn't lead on app UX compared to digital-only alternatives. Both observations are straight, not promotional.
Bottom Line
An RBS youth account or Junior ISA is a functional, no-frills entry point into formal banking for young people. The process to open one is generally quick unless your circumstances fall outside the standard template. The real work happens after the account is live, in the ongoing management and the conversations that accompany it. The product won't do that for you, and no product will. What it does provide is a legitimate financial identity for the child, a structure for managing money, and — in the case of the Junior ISA — a tax-advantaged container that benefits from time. Start early if you can. Set the notifications properly. Don't assume the account manages itself. And don't confuse having the account with teaching the habits that make the account useful.