What The Raymour And Flanigan Credit Card Actually Gets You
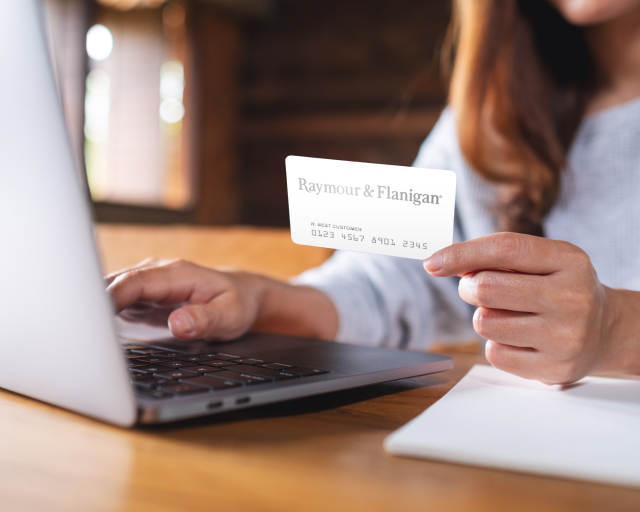
I've been helping people figure out store credit cards for years now, and honestly, most of them are mediocre at best. The Raymour And Flanigan one is borderline worth the application, which surprises me since most of these retail cards are basically debt traps wrapped in a discount brochure. The card gives you a 25% discount on regular-priced furniture and sleep products when you use it at checkout. That's the headline number and it's accurate. There's also occasional financing promotions that run through their website, typically 0% interest for 60 months on purchases above a certain threshold. The fine print on those matters more than people realize. Here's the thing nobody tells you about the 25% discount. It only applies to regular-priced items. If something is already marked down or part of a clearance event, the card doesn't stack on top. I learned this the hard way during a kitchen cabinet project last fall. I thought I was getting 25% off a 30% off sale. I wasn't. The discount applied to the original price before the sale percentage, which actually works in your favor mathematically, but the checkout system didn't make that obvious at all. I had to call customer service and get a repricing adjustment. Took about 40 minutes on hold but they fixed it.
How To Apply And What To Expect
Applications happen online at the Raymour And Flanigan website or in-store. The in-store process is slightly faster because a representative can walk you through it on a tablet. Online applications sometimes take longer to process since they route through a third-party lender initially. Approval isn't guaranteed, and the credit check is a hard pull. If you're already working on improving your credit score for something bigger like a mortgage, maybe hold off on this for a few months. One hard inquiry won't tank your score, but multiple ones within a short window definitely add up. Once approved, the physical card arrives in about 7 to 10 business days. Some people report faster delivery, but that's the standard wait. There's no instant card option at Raymour And Flanigan like some other retailers offer, so you can't walk out with immediate access even after approval.
The Financing Promotions
The 0% financing deals are the real value driver here, but they come with strings. The most common promotion is 0% for 60 months on purchases of $2,499 or more. If you don't pay it off by the end of the term, deferred interest kicks in retroactively to the original purchase date. That means you could owe a massive interest charge all at once even if you've been making perfect payments for 59 months and then slip up in month 60. I've seen people get burned by this exact scenario. You set up autopay, everything looks fine, and then a bank error or a forgotten account change messes up a single payment. Suddenly you're looking at thousands in deferred interest. Set calendar reminders for the final payment deadline and then some buffer time after. There are also shorter-term promos like 0% for 18 months on smaller purchases. These have lower minimums and significantly less risk of deferred interest piling up. If you're financing something under $1,500, look for those smaller windows instead of defaulting to the big 60-month option.
Get the Full Details

What The Card Doesn't Cover
Services like installation, removal of old furniture, and white glove delivery aren't discounted. The 25% applies strictly to the product price. I've seen people try to bundle installation into their purchase to get the discount to apply to the total, but the system separates product from service charges automatically. You can't game it unless you structure the order very specifically before checkout. Gift cards and merchandise credits purchased with the card don't earn any additional rewards. The card isn't a rewards card in the traditional sense. There's no cash back, no points, no tier system. It's purely a discount and financing tool. If you're shopping across multiple furniture retailers and want cross-store benefits, this card does nothing for you outside the Raymour and Flanigan ecosystem.
Annual Fee and Costs
There is no annual fee. That's actually unusual for store cards and one reason the product exists at all. Most retail cards charge somewhere between $0 and $30 annually. Raymour and Flanigan keeps it free, probably to encourage repeat purchases rather than lock in fee revenue. The interest rate after any promotional period ends is variable and runs quite high. I'm talking subprime territory rates that can exceed 25% APR depending on your credit profile. This is the business model. They make money on the people who carry balances or miss the financing window.
Practical Strategy
Use the card only when you can pay the full balance within the promotional window. Set up payment reminders at least 30 days before the promo ends. If your budget is tight, the 25% discount on a single large purchase might be more valuable than financing anything at all. A one-time 25% off a $3,000 sofa saves you $750, which easily covers interest charges you'd pay on a carry balance over a year. Another angle that works better than most people realize: combine the card with email-only promo codes. Raymour and Flanigan sends out additional coupon codes periodically to subscribers. Those codes often stack with the card discount on regular-priced items, giving you something closer to 30 to 35% off total. The site will let you apply both at checkout without conflict.

Bottom Line
The card is worth applying for if you're planning a substantial furniture purchase within the next six months and have the discipline to pay it off fast. It's not worth it if you're looking for long-term rewards or plan to carry a balance. The deferred interest structure alone makes it dangerous for people who already struggle with credit card management. I opened one during a renovation two years ago. Used it for a sectional and dining set totaling about $4,200. Paid it off in 14 months through the promo period. Saved roughly $1,050 from the discount alone with zero interest cost. No regrets on that decision.