Getting Money When Everyone Else Is Doing The Same Thing
Raising capital in a saturated market is less about your pitch deck and more about making investors feel like they are seeing something genuinely novel while also feeling safe enough to sign a check. I have watched startups with better product-market fit burn through three funding rounds and still be irrelevant, while some obscure competitor pulled in eight figures by simply naming the right problems at the right time. The mechanics are standard. You need traction metrics, a clear use of proceeds, and a cap table that does not look like a desperate plea. What changes in competitive environments is the timing of your narrative. Investors in crowded spaces have heard every version of disruption. Your guide to raising needs to account for their fatigue before they even open your document. I spent six months trying to raise seed in the payments space back in 2019. Every investor asked the same three questions. I learned to answer them in the first forty seconds and stop talking about anything else. That alone cut my average meeting length from forty five minutes down to twelve. Investors appreciated the efficiency. More importantly, they remembered me because I was the only founder who treated their time like it had value.
The Structural Reality Of Competitive Capital Raising
Most founders treat fundraising as a linear process. They build a deck, send it out, and wait for replies. This approach fails systematically in competitive markets because you are competing for attention against dozens of other companies with similar profiles. The market has already aggregated comparable data points. Investors make quick pattern-matching decisions before reading a single line of your materials. Your actual advantage comes from controlling the frame. Frame means the specific lens through which an investor evaluates your opportunity. In a crowded vertical, the wrong frame makes you a commodity. The right frame makes you the only rational choice. I worked with a company that was raising in the logistics technology space. Their original frame was automation and cost reduction. Every other logistics startup used the same frame. We switched theirs to regulatory arbitrage driven by new state-level compliance mandates that hit eighteen months out. The frame made the timing urgent. It made their product feel inevitable rather than optional. They closed their round in eleven weeks instead of the estimated seven months.
Metrics That Actually Move Capital
Burn rate, runway, and ARR are table stakes. Every investor reviews these whether you mention them or not. What separates funded companies from unfunded ones in competitive spaces is the second order metric. This is the number that proves your business model has teeth beyond the surface level. In our experience, net dollar retention above one hundred thirty percent paired with a cohort analysis showing month three revenue doubling matters more than any headline growth figure. I have seen investors reject clean decks because the retention cohort chart looked like a flat line after month four. The revenue looked impressive on paper. The behavior told a different story. Another counter-intuitive point that beginners consistently miss. Lower customer acquisition cost is not always better than higher acquisition cost. If your ACP is low because you are targeting tiny accounts that will never scale, a higher ACP with concentrated enterprise buyers can actually make your unit economics look superior to sophisticated investors. The math flips depending on lifetime value trajectory. Two companies with identical CAC can present wildly different investment cases depending on LTV shape.
Get the Full Details
The Document Stack That Actually Works
You need a data room. Standard. But the specific documents matter more than the volume. Investors in competitive markets skim aggressively. They look for red flags in exactly three places first. The cap table. Any anomalies here like odd vesting schedules or unclear options pools trigger immediate skepticism. Keep it clean. Use standard four year vesting with a one year cliff. Deviations require written explanations in the data room itself. I have seen rounds stall for weeks because someone forgot to update a prior employee option grant. The diligence team found it and assumed the founder did not know their own company structure. That perception is extremely costly to repair. The financial model. Do not send a spreadsheet with a million assumptions. Send a three statement model with clear section breaks and a assumptions page that lists every variable a reasonable person would question. If you are projecting sixty percent gross margins in year three, explain the path there. Investors do not want to guess. They want to stress test your logic and find where you are wrong before they do it themselves.
The competitive landscape slide. This is where most founders fail. Do not include a grid with four by four boxes listing every competitor. No one reads these. Instead, map your position using a single axis that matters most to your specific market. Price versus performance. Speed versus accuracy. Vertical depth versus horizontal breadth. Pick the axis where you have a defensible edge and build the narrative around it. Make the chart tell a story without requiring explanation.
When Raising Fails And What To Do Instead
Capital raising in competitive markets has hard failure modes. The most common one is timing misalignment. You are raising when the macro environment has shifted against your sector. No amount of preparation overcomes a market that has turned hostile toward your category. I watched a fintech company miss two funding windows in 2022 because interest rate policy changed faster than their pivot strategy could adapt. They tried to reframe around stability during a volatility boom. The narrative contradiction was obvious to every investor. When framing fails and traditional venture capital is unavailable, bootstrapping becomes a viable alternative in specific scenarios. If your business has strong cash flow generation from day one and does not require massive upfront R&D, self funding preserves equity and gives you leverage in future negotiations. Revenue backed credit lines from lenders like Stripe or Circle can bridge gaps that would otherwise force a down round. These instruments exist specifically for companies that can show predictable monthly revenue patterns. Another often overlooked path is strategic corporate investment. Large incumbents in your space sometimes invest in smaller competitors because acquisition is cheaper than building internally. This route requires different negotiation dynamics. Corporate investors will demand board seats, information rights, and sometimes exclusivity clauses that limit your ability to work with competitors. The capital is real but the constraints are substantial. Proceed only if the strategic alignment justifies the loss of optionality.
Practical Execution Details
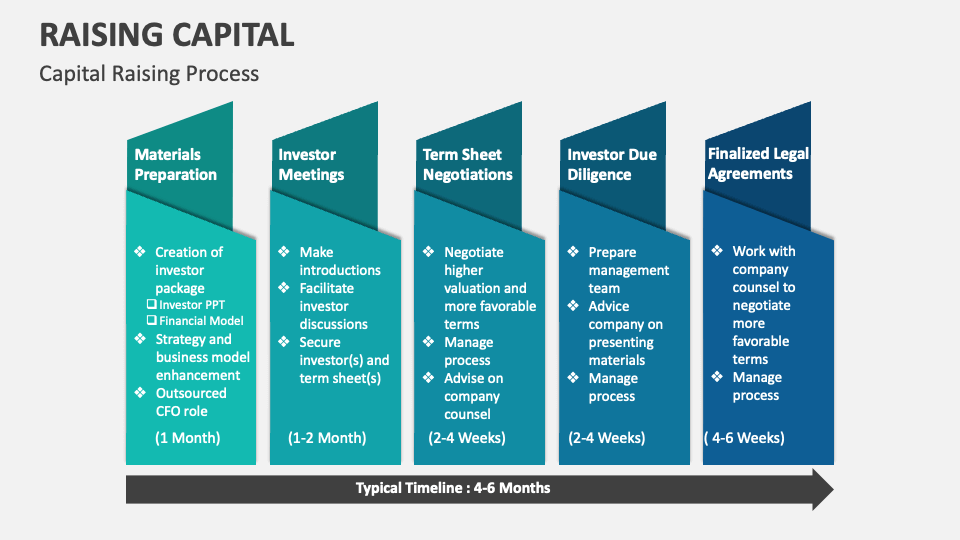
Set up your data room before you need it. Not when the first serious inquiry comes in. Google Drive works fine. We prefer Google Workspace for its permission granularity. Set individual file access controls. Do not give blanket edit permissions to anyone outside your core team. I once reviewed a data room where a marketing intern had comment access to the financial model. The comments contained assumptions that contradicted what the founder told the lead investor. The inconsistency killed the deal twenty minutes into diligence. Track every conversation. Use a simple CRM. HubSpot free tier handles this adequately. Record what investors asked, what concerns came up, and what objections were raised. Pattern recognition across meetings reveals which parts of your narrative resonate and which parts consistently confuse people. You should be able to identify your three most common objection within five investor meetings. Addressing those objections proactively in subsequent pitches compounds faster than adjusting your product roadmap. Term sheet negotiation in competitive markets tends to favor investors because there are always other founders seeking capital. Understand which terms are non negotiable and which are decorative. Liquidation preferences above one times are aggressive but standard in hot sectors. Conversion rights and participation caps matter more than most founders realize. A participating preferred share can severely dilute common equity during a modest exit. I have seen founders accept slightly lower valuations to avoid participation ratchets. The math favors the lower valuation in most realistic exit scenarios.
What Nobody Tells You About Follow On Rounds
Raising your first round is harder than raising your second, but most founders underestimate how much the dynamic shifts. Post seed, investors evaluate you against other portfolio companies from previous rounds. Your traction relative to benchmarks matters more than absolute numbers. If your closest comparable raised at twice your valuation last year, you need to explain the variance or accept the discount. Reference letters from existing investors carry enormous weight. A single strong endorsement from a respected fund can offset weaker metrics. Cultivate these relationships before you need them. Regular updates matter. Monthly one page summaries keep your investor network warm. The summary should include three wins, three challenges, and one specific ask or decision point. Nothing else. Investors scan these quickly. Structure for scanning. The hardest truth about raising capital in highly competitive markets is that readiness is often indistinguishable from luck in hindsight. Two companies with identical metrics can raise at vastly different valuations based on which investor happens to be deploying capital that quarter. Preparation does not guarantee outcome. It only guarantees you are not leaving anything on the table through ignorance of process. The companies that consistently raise well are the ones that treat fundraising as a operational discipline rather than an episodic event.