The Practical Reality of Getting and Using a Rabobank Credit Card in the Netherlands
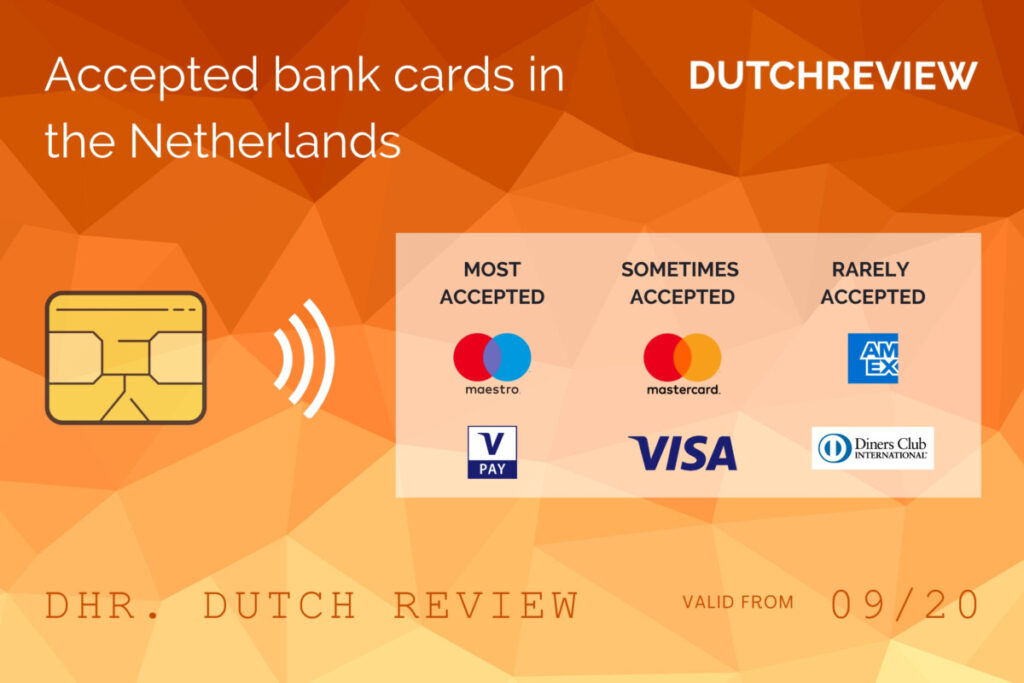
Rabobank is one of the larger banking cooperatives in the Netherlands, and they offer credit cards alongside their more common pinpas debit products. If you are moving here or already banking with them, the credit card application process is straightforward but has a few things that will catch you off guard if you come from a country where credit cards are the default payment method. Most Dutch residents use their pinpas for everything daily, so treating a Rabobank credit card like your primary wallet card is not really how it works over here. When you apply through Rabobank, you typically have access to either a Visa or a Mastercard credit card depending on which product tier you qualify for. The application happens online through the Rabobank app or internet banking once you already have an account, so you cannot apply for a credit card if you do not first establish a current account. I learned this the hard way when I tried to pre-apply before my banking relationship was fully set up and got bounced back twice. The approval process usually takes a few business days. Rabobank runs a BKR registration check, which is the Dutch credit bureau, and if you have existing debts or payment delays on file there, your chances drop significantly. This is different from the UK or US where you might get approved based purely on income and a quick soft pull. The BKR check is thorough and it stays on record for four years after the decision.
Once approved, the card arrives by post within about five working days. You activate it through the app and set your PIN. Unlike American debit cards where you swipe or insert and sign, the Dutch system is almost entirely chip-and-PIN, and Rabobank credit cards are no exception. You use them at terminals the same way you would use your pinpas, but the billing cycle works on a true credit basis with a monthly statement.
What Actually Works and What Does Not
Here is the thing nobody tells you about using a Rabobank credit card at Dutch gas stations. Many self-service pumps only accept pinpas. I spent twenty minutes at a Shell station outside Utrecht trying to pay at the pump with my credit card before realizing I needed to go inside and use the pinpas terminal. Some newer stations have upgraded, but do not assume yours will work. This is one of those small daily friction points that makes people here keep their debit card on their keyring and treat the credit card as a backup. Online purchases work fine and that is actually where the card shines. Subscription services, booking flights, and larger retail purchases are the use cases that make sense. Most Dutch online retailers accept Visa and Mastercard without issue. I use mine for groceries on marketplaces and for train tickets through NS, and the fraud protection is solid compared to pinpas, which has tighter per-transaction limits on contactless spending.
Get the Full Details

The Fees and Limits You Need to Know
Rabobank charges an annual fee for most of their credit card products, which typically runs between forty and eighty euros depending on the card level. Some premium tiers offer travel insurance and lounge access that may justify the cost if you travel internationally several times a year. For a card you only use locally, the annual fee eats into any rewards you might earn. The credit limit is set during approval and is usually conservative for Dutch residents who do not have an established credit history. I have seen limits range from two thousand to five thousand euros for standard accounts. If you need more, you can request an increase through the app, but each request triggers another BKR check. Doing this too frequently will temporarily lower your credit score in the bureau's eyes, and a single request can take three to five business days to process. Foreign transaction fees apply when you use the card outside the eurozone. This is where many people get surprised. Even though the Netherlands is in the euro, traveling to the UK or Switzerland with a Rabobank credit card means a markup fee on top of the exchange rate. I recently calculated this on a trip to Copenhagen and found the effective cost was roughly 1.5 percent above the base exchange rate. For regular travelers, this adds up faster than you would expect.
How to Apply and Set It Up Properly
You need an active Rabobank current account with at least six months of transaction history. Log into the app, navigate to the credit cards section, and fill out the application. You will declare your income, monthly expenses, and current debts. The system evaluates this in real time for most straightforward cases, and you get a decision within minutes. If the system flags something, a human reviewer takes over and it can stretch to a week. After you receive the physical card, enable it in the app and verify that your contact details are current. This sounds obvious, but I once missed an important payment alert because my address had not been updated after a move, and the statement went to the old mailbox. Late payments on a credit card hit your BKR record immediately, and a single missed payment can reduce your credit score by thirty to fifty points depending on your overall profile. Set up automatic payment for at least the minimum amount due. Rabobank allows you to link a separate bank account or use the balance from your current account. Automatic payment prevents accidental late fees and protects your credit rating without requiring you to remember due dates manually.
Where This Actually Fails You
Here is the blunt part. A Rabobank credit card is not going to replace your pinpas for everyday Dutch spending. It is heavier, has higher fees, and offers weaker contactless limits than your debit card. Most convenience stores, bakeries, and small cafes will happily take your pinpas and will sometimes refuse a credit card outright because the merchant fees are higher for them. You will encounter this regularly and you need to carry both. If you are a resident without strong income documentation or with a thin credit file, the approval odds are genuinely lower than in markets with more relaxed lending standards. The bank does offer a secured credit card product in some cases, but the limits are low and the terms are not favorable. For people in that situation, building credit history through a pinpas with responsible usage and paying all bills on time is usually the faster path before a credit card application makes sense. Rabobank does not currently offer a no-annual-fee credit card that includes meaningful cashback or rewards for the Dutch market. Their rewards programs exist but the point values are modest compared to premium cards in Germany or the UK. If your goal is maximum return on spending, you are likely better off looking at specialized fintech options or foreign-issued cards if you have access to another EU banking relationship. For most people who already bank with Rabobank and want the convenience of a proper credit card for travel and larger purchases, it is a reasonable secondary card. It is not a must-have, and it is not a substitute for good everyday banking habits with your pinpas.