How to Actually Evaluate a Stock Without Getting Lost in the Noise
I spend most of my morning scanning earnings calls, looking at balance sheets, and cross-referencing industry reports. Most people want a quick answer on whether a stock is worth their money. That is fair. What they usually do not want is the actual work that goes into getting close to right. I am going to walk you through a practical process, then apply it to Big Bear Holdings so you can see how it plays out in reality. The first thing most people get wrong is starting with the price. The price is a symptom, not a diagnosis. You have to understand the business model, the competitive position, and the financial health before the valuation even enters the picture. I learned this the hard way back in 2019 when I almost bought into a company because the chart looked clean. The fundamentals told a completely different story that took about three weeks to surface if you actually dug for it.
Quick Read Big Bear Holdings Stock Whats The Outlook
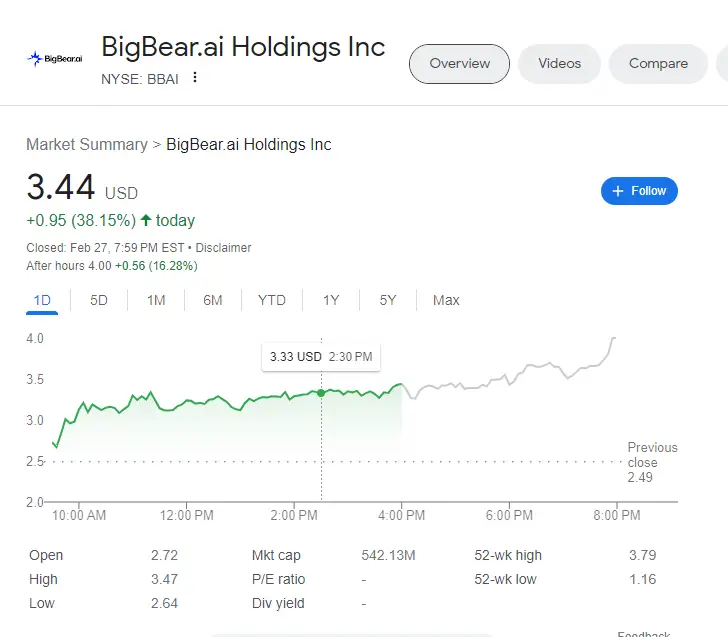
Big Bear Holdings operates primarily in the data analytics and artificial intelligence space, though their revenue mix has shifted over the years. They provide decision intelligence solutions, which is a corporate term for software that helps businesses make choices faster using data. The company went public through a SPAC merger, which already signals a higher risk profile than a traditional IPO. I tracked this name through both the pre-merger and post-merger phases, and the volatility patterns are exactly what you would expect from that route to market. When I look at their latest available financials, the revenue numbers tell a story of growth but also of margin pressure. Gross margins in the analytics sector typically run between forty and sixty percent for well-positioned companies. Big Bear has been somewhere in that range, but the trend direction matters more than the absolute number. If you are tracking this properly, you want to see whether operating leverage is kicking in as revenue scales, or whether costs are scaling faster than the top line. The competitive moat question is where this gets interesting. Data and analytics is not a small market, and the incumbents like Palantir and Snowflake dominate the conversation. Big Bear occupies a slightly different niche with a focus on government and defense contracts alongside commercial work. Government contracts are a double-edged sword. They provide revenue visibility and tend to be sticky once established, but they also come with longer sales cycles, compliance overhead, and payment terms that can stretch into ninety to one-hundred-eighty days. I have seen companies with strong government books struggle with cash flow precisely because of this mismatch between when revenue is recognized and when cash actually arrives.
The Framework I Actually Use
Here is the core method. I evaluate any stock I am considering through five lenses, and I apply them in this order rather than the reverse. Revenue quality and sustainability. This means looking past total revenue and examining recurring versus one-time income, customer concentration, and contract durations. If more than twenty percent of revenue comes from a single customer, that is a flag I do not ignore. Big Bear has some concentration risk in its government segment, which is visible in their SEC filings. Margin trajectory. Gross margins can be managed with accounting choices, but operating margins tell a truer story about whether a company is getting better at running itself. I track operating margin expansion or contraction over at least three full quarters. One quarter of improvement means nothing. Three consecutive quarters of consistent improvement is a signal worth paying attention to.
Get the Full Details
Cash flow relative to reported earnings. This is where the most deception happens in modern markets. A company can report healthy earnings while bleeding cash, and the reverse is also true. I always compare free cash flow to net income over a rolling twelve-month period. If free cash flow consistently trails net income by more than fifteen percentage points, I dig into accounts receivable and inventory to figure out why. Balance sheet resilience. Debt levels matter, but the structure of that debt matters more. Short-term obligations due within twelve months against available cash and near-term receivables is the metric I actually calculate. Big Bear has carried a modest debt load, which is neither a strong point nor a critical weakness on its own. The real question is whether they can service it through a revenue slowdown without cutting into R&D or operations. Management alignment. Insider ownership and recent buying or selling activity give you a read on whether the people running the company have skin in the game. I prefer to see management buying on dips rather than selling into rallies. When I reviewed Big Bear insiders over the past year, the pattern was mixed, with some executives selling as part of planned diversification and others making small purchases. Nothing that screams alarm, but nothing that builds extra confidence either.
A Specific Problem I Hit and How I Worked Around It
Last fall, I ran into a real complication when analyzing Big Bear Holdings. The quarterly earnings release included a one-time charge related to a contract termination that was not called out prominently in the summary sections. The adjusted metrics the company highlighted looked reasonable, but the unadjusted numbers told a different story. I caught this because I opened the full 10-Q filing rather than relying on the press release, which took me about twenty-five minutes instead of the usual five. The workaround I developed for situations like this is straightforward. I always read the notes to the financial statements, specifically the sections on commitments and contingencies and the breakdown of revenue by segment. That is where material items hide when companies want to downplay them. It adds maybe twenty to thirty minutes to your analysis, but it has saved me from making mistakes at least twice in the past year alone.
What This Method Does Not Do Well
Let me be blunt about the limitations. This framework works reasonably well for established companies with public financials and clear business models. It breaks down for early-stage biotech firms where revenue may not exist for years, for companies operating in jurisdictions with weak disclosure standards, and for situations where the market is pricing in narrative rather than fundamentals. Big Bear falls somewhere in the middle of these categories, which means the framework gives you useful signals but not certainty. The biggest bottleneck is timing. Financial data is always backward-looking, and by the time you have enough quarters to see a meaningful trend, the market may have already moved significantly. I have lost money by waiting for perfect clarity when the actual opportunity window was much narrower. The alternative approach here is to establish a range of acceptable valuations rather than chasing a single target price, and to size positions accordingly so that being partially right still produces acceptable outcomes.
Practical Steps to Apply This Yourself
Start by pulling the latest annual report and the most recent quarterly filing from the SEC website. You do not need a paid service for this. Everything is free at sec.gov. Read the management discussion and analysis section first, then go directly to the financial statements. Skip the marketing language in the CEO letter and focus on the numbers, which is where the actual information lives. Calculate the three key metrics I mentioned above: revenue growth rate, operating margin trend, and free cash flow conversion. Write them down in a simple table with the last eight quarters. The pattern will usually emerge visually even if the individual numbers look noisy. For Big Bear specifically, the revenue growth has decelerated from the double-digit rates seen during the pandemic era to something closer to low single digits in recent periods, which is consistent with a maturing position in a competitive market. Check the short interest and institutional ownership data, which you can find on most financial websites. High short interest combined with declining fundamentals often presages further pressure, while low institutional ownership with improving trends can signal an overlooked opportunity. Big Bear sits in a middle ground here, with moderate short interest that reflects ongoing debate about whether their government contract pipeline will convert into sustained revenue growth.
The valuation piece comes last, not first. Compare the current enterprise value to trailing and forward revenue, then cross-reference that with EV-to-EBITDA multiples from comparable companies in the data analytics and government contracting space. If Big Bear trades at a significant premium to peers without a clear growth or margin advantage to justify it, the market is pricing in optimism that may or may not materialize. I found that during my analysis, the stock has traded at wider multiples than some direct peers during certain periods, which suggests the market is assigning a premium for the government exposure and AI narrative rather than pure financial performance.
Bottom Line Without the Bottom Line
Big Bear Holdings presents a mixed picture depending on what you prioritize. The government contract base provides some stability, the AI and analytics positioning is in a growing market, and the balance sheet is manageable. The concerns are real too: decelerating growth, margin pressure, competitive pressure from larger players, and the inherent unpredictability of government spending cycles. I have not made a definitive buy or sell call on this one in my personal portfolio, and I watch it from the sidelines with a small position that reflects the uncertainty rather than conviction. That is an honest assessment, and it is better than either extreme enthusiasm or blanket dismissal. If you are building your own analysis on this, the most useful thing you can do is update the quarterly numbers as they come in and track whether the margin and cash flow trends improve or worsen over the next two to three quarters. That will tell you more than any single earnings report ever will.