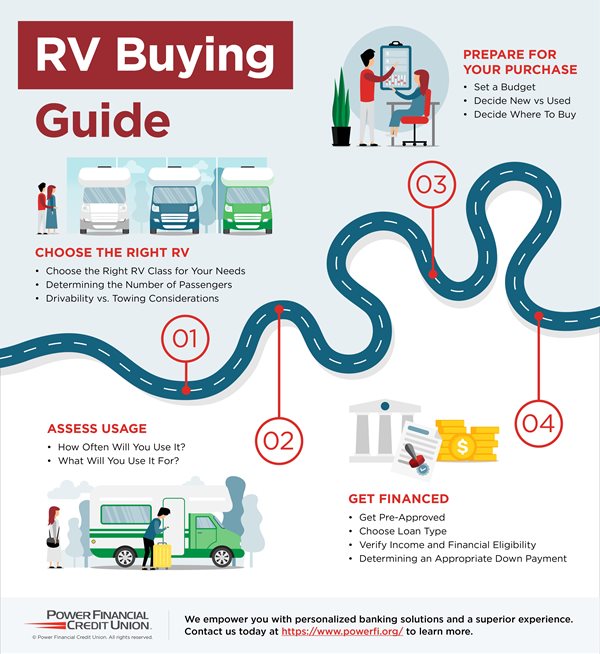
Camper financing is messier than most people expect
I spent three weeks last year looking at loans for a Class C that I wanted to use for weekend trips. The dealerships in my area had maybe four or five lenders they were willing to run you through, and each one handled things differently. If you're about to sit down with a salesman or browse options online, there are specific questions you should have ready before anything else. This is what I figured out the hard way. The first thing I learned is that not all lenders treat campers like regular vehicles. That matters a lot. When I walked into a dealership, the finance manager pulled up rates that were clearly optimized for his house lender, and they were worse than what I'd seen elsewhere. Before you let them touch your credit application, ask these things straight out. Is this a manufactured housing loan or an RV loan? This one catches people off guard. If the camper is going to be parked at a site long-term, some lenders reclassify it as personal property or even real estate-adjacent. That shifts the rate by a full point or more. A lot of dealers don't flag this distinction until the paperwork is already moving. I had a situation where a unit I was financing turned out to be listed under a different classification on the title, and my closing costs jumped nearly two thousand dollars because of it. I pulled the title documentation and cross-referenced it with the HUD appraisal guide for manufactured structures before I signed anything. Once I caught that, the lender switched it to a standard RV loan category and we were back on normal terms.
What is the APR versus the interest rate? Dealers love to lead with the interest rate because it sounds lower. The APR includes the origination fee, the processing charges, and sometimes the prepayment penalty. On a $60,000 loan over seven years, that difference can be anywhere from $800 to over $2,000. Ask them to show you both numbers side by side on the same screen. Most of the time they will, but only if you ask first. Are there any prepayment penalties? I've seen this one in two separate financing deals now. A couple of lenders in my region stick prepayment penalties into the fine print if you pay off the loan early. It usually reads like something only a fifth-grade reading level can parse. One lender charged 3% of the remaining balance if you paid off within the first three years. That's roughly $1,800 on a $60,000 loan if you cleared it in year two. Just find out upfront whether it exists so you can avoid those lenders entirely. What is the minimum credit score for the advertised rate? Every dealer will show you a rate that sounds impossible to beat. Those rates are usually reserved for scores above 740. If you're in the 680 to 739 range, you should get a straightforward answer about what rate you actually qualify for, not the marketing number. I asked this question directly and the finance guy actually smiled, which was unusual. He gave me the real rate without any extra conversation about it being a disappointment. That honesty was worth more than the rate itself.
Can I lock the rate before I place the order? RV prices fluctuate and rates do too. Locking before you commit gives you a window where neither price nor rate can move against you. Most lenders offer a 30-day lock, sometimes 45. Without a lock, you're gambling on the market staying stable while you shop. The cost of a lock is usually negligible compared to a half-point rate increase during the waiting period. What happens if the camper fails inspection or the appraised value comes in low? This is one of those things nobody mentions until it happens to you. If you put down a small down payment and the unit appraises for less than the purchase price, you're on the hook for the gap. It sounds obvious, but a lot of people assume the loan covers the full amount regardless. I once saw a buyer sign papers without asking this question and then get hit with a $4,500 shortfall because the appraiser valued the camper well below the sticker. Having a clause in your contract that lets you walk away or renegotiate if the appraisal comes in under a certain threshold is worth having. I made sure that language was in every deal I closed.
Get the Full Details

Common financing structures and when to avoid them
RV loans generally fall into a few categories. The standard secured loan uses the camper itself as collateral. The rate is usually lower but your asset is on the line. If you miss payments, you lose the unit. This is the most common route and works fine for most people who can handle the monthly payment without stress. Manufactured home loans exist for units that are parked permanently and treated more like real estate than vehicles. The terms are longer, often 15 to 20 years, and the interest rates can be worse than RV loans. These loans sometimes require the land to be owned outright or financed separately, which adds a layer of complexity most campers don't need. Avoid this category unless you actually need the longer term to make the numbers work. The shorter-term RV loan is almost always cheaper overall despite the higher monthly payment. Credit union loans are worth checking before you walk into a dealership. I found a credit union in my area offering a rate that was 0.75% lower than the best dealer-lender offer. The trade-off is that credit unions tend to have slower closing times, maybe two to three weeks instead of a day or two. If you're not in a rush, the savings are worth the wait. A 0.75% difference on a $50,000 loan over seven years is about $1,900 in total interest savings. That's real money, not theoretical.
What about balloon payment loans? These exist and they look attractive at first because the monthly payment is much lower. The catch is the balloon payment at the end, which can be 30 to 40% of the original loan amount. I've seen people get into this trap without realizing the size of the final payment until the last month. The only scenario where this makes sense is if you're certain you can sell the camper or refinance before the balloon comes due. Otherwise it's a financial landmine.
The negotiation part most people skip
After you get the loan terms, there's still room to negotiate the dealer's add-ons. The extended warranty, the spare tire coverage, the service contracts. These markups can add $2,000 to $5,000 to your total cost, and they're all optional. I walked away from a $3,200 extended warranty once because the dealer wouldn't budge on the price and the coverage terms were terrible. The warranty excluded wear items and had a deductible that made it basically useless. You can get comparable coverage elsewhere for half the price if you bother shopping around, but you have to know what you're getting into. Asking for the out-the-door price before you discuss financing changes the entire dynamic. When you talk price first, the dealer can't hide fees inside the loan terms. I insist on seeing the total price with all fees broken out before I ever mention financing. It takes about ten minutes and it prevents the dealer from adding surprise charges later. Interest rates on RV loans have been moving recently. Depending on when you read this, the current environment could be favorable or unfavorable. Credit unions tend to be more stable with their rates, which is another reason to check them before committing to a dealer lender. The process of comparing three or four lenders usually takes an afternoon and can save you several thousand dollars over the life of the loan. It's not complicated, just tedious. Do the tedious part first so the rest of the deal feels easy.

If the loan terms feel unclear, ask the lender to send you the full disclosure documents before you sign. Most will, and reading through them takes about 20 minutes. Those documents will tell you everything about fees, penalties, and payment schedules. Reading them beats relying on a verbal explanation that may or may not be accurate.


