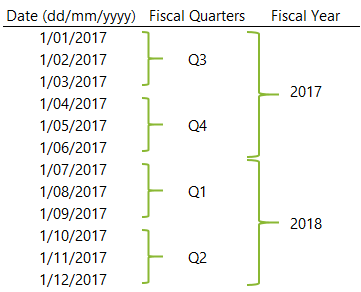The Last Three Months Make Or Break Your Year
Q4 is where most fiscal plans go to die. You spend the first nine months building reasonable projections, then October through December hits and everything has to compress into a frantic finishing sprint. I have watched more than one company blow through their entire annual budget in November because procurement was waiting for Q4 pricing commitments to finalize vendor contracts. There is a specific rhythm to this quarter that most people miss until they have already messed up the numbers. The problem is not that Q4 is hard. The problem is that it is structurally different from the rest of the year in ways that accounting systems and management software rarely account for.
Quarter 4 Of The Year Navigating The Climax Of The Fiscal Calendar
Let me start with the mechanics before the strategy. In a standard calendar-year fiscal structure, Q4 runs October 1 through December 31. That is the easy part. What actually matters is the gap between when transactions occur and when they get recorded. Most companies process revenue recognition and expense accruals on a month-end close schedule, but Q4 compresses that timeline because leadership expects final numbers before January. You are essentially running two close cycles in one month. Here is the workaround I ended up using after burning through three straight years of December chaos. We shifted our actual close calendar for Q4 items to a mid-month hard cutoff. Everything posted by the 15th gets pulled into the quarter's financials without exception. Anything after the 15th rolls into January regardless of how material it is. Yes, this means some legitimate October expenses show up in November's books sometimes. That is fine. The alternative was spending the last three weeks of December manually chasing down receipts from sales teams who had disappeared into holiday plans. The real friction in Q4 usually comes from revenue recognition timing. If you are on a cash basis this is straightforward. If you are accrual, you have to decide whether to recognize contracted but unbilled revenue at quarter end or wait. I ran into this exact problem last year with a software company that had delivered three major deployments in late November but did not issue invoices until January. Their contract terms specified payment within thirty days of delivery, which meant those revenues legally belonged in Q4. We ended up creating a manual accrual schedule instead of waiting for the billing cycle. It added about six hours of work for our accounts team in early December but saved us from a restatement in February.
The Accrual Trap Most People Fall Into
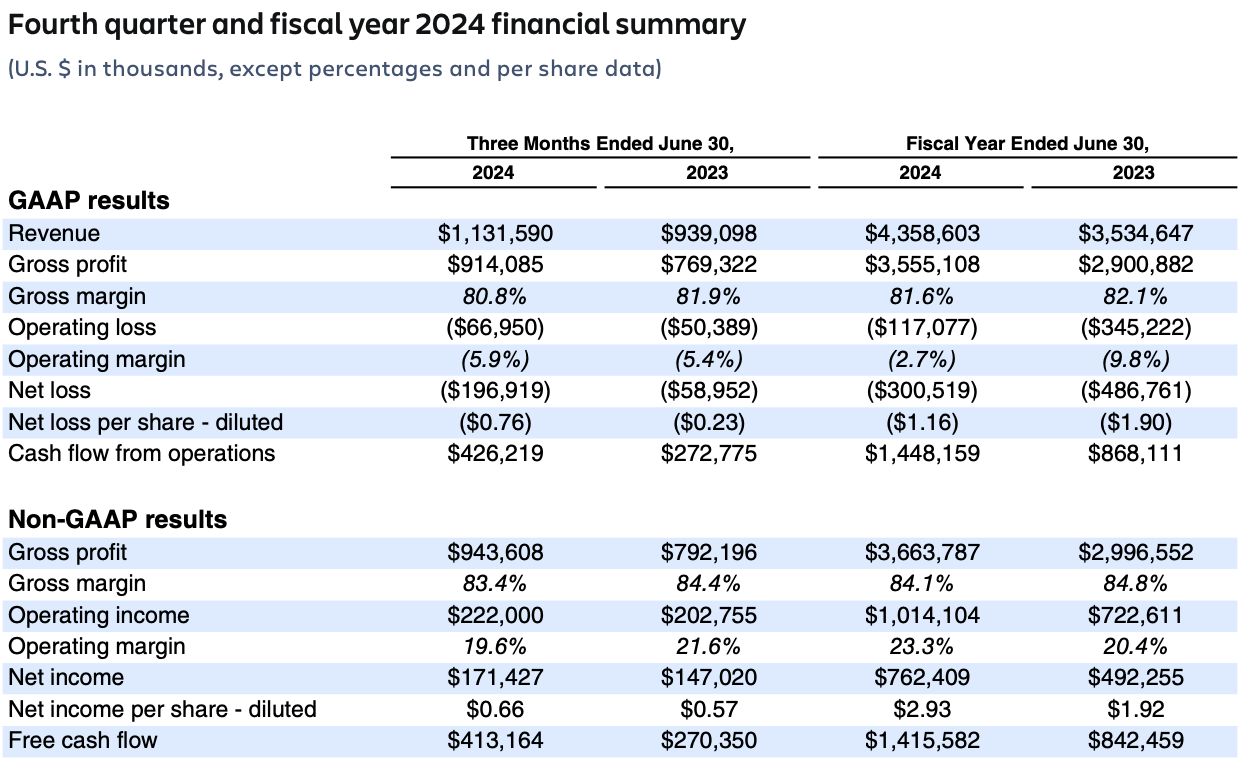
Beginning CFOs and controllers tend to treat Q4 like a normal quarter with extra steps. It is not. The volume of year-end adjustments, bonus accruals, tax provisioning work, and audit preparation creates a bottleneck that typically consumes forty to sixty percent of your finance team's bandwidth in November alone. If you are not planning for that specifically, you will be behind by mid-quarter. I learned this the hard way. One year I assumed we could handle bonus accruals and tax provisions in parallel. We could not. The bonus calculations depend on final EBITDA figures, and EBITDA depends on the tax provision assumptions, which depends on whether certain year-end expenditures qualify for immediate deduction or need to be capitalized. That circular dependency added almost two weeks to our close timeline. Now I run tax provisioning first, lock in the numbers, then feed those into bonus accrual models. Order matters here. Another thing nobody warns you about: bonus timing can distort your P&L in ways that look terrible to stakeholders if you do not communicate the mechanics upfront. I once had a board member ask why our operating margin dropped twelve percentage points in Q4 when revenue was up. The answer was a single accrued bonus pool that represented fourteen percent of quarterly revenue. It was accurate. It just looked alarming without context. We now include a one-line reconciliation in every Q4 board pack that isolates non-recurring year-end accruals from operational performance. It takes five minutes to prepare and prevents entirely unnecessary panic.
Get the Full Details
Inventory And COGS: The Hidden Quarterly Killer
If your business moves physical product, Q4 is where inventory valuation methods get tested. Last-in-first-out companies especially feel the pressure here because purchasing volumes spike and you are trying to match costs against revenue that was booked earlier in the quarter. I worked with a wholesale distributor who switched to a weighted average cost method specifically for Q4 because their LIFO calculations were producing month-over-month swings that made it impossible to explain to anyone outside the accounting department. The COGS numbers also get complicated by seasonal markdowns. Retail businesses typically take aggressive inventory write-downs in late December to clear out seasonal stock. If you wait until after the quarter closes to record those, your gross margins will be artificially inflated for Q4 and crushed in Q1. Book them during the quarter. I recommend setting a markdown reserve estimate by December 10 based on historical clearance percentages. It does not need to be exact. It needs to be defensible if an auditor asks.
The Audit Crunch
External auditors flood your office in January. This is universal. They also want to confirm receivables and payable balances as of December 31, which means they will send confirmation requests in the first week of January when your accounts receivable team is already dealing with post-holiday collections. I resolved this by sending our own internal confirmation letters to our top fifty customers and suppliers during the last week of December. The external auditors accepted our internally generated confirmations with only minimal verification. This cut what normally would have been a three-week confirmation cycle down to roughly five business days in January. One other audit-related note: if your company carries a significant amount of long-term debt or lease obligations, review the amortization schedules in November rather than December. I saw a mid-market company discover in early January that their lease modification from the previous spring had not been properly reflected in their December 31 balance sheet. Correcting that required pulling in legal documents and recalculating the right-of-use asset, which delayed their financial statements by eleven days. A thirty-minute review in November would have caught it immediately.
What Does Not Work
Do not attempt to do everything manually in spreadsheets during Q4. I tried it for two years. Spreadsheet-based tracking for accruals, bonus pools, tax provisions, and revenue reversals creates version control nightmares. Someone inevitably updates a cell, someone else works from the old file, and you end up with two different numbers presented to two different people on the same day. We moved to a dedicated close management tool that enforces deadlines and locks entries once they pass. It saved us approximately eight hours per closing cycle starting in November. Also do not assume that your Q3 processes will transfer directly into Q4. They will not. The volume, the pressure, and the number of simultaneous workstreams are different enough that you should treat Q4 as a separate operational phase. Build a specific Q4 checklist that includes items your normal monthly close routine never addresses: bonus accrual validation, tax provision milestone dates, inventory write-down estimates, year-end revenue cut-off procedures, and audit confirmation timelines. I use a version that runs about forty items long and assigns each one to a specific person with a hard due date. Without that specificity, things slip.

The Cash Flow Disconnect
Your P&L and your cash position will diverge significantly in Q4. Revenue might look strong on paper because you recognized contracts that were signed in November but will not be paid until February. Meanwhile, your vendor payments, tax payments, and bonus payouts are all hitting in December. I have seen this exact scenario produce a cash deficit that made it look like the company was in distress when the underlying business was perfectly healthy. The fix is maintaining a rolling thirteen-week cash flow forecast that gets updated weekly starting in October. It does not predict the future. It just tells you when you will actually need the money. One final practical point. If you use an ERP system, do not wait until December to test your close workflow. Run a dry close in late November using a copy of your production data. This catches configuration issues, approval routing errors, and period lock problems before they become real. The test typically takes about four hours and prevents the kind of system-level failures that can push your official close date out by a week or more. The fourth quarter of any fiscal year is not a crisis to survive. It is a planning problem. The companies that handle it well are not the ones working the longest hours in December. They are the ones who accepted early that Q4 operates under different rules and built their calendar around that fact instead of pretending it behaves like any other three-month period.