The Qualified Dividends and Capital Gain Tax Worksheet Explained
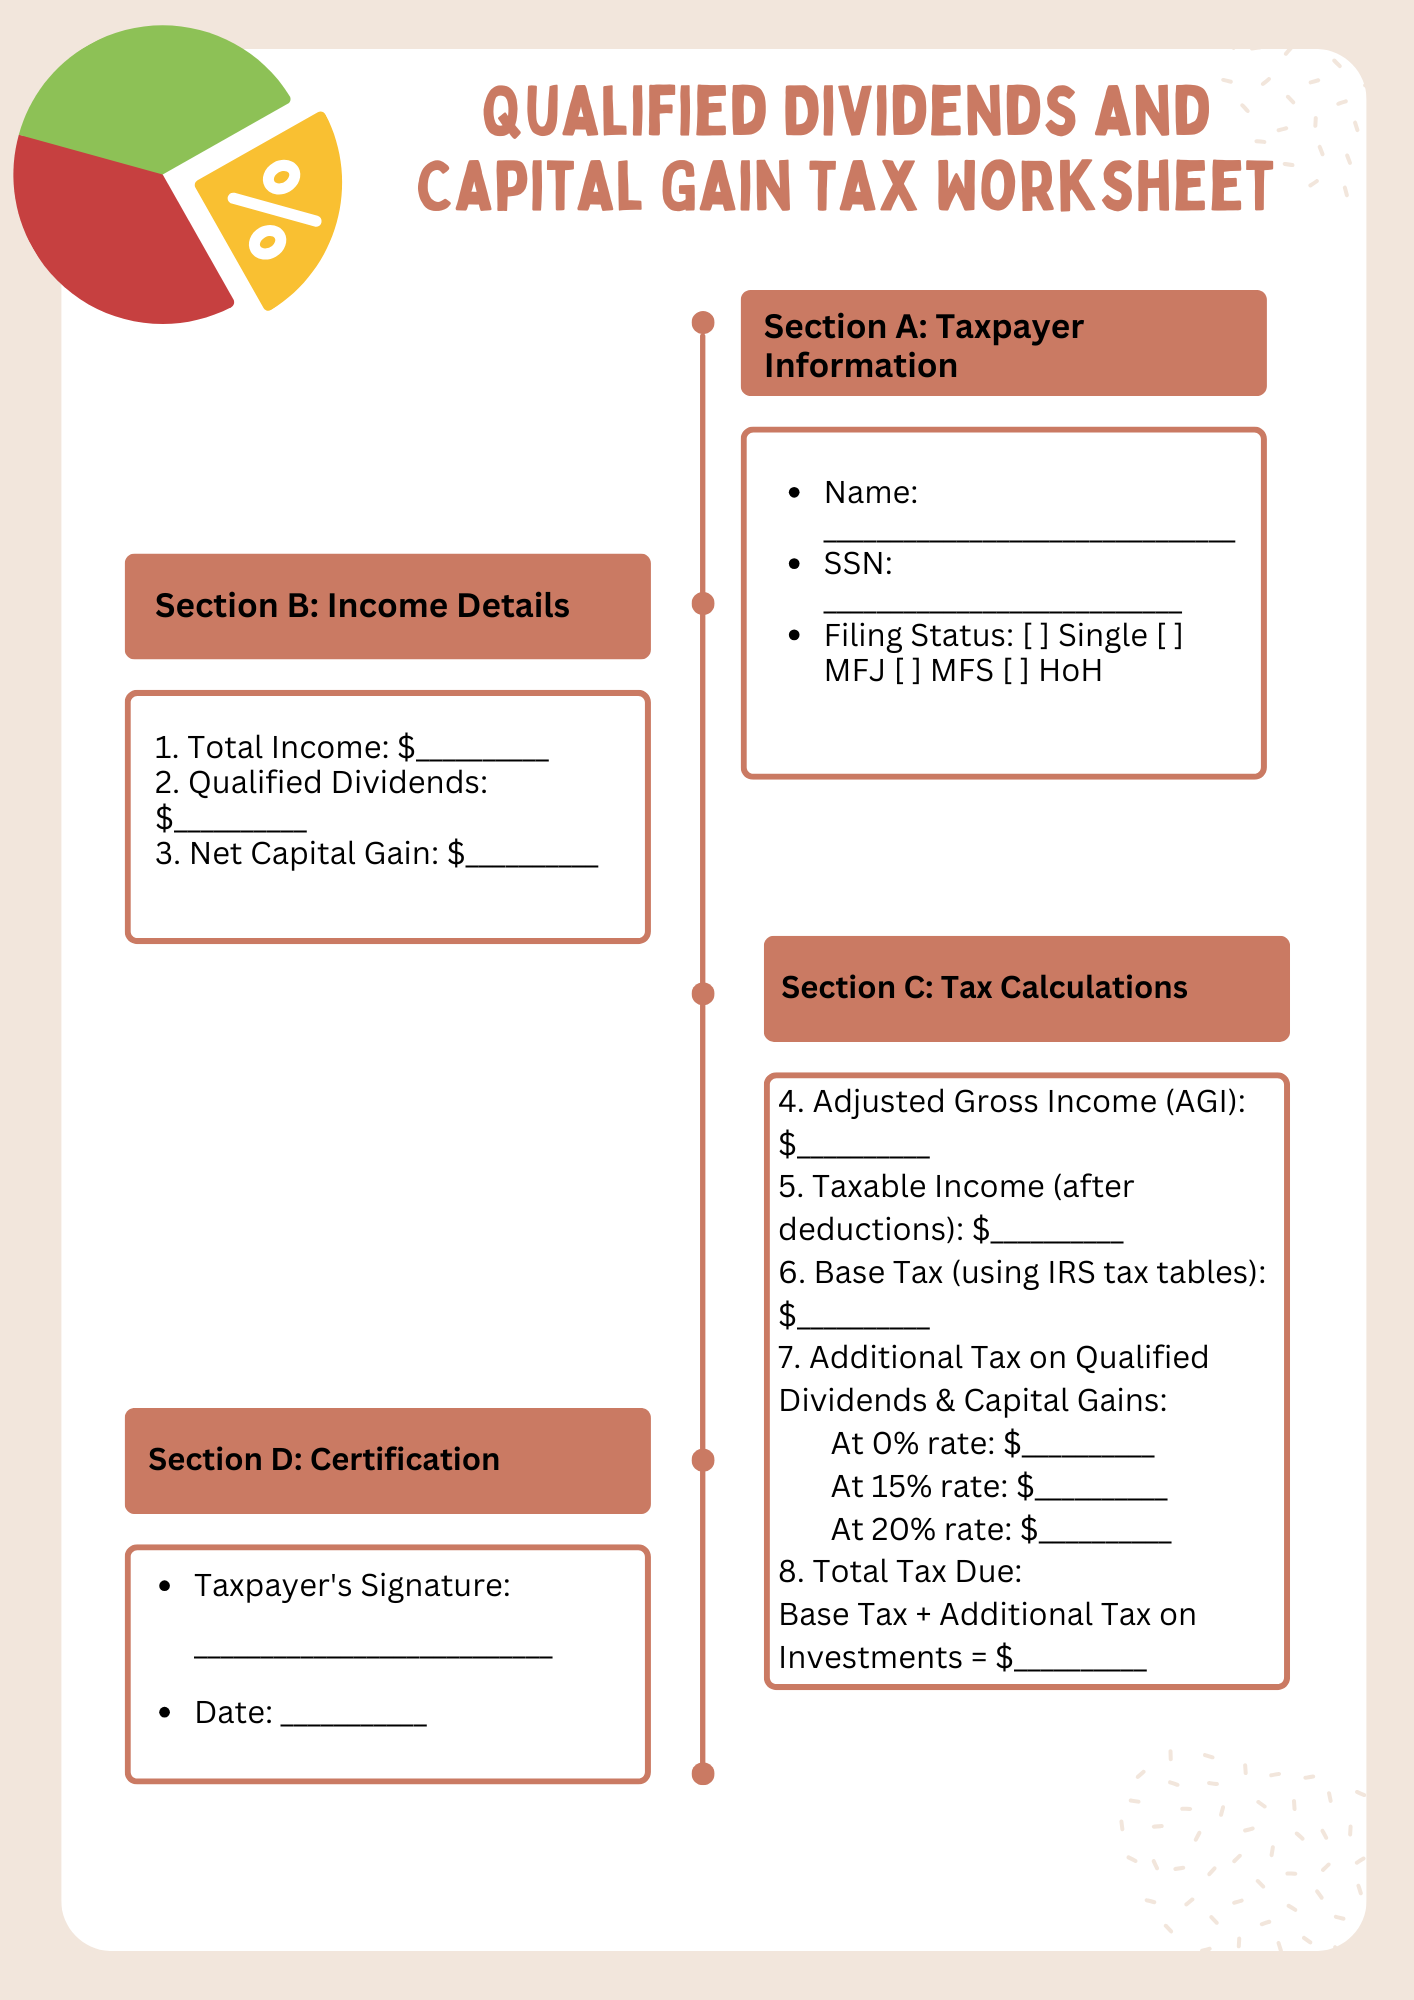
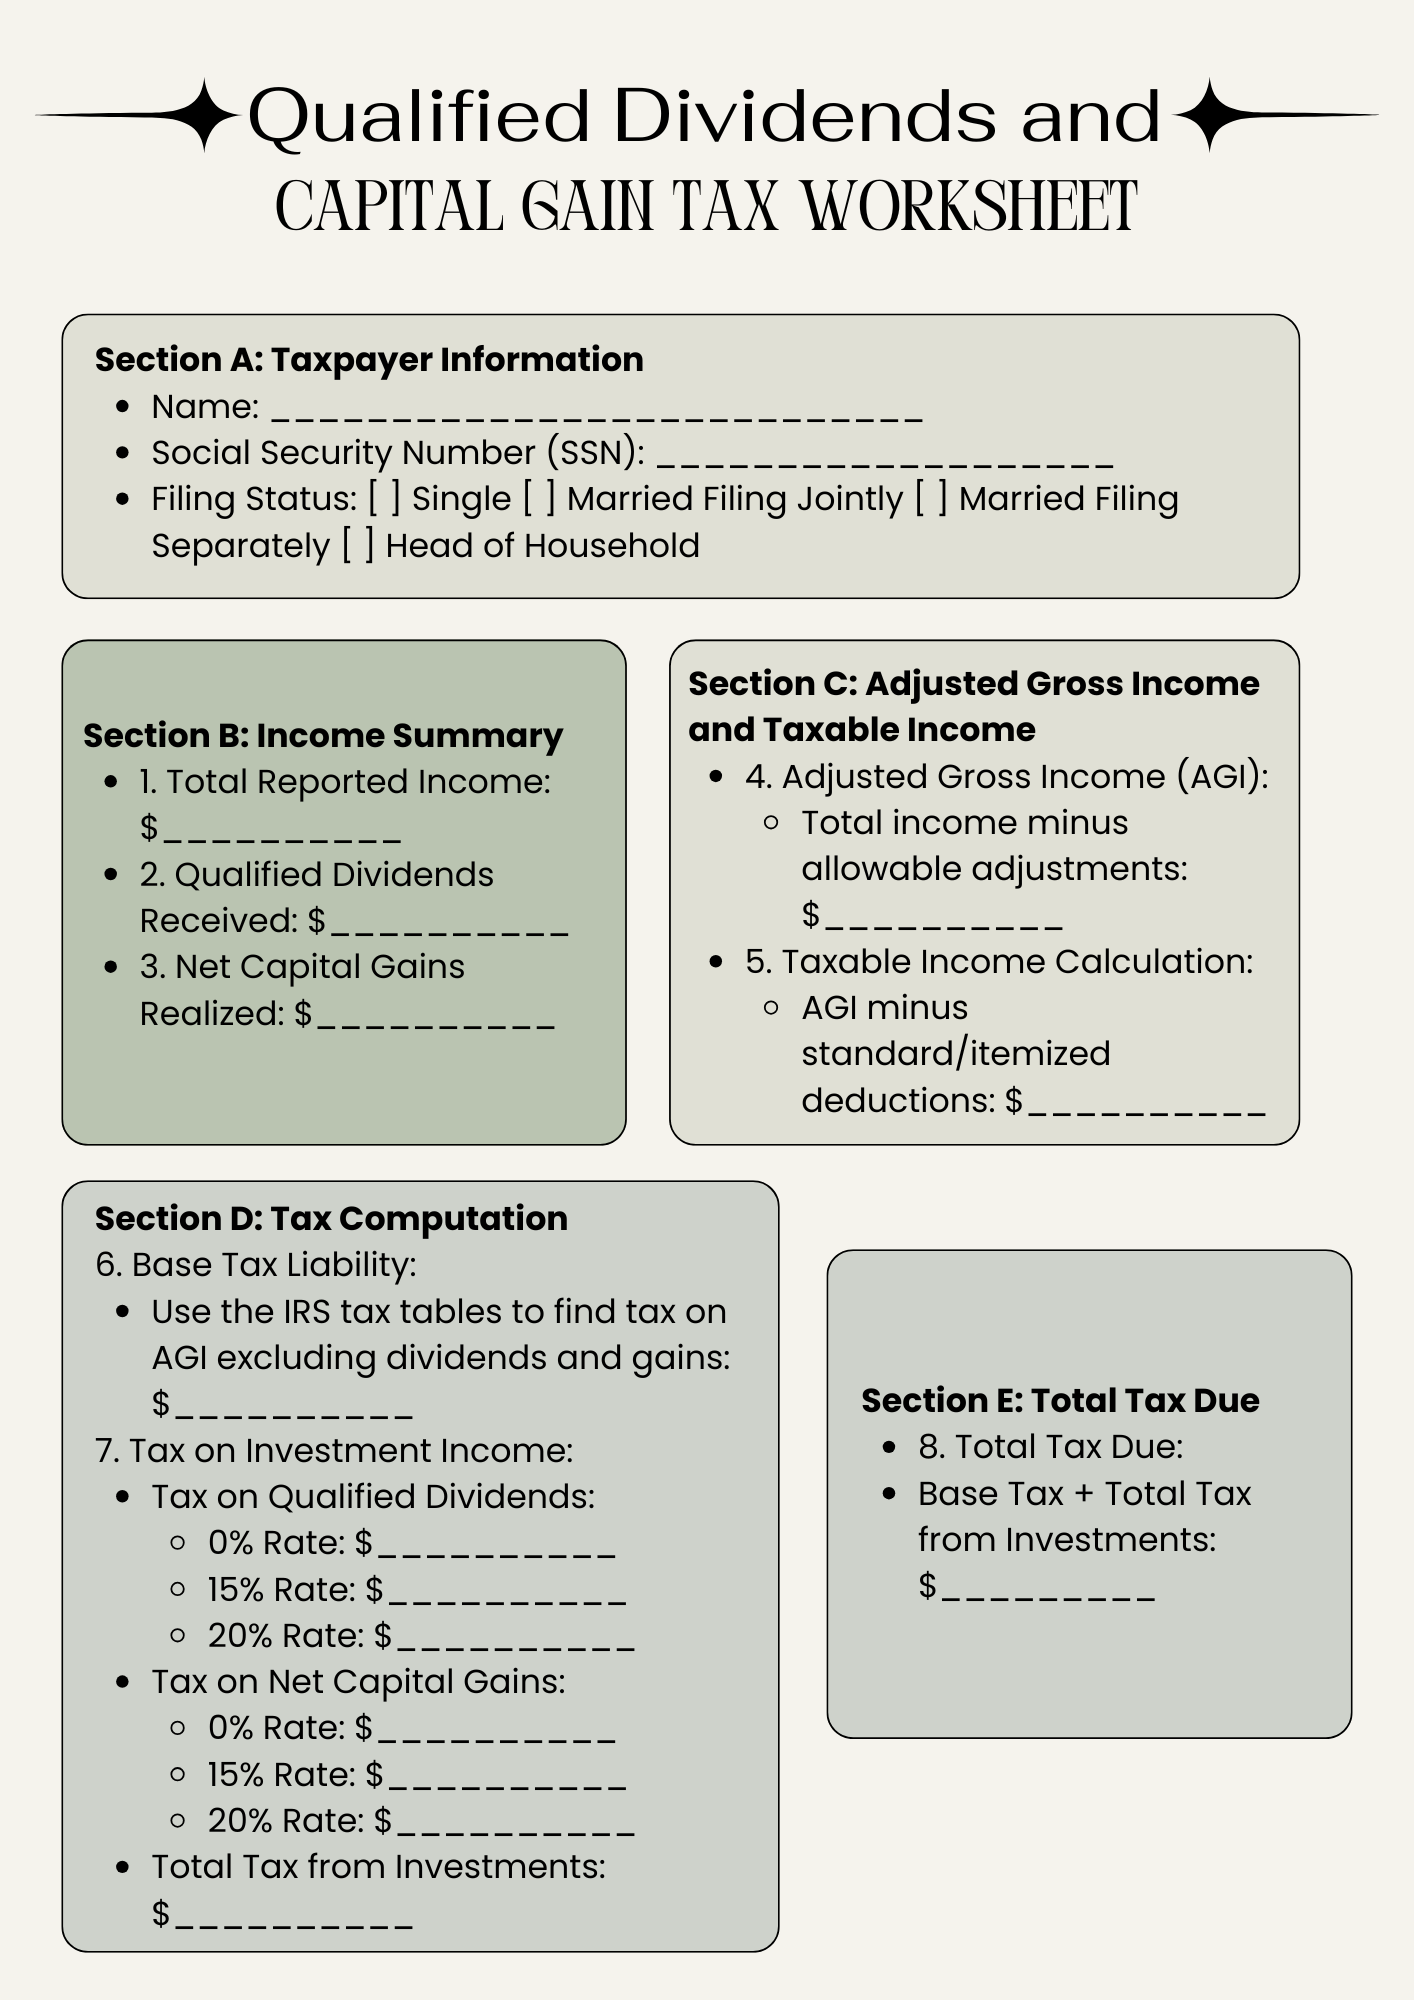
If you file Form 1040 and receive qualified dividends or have long-term capital gains, you've probably encountered the Qualified Dividends and Capital Gain Tax Worksheet sitting somewhere in the IRS instructions. Most people skip it or fill it out wrong because they don't understand what it actually does. This guide will walk you through it, and I'll share a few things that aren't obvious from reading the form itself. It's an optional calculation tool built into the IRS Form 1040 instructions that determines whether you're better off paying tax on your qualified dividends and net capital gain at the preferential rates (0%, 15%, or 20%) instead of the ordinary income tax brackets. The worksheet isn't something you attach to your return. It's a scratchpad. You work through it line by line, get a final number, and then enter that number on the main 1040. That's it. The reason it exists is that the tax code taxes qualified dividends and long-term capital gains differently than your wages or interest income. Without this worksheet, the IRS software or your tax preparer might accidentally apply ordinary rates to income that deserves the lower preferential treatment. For a lot of people, that mistake costs hundreds or even thousands of dollars.
I've done this for years, both as a preparer and as someone filing my own returns. The worksheet is not intuitive. The lines jump around. The brackets change. And the interaction between the Net Capital Gain Worksheet and the qualified dividends worksheet is where most people get tripped up. Here's how it actually works.
How to Use the Worksheet Step by Step
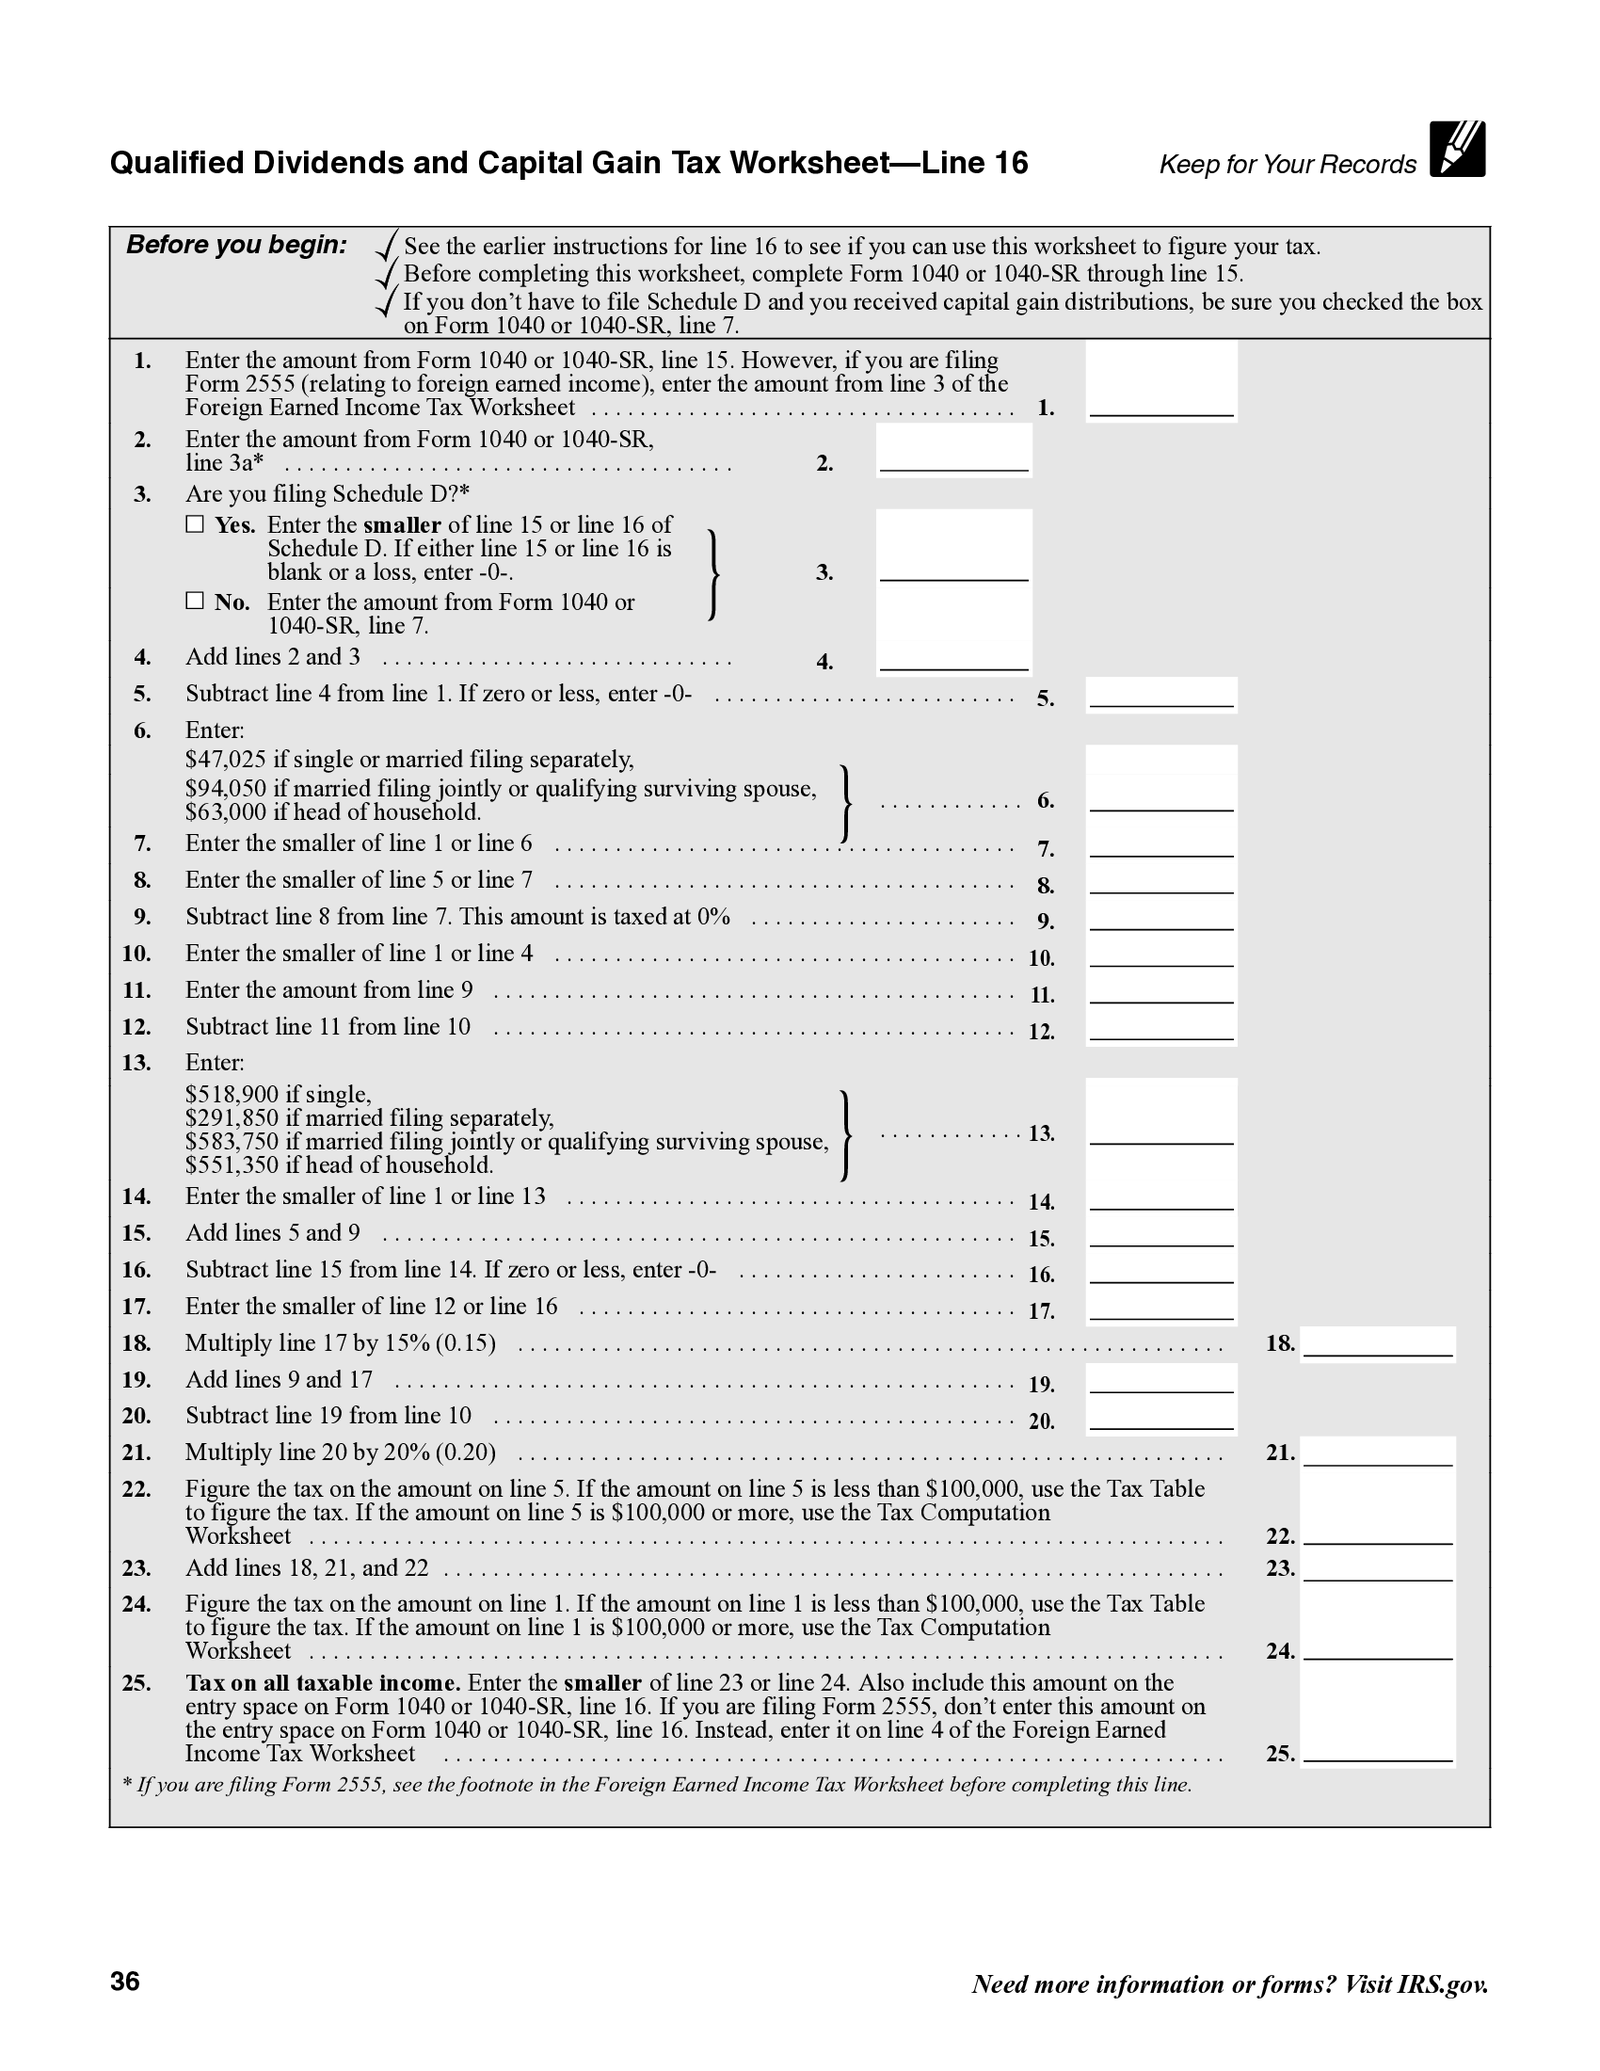
First, you need to know where to find it. It's in the instructions for Form 1040, usually under a section called "Qualified Dividends and Capital Gain Tax Worksheet." The exact line numbers and structure vary slightly by tax year. For recent years, the worksheet typically has somewhere between 15 and 25 lines depending on your situation. You'll also need your W-2, your 1099-DIV, and potentially your Schedule D if you have capital gains to report. Line 1: Start with your taxable income from line 15 of your Form 1040. If you're using tax software, this number should already be populated. If you're doing this on paper, double-check it against your 1040. Line 2: Enter any taxable amount from your pension or annuity if you're filing Schedule B. This is a less common situation, but if you have one, it matters here.
Get the Full Details
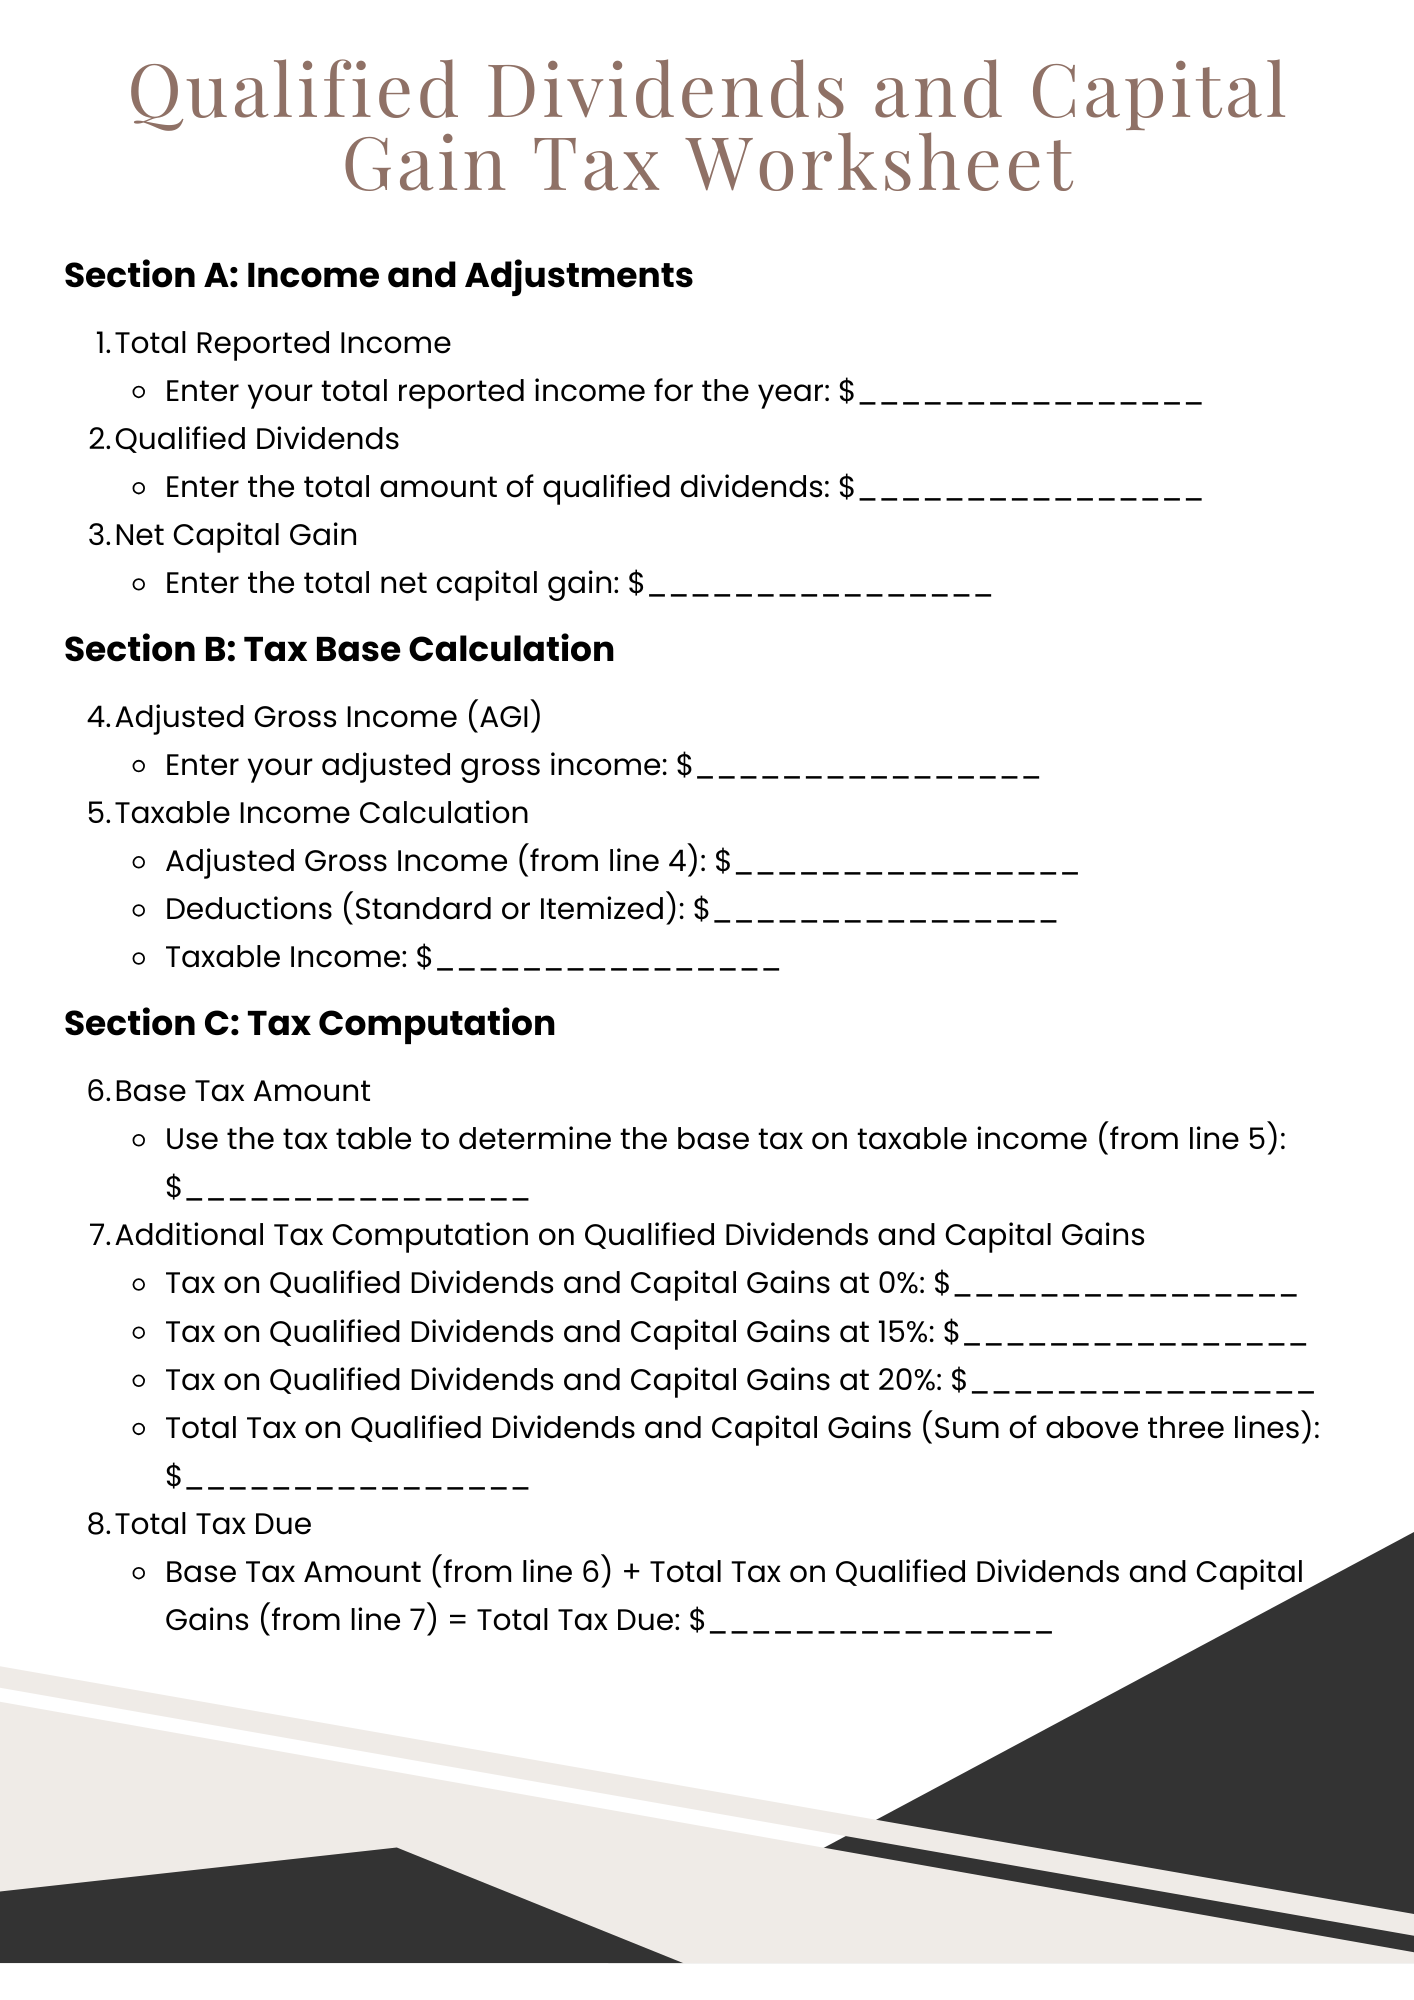
Line 3: This is where things get specific. You enter the smaller of your qualified dividends or your net capital gain. Wait, let me explain that because it's easy to get wrong. You compare two numbers: the total qualified dividends from box 1b of your 1099-DIV, and the net capital gain from Schedule D if you have one. You take whichever is smaller. If you only have qualified dividends and no capital gains, then line 3 is just your qualified dividends. If you only have capital gains and no qualified dividends, line 3 is your net capital gain. If you have both, you pick the smaller of the two. I learned this the hard way back in 2019. I had $18,000 in qualified dividends and $12,000 in net capital gains. I put the full $30,000 on line 3 because I thought you just added everything together. That was wrong. The worksheet specifically says to use the smaller amount. I ended up over-treating the difference and my tax was higher than it should have been. I had to file an amended return. Never again. Line 4: Subtract line 3 from line 1. This gives you the portion of your taxable income that's not covered by the preferential rate calculation. Most people get nervous here because the number feels arbitrary, but it's just a mechanical step that determines how your remaining income gets taxed.
Line 5: Enter the amount from line 15 of your 1040 again, or use a different line depending on your specific version of the worksheet. This varies by year. Always check the instructions for your tax year. Don't assume last year's worksheet is identical to this year's. Line 6 and beyond: Now you start applying the actual tax rate calculations. The worksheet has you compare your numbers against the income thresholds for the 0%, 15%, and 20% capital gains brackets. For 2024, those brackets for single filers are roughly: 0% up to about $47,025 of taxable income, 15% from $47,026 to $518,900, and 20% above that. Married filing jointly roughly doubles those numbers. The worksheet does the math for you, but you still need to understand which bracket you're in so you can verify the result makes sense. The final output of the worksheet is a tax amount that you then enter on line 15 or 16 of your Form 1040, depending on the year. That number replaces the tax you would have calculated using the regular tax tables if you hadn't run the worksheet.
When You Actually Need to Use It
You need this worksheet if any of the following apply to you: - You have qualified dividends reported in box 1b of your 1099-DIV - You have a net capital gain on Schedule D
- You have both If your only investment income is ordinary dividends (box 1a, not 1b), short-term capital gains, or interest income, the regular tax calculation on your 1040 is sufficient. The worksheet doesn't apply to you. Here's a counter-intuitive point that most people miss: having qualified dividends doesn't automatically mean you'll save money by using this worksheet. In some edge cases, particularly when you have a mix of preferentially taxed income and certain deductions or credits that phase out, the regular tax calculation can actually come out lower. I ran into this with a client who had significant qualified dividends but also was near the threshold for several phase-outs. Running both calculations side by side revealed that the ordinary tax method saved her about $400. She was shocked. The worksheet is designed to help, but it's not a universal win.
Another thing nobody warns you about: the worksheet only accounts for the interaction between qualified dividends, capital gains, and your ordinary income tax. It doesn't factor in the Net Investment Income Tax (NIIT), which is an additional 3.8% that kicks in at higher income levels. If you're subject to NIIT, you need to run a separate calculation for that on Schedule NEC. The two calculations are independent. The worksheet won't tell you about NIIT. I always check for NIIT eligibility after running the worksheet, just to catch that extra tax.
Common Mistakes and How to Avoid Them
The biggest mistake is putting the wrong number on line 3. As I mentioned, you take the smaller of qualified dividends or net capital gain. Not the sum. The smaller. If you have $25,000 in qualified dividends and $30,000 in net capital gain, you put $25,000 on line 3, not $55,000. The worksheet is designed to prevent double-counting income that's already being treated preferentially. The second biggest mistake is confusing short-term and long-term capital gains. Short-term gains are taxed at ordinary rates. They don't belong on this worksheet at all. Only long-term capital gains from Schedule D, line 16 (or the applicable line for your year), go into the calculation. If you sell stocks held for less than a year, that income goes through the regular tax computation, not the preferential one. A third mistake is forgetting that the worksheet must be completed even if the result is the same as the regular calculation. The IRS doesn't care that you're getting the same number either way. If you have qualified dividends or net capital gain, you're supposed to run the worksheet and enter the result. Skipping it won't necessarily trigger an audit, but it leaves you without a record of why you chose the regular tax computation over the preferential one. That's a gap that comes back to haunt you during an examination.
Practical Tips That Actually Help
If you're doing this by hand, keep a separate sheet of paper for intermediate calculations. The worksheet references its own lines, and it's easy to lose track of which number came from where. Write down each line's source, like "line 3 = smaller of $X from 1099-DIV box 1b and $Y from Schedule D line 16." Five minutes of note-taking now saves you an hour of reconstruction later. Don't trust your tax software to have done this correctly without checking. I've seen automated returns where the software silently applied the regular tax rates instead of the preferential ones, resulting in a higher tax liability. The software calculated something, but it wasn't necessarily the right something. Cross-reference at least two lines between the worksheet output and what the software produced. If they match, great. If they don't, investigate immediately. For high-income earners, pay attention to the interaction between the capital gains brackets and the regular tax brackets. There's a range of income where your marginal ordinary tax rate is 24% but your capital gains rate is 15%. That gap creates opportunities for tax planning, like harvesting losses or deferring gains into the next year. The worksheet itself won't tell you this, but understanding it while you're filling out the form can change your entire year-end strategy. I had a client who realized mid-worksheet that he was about $3,000 over the 15% capital gains threshold. We adjusted his withholding for the final quarter of the year and moved some sales to the next tax year. The worksheet result changed by about $600, but the overall tax picture improved significantly.
What the Worksheet Cannot Do for You
It's important to be clear about the limitations. The Qualified Dividends and Capital Gain Tax Worksheet only addresses the interaction between preferentially taxed investment income and your ordinary income tax. It does not calculate your self-employment tax. It does not handle the additional Medicare tax on high earners. It does not account for state taxes, which vary wildly. It does not help with AMT calculations, though if you're subject to AMT, you'll need a separate worksheet for that anyway. And it doesn't replace professional advice if your situation involves complicated entities like trusts, partnerships, or foreign income. Also worth noting: if your only investment income is from a single 1099-DIV with qualified dividends and no capital gains, and your taxable income is below the 0% capital gains threshold, the worksheet will likely show that you owe zero tax on that dividend income. That's correct, but it can feel counterintuitive. You're earning money and the form says you owe nothing on it. That's how the tax code works at those income levels, and there's no error to fix. Just accept it and move on. If you find the worksheet confusing or your situation involves multiple sources of investment income, estate distributions, or complex capital gains situations, the most practical alternative is to use a certified tax professional or a reputable tax preparation service. The worksheet is designed for straightforward situations. When your situation isn't straightforward, the worksheet becomes less of a time-saver and more of a liability. I've spent entire weekends untangling worksheet errors from DIY filings. It's not fun, and it's not efficient. Knowing when to stop trying to do it yourself is part of the process.
The worksheet itself is available in the official IRS Form 1040 instructions, which you can download from irs.gov. It's free. No registration required. No paid tool needed. Just the official instructions and a calculator. That's all you really need to get it right the first time.