The Practical Reality of Argentina's Sovereign Debt Crisis
Argentina's external debt situation is one of those topics that looks simple on the surface but falls apart the moment you actually try to parse the details. Most people reading about it walk away thinking they understand it. They don't. Let me walk through what actually matters here. The basic architecture is this: Argentina has defaulted on its sovereign debt multiple times, most recently in late 2020, which was actually a technical default on roughly $65 billion in obligations. The country has been in and out of restructuring negotiations for over two decades. The International Monetary Fund alone is owed approximately $44 billion as of the most recent disclosures, making it Argentina's single largest bilateral creditor by a significant margin. What nobody tells you when they summarize this is how fragmented the creditor landscape actually is. You've got bondholders split across dozens of tranches with different governing laws, coupon structures, and maturity dates. Some bonds fall under New York law, others under Argentine law. The enforcement mechanisms are entirely different depending on which jurisdiction applies, and that distinction alone determines whether a creditor can seize assets or is stuck pursuing diplomatic channels.
I worked through a restructuring analysis back in 2019 where the initial model came back saying Argentina could service its obligations under a baseline scenario. The problem was the model was using nominal GDP growth assumptions that hadn't accounted for the inflation adjustment on local-currency indexed bonds, commonly referred to as CER bonds. Once I pulled the real inflation-indexed payment schedule into the debt service calculation, the surplus disappeared completely and the restructuring timeline needed to be extended by roughly eighteen months. That was the kind of detail that made or broke the negotiations.
How the Debt Structure Actually Works
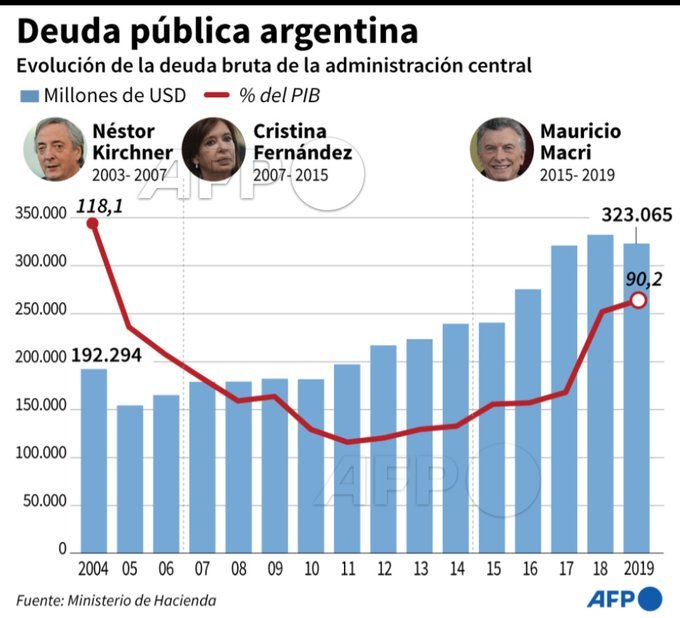
Argentina's external debt sits somewhere between $200 billion and $300 billion depending on how you count restructured obligations and what exchange rate assumptions you apply. The IMF loan from 2018 was the largest single credit facility ever extended to a country at that time, roughly $57 billion, and it came with strict conditionalities around fiscal targets and central bank independence that became politically explosive. The 2020 restructuring is where things get mechanically interesting. Argentina swapped approximately $65 billion in old bonds for new ones at a steep hair cut. Bondholders took between 65 and 70 percent face value losses depending on which tranche they held. In exchange they received something called growth bonds, which are CPI-linked instruments that pay higher coupons if Argentina's GDP exceeds certain thresholds. It's an innovative structure on paper but in practice it means creditors are now betting on Argentina's economic performance rather than being guaranteed a fixed repayment, which is a fundamental shift from how sovereign debt normally works. The holdout creditors from the 2001 default are a separate problem entirely. Entities like NML Capital, previously known as Elliott Management's fund, refused to participate in the restructurings and pursued full face value repayment through the courts. The famous ruling by Judge Thomas Griese in 2014 basically said Argentina couldn't make debt service payments to the restructuring creditors while it was still in legal default to the holdouts. That blocked payments for years and created the so-called "equal treatment" clause complications that kept resurfacing every time Argentina tried to access international capital markets.
Get the Full Details

The Currency Mismatch Problem
Here's where most coverage of Argentina's debt gets it wrong. People talk about debt-to-GDP ratios as if they're the meaningful metric. For Argentina, the more critical problem is currency mismatch. A substantial portion of the debt is denominated in US dollars while government revenue is in Argentine pesos. When the peso depreciates, the real burden of the debt increases regardless of whether the nominal amount changes. This isn't a theory, it's what happened repeatedly throughout the 1980s, 1990s, and most recently between 2018 and 2023 when the peso lost well over half its value against the dollar. Argentina does have some domestic-currency debt and some inflation-linked bonds that provide a partial hedge, but the mismatch remains structural. The central bank's attempts to manage this through reserve accumulation have repeatedly failed because the fiscal deficit keeps requiring new borrowing, which increases the debt stock faster than reserves can grow. It's a circular problem with no clean solution inside the current framework.
What Actually Happens in a Restructuring
A sovereign debt restructuring isn't a single event, it's a process that unfolds over years and involves multiple negotiating tracks simultaneously. The Paris Club of official bilateral creditors negotiates terms separately from private bondholder committees. The IMF doesn't directly negotiate restructuring terms but its standby arrangements or extended facility programs create the financing floor that makes a restructuring possible in the first place. The timeline typically works like this. First, the government announces it can't service its obligations and declares a selective default or formal restructuring. Then it forms creditor committees, usually one for bondholders under New York law and another for any domestic or Paris Club creditors. Valuation of claims happens next, which is where the bond math gets complicated because you have to account for accrued interest, make-whole provisions, and the specific terms of each bond issuance. Finally, there's a vote where bondholders decide whether to accept the new terms, usually requiring a supermajority under the collective action clauses that were added to most sovereign bonds after the 2001 default to prevent holdout behavior. The 2020 deal required approval from about 75 percent of bondholders by face value, and it passed. But the path to that vote involved distributing draft terms, running legal review across multiple jurisdictions, and negotiating amendments that were acceptable to both the government and the committee's legal counsel. Each amendment round took about two to three weeks. The whole process from announcement to exchange completion took roughly fourteen months.
The Inflation Index Complication
Argentina's CPI data has been subject to repeatedmethodological disputes and accusations of manipulation, particularly during periods when inflation ran well above official figures. This creates a direct problem for the growth bonds issued in the 2020 restructuring, since their coupon payments are tied to GDP growth but the underlying economic data used to verify that growth is itself disputed. Creditors have little recourse when the government reports a GDP figure that they consider artificially suppressed. In practice, this means the growth bond mechanism, which was supposed to align creditor and debtor incentives, may not function as designed if the data trust is broken. The workaround that some analysts have suggested is using independent inflation and growth estimates from sources like the Blue Dollar exchange rate implicit inflation proxy or IMF staff reports, but these aren't contractually binding for coupon calculations.

What the Current Situation Looks Like
As of early 2024, Argentina had emerged from the 2020 restructuring but was carrying a debt service burden that consumed a large share of export earnings. The country had regained partial access to international capital markets after the holdout litigation was resolved, issuing new bonds in late 2023. The macro environment has remained volatile with alternating periods of capital controls, multiple exchange rates, and ongoing negotiations with the IMF over the remaining standby arrangement balance. The key risk going forward isn't another outright default in the traditional sense, it's a gradual erosion of debt sustainability through persistent currency depreciation and inflation that makes the real value of obligations heavier each year without a formal restructuring event. That's a slower and in some ways more damaging path than a sudden default because it compounds quietly and gives creditors less warning. If you're looking at this from an investment angle, the main thing to track is the spread between Argentina's Brady bonds and comparable emerging market issuers, the IMF disbursement schedule, and the evolution of the parallel exchange rate premium. Those three indicators together tell you more about debt sustainability than any headline debt-to-GDP figure the government publishes.