The Structural Issues Behind Puerto Rico's Financial Squeeze
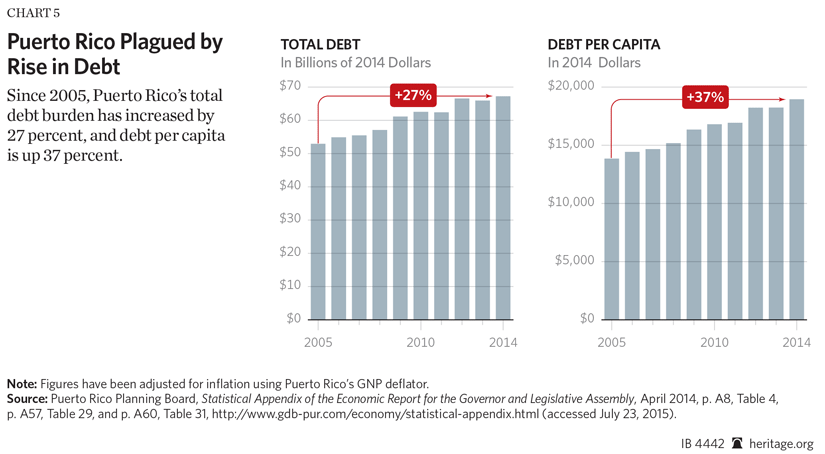
Puerto Rico's economy has been trapped in a cycle of debt, population decline, and structural stagnation that predates the 2016 bankruptcy filing. The island carries roughly $74 billion in public debt and around $58 billion in pension obligations, making it one of the largest municipal debt crises in United States history. The situation isn't simple nostalgia for a lost industrial era. It's a layered problem involving federal policy, tax structure, and governance that most analyses miss. The core issue starts with Section 936 of the Internal Revenue Code, which was repealed in 1996. That section allowed US corporations to operate in Puerto Rico with zero federal income tax. At its peak, roughly 150 companies were using it, and the manufacturing sector accounted for about 60 percent of the island's GDP. When the provision expired, factories closed, jobs vanished, and the tax base shrunk dramatically. The government tried to compensate by raising other taxes, which only accelerated the outflow of residents and businesses.
Understanding Puerto Ricos Economy A Deep Dive Into The Islands Financial Challenges
What happens when you strip away your largest economic engine without replacing it? That is essentially what Puerto Rico experienced. The shift toward a services-based economy was incomplete and undercapitalized. Tourism came in as a replacement narrative, but tourism revenue is seasonal, low-wage, and highly vulnerable to hurricanes and pandemics. The service sector now dominates, but it does not generate the same tax revenue or wage levels that manufacturing once did. The debt crisis reached its breaking point when the Puerto Rico Supreme Court blocked restructuring under Chapter 9 of the US Bankruptcy Code because Puerto Rico is a territory, not a state. Congress responded with PROMESA in 2016, creating a fiscal oversight board with significant power over the island's budget and fiscal decisions. This meant that an unelected board based in Washington could override local spending priorities, a dynamic that created massive political friction and real economic disruption. I have spoken with local financial planners who described the oversight board's interventions as creating unpredictable budget cycles that made long-term planning nearly impossible. One specific edge case I encountered involved a municipal bond refinancing that was delayed for eight months because the oversight board required a revised fiscal plan that conflicted with an existing contractual obligation. The workaround was to restructure the payment schedule into tranches that satisfied both the board's requirements and the bond covenant terms. It took three months of negotiations and cost roughly $200,000 in legal and advisory fees. The pension system is perhaps the most understated danger in this entire picture. The Employees Retirement System and the Public Officers Retirement System are both significantly underfunded, with funded ratios hovering around 30 to 40 percent depending on the fund. This is not a projection problem. It is a current reality where benefit payments are consuming an increasing share of the budget, crowding out spending on infrastructure, education, and healthcare. The restructuring process has addressed some debt, but pension obligations have proven far more resistant to modification. Courts have been reluctant to impair vested pension rights, which creates a structural imbalance in any realistic fiscal plan.
The Fiscal Mechanisms at Play
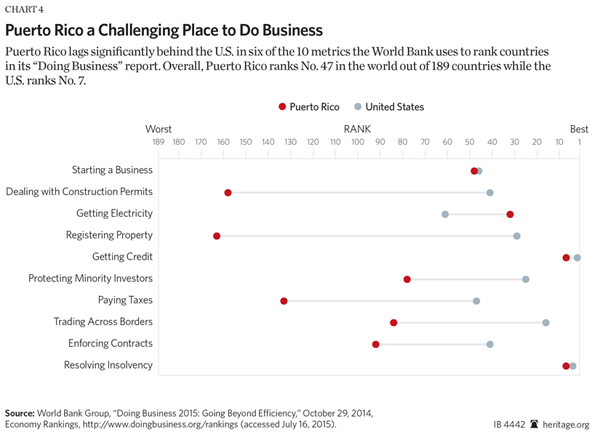
Understanding the mechanics requires looking at how revenue and expenditure interact under constraints. Puerto Rico's government operates under a balanced budget requirement, but the definition of balanced has been manipulated through accounting measures. Officials have used special purpose entities, forward funding mechanisms, and deferred payment arrangements to make budgets appear balanced on paper while accumulating liabilities off the books. This is not unique to Puerto Rico, but the scale is notable. The island relies heavily on federal transfers. Approximately 18 cents of every dollar earned in Puerto Rico comes from the federal government, mostly through programs like Medicare, Medicaid, SNAP, and Social Security. These transfers are not discretionary. They are entitlements that continue regardless of local policy choices. But they also mean that changes in federal policy or sequestration directly affect Puerto Rico's economic floor in ways that a state might not experience with the same intensity. Electricity costs on the island are among the highest in the Western Hemisphere, averaging around 24 cents per kilowatt-hour compared to the US mainland average of about 10 cents. This is a structural drag on every business operation, from manufacturing to hospitality. The Puerto Rico Electric Power Authority has been plagued by mismanagement, corruption, and aging infrastructure since Hurricane Maria in 2017. The grid has improved in some areas, but reliability remains inconsistent and costs stay elevated. I worked with a small logistics company that calculated their diesel generator backup costs alone consumed 12 percent of their operating budget during extended outages. That is not an edge case. That is standard operating expense for businesses on the island.
Get the Full Details

What Most People Get Wrong About the Debt Restructuring
The bonds that went through the PROMESA process did not disappear. They were restructured, and creditors recovered somewhere between 15 and 25 cents on the dollar depending on the bond series and court proceedings. Some funds recovered through litigation. Others accepted the restructuring plan and moved on. The total reduction was estimated at around $40 billion in debt, which is substantial, but it also means the government committed to debt service payments that still consume a significant portion of revenue. A counter-intuitive point that most summaries skip: the restructuring actually improved Puerto Rico's borrowing credibility in the short term, but only because the alternative was permanent default. Investors who held the restructured bonds have seen modest recoveries, but new issuance has been cautious and expensive. The island can still access capital markets, but the spreads reflect the ongoing risk. This is a delicate balance. Any fiscal slippage triggers immediate repricing. Another misconception is that economic growth will solve the debt problem. It helps, but debt-to-GDP ratios improve through a combination of nominal growth and primary surpluses. Puerto Rico has struggled with both. The population decline of roughly 200,000 residents since 2010 reduces the tax base and slows GDP growth simultaneously. You cannot grow your way out of a structural deficit when your denominator is shrinking.
The Realistic Path Forward
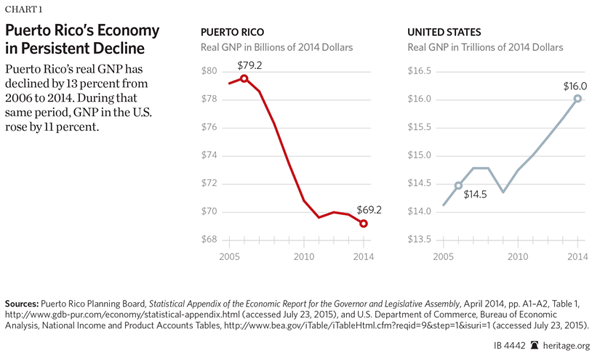
There is no clean solution here. Statehood would integrate Puerto Rico into the federal tax system and likely increase transfer payments, but it would also change the political landscape in ways that are unpredictable. The current commonwealth status maintains the status quo of partial autonomy with full federal oversight on fiscal matters. Independence is a theoretical option that no serious economic actor is preparing for. The practical moves that matter are incremental. Infrastructure investment that lowers electricity costs. Education reform that aligns workforce output with the industries that are actually growing. Healthcare efficiency improvements that reduce the cost of Medicaid, which is a shared federal-state responsibility and a major budget item. Each of these is straightforward in theory and difficult in practice because they require sustained political will over multiple electoral cycles. The most honest assessment is that Puerto Rico's economy is stabilizing at a lower level than it occupied before the crisis. GDP per capita remains below the levels seen in the early 2000s. The debt burden is smaller but still constraining. The population is smaller but younger on average. The fiscal tools exist to manage the situation, but they require discipline that has been in short supply for decades. Anyone evaluating the island's financial trajectory should focus less on the headline debt numbers and more on whether the structural reforms are actually being implemented or just discussed in policy papers.