Understanding Vehicle Loan Rates and How to Find Affordable Financing
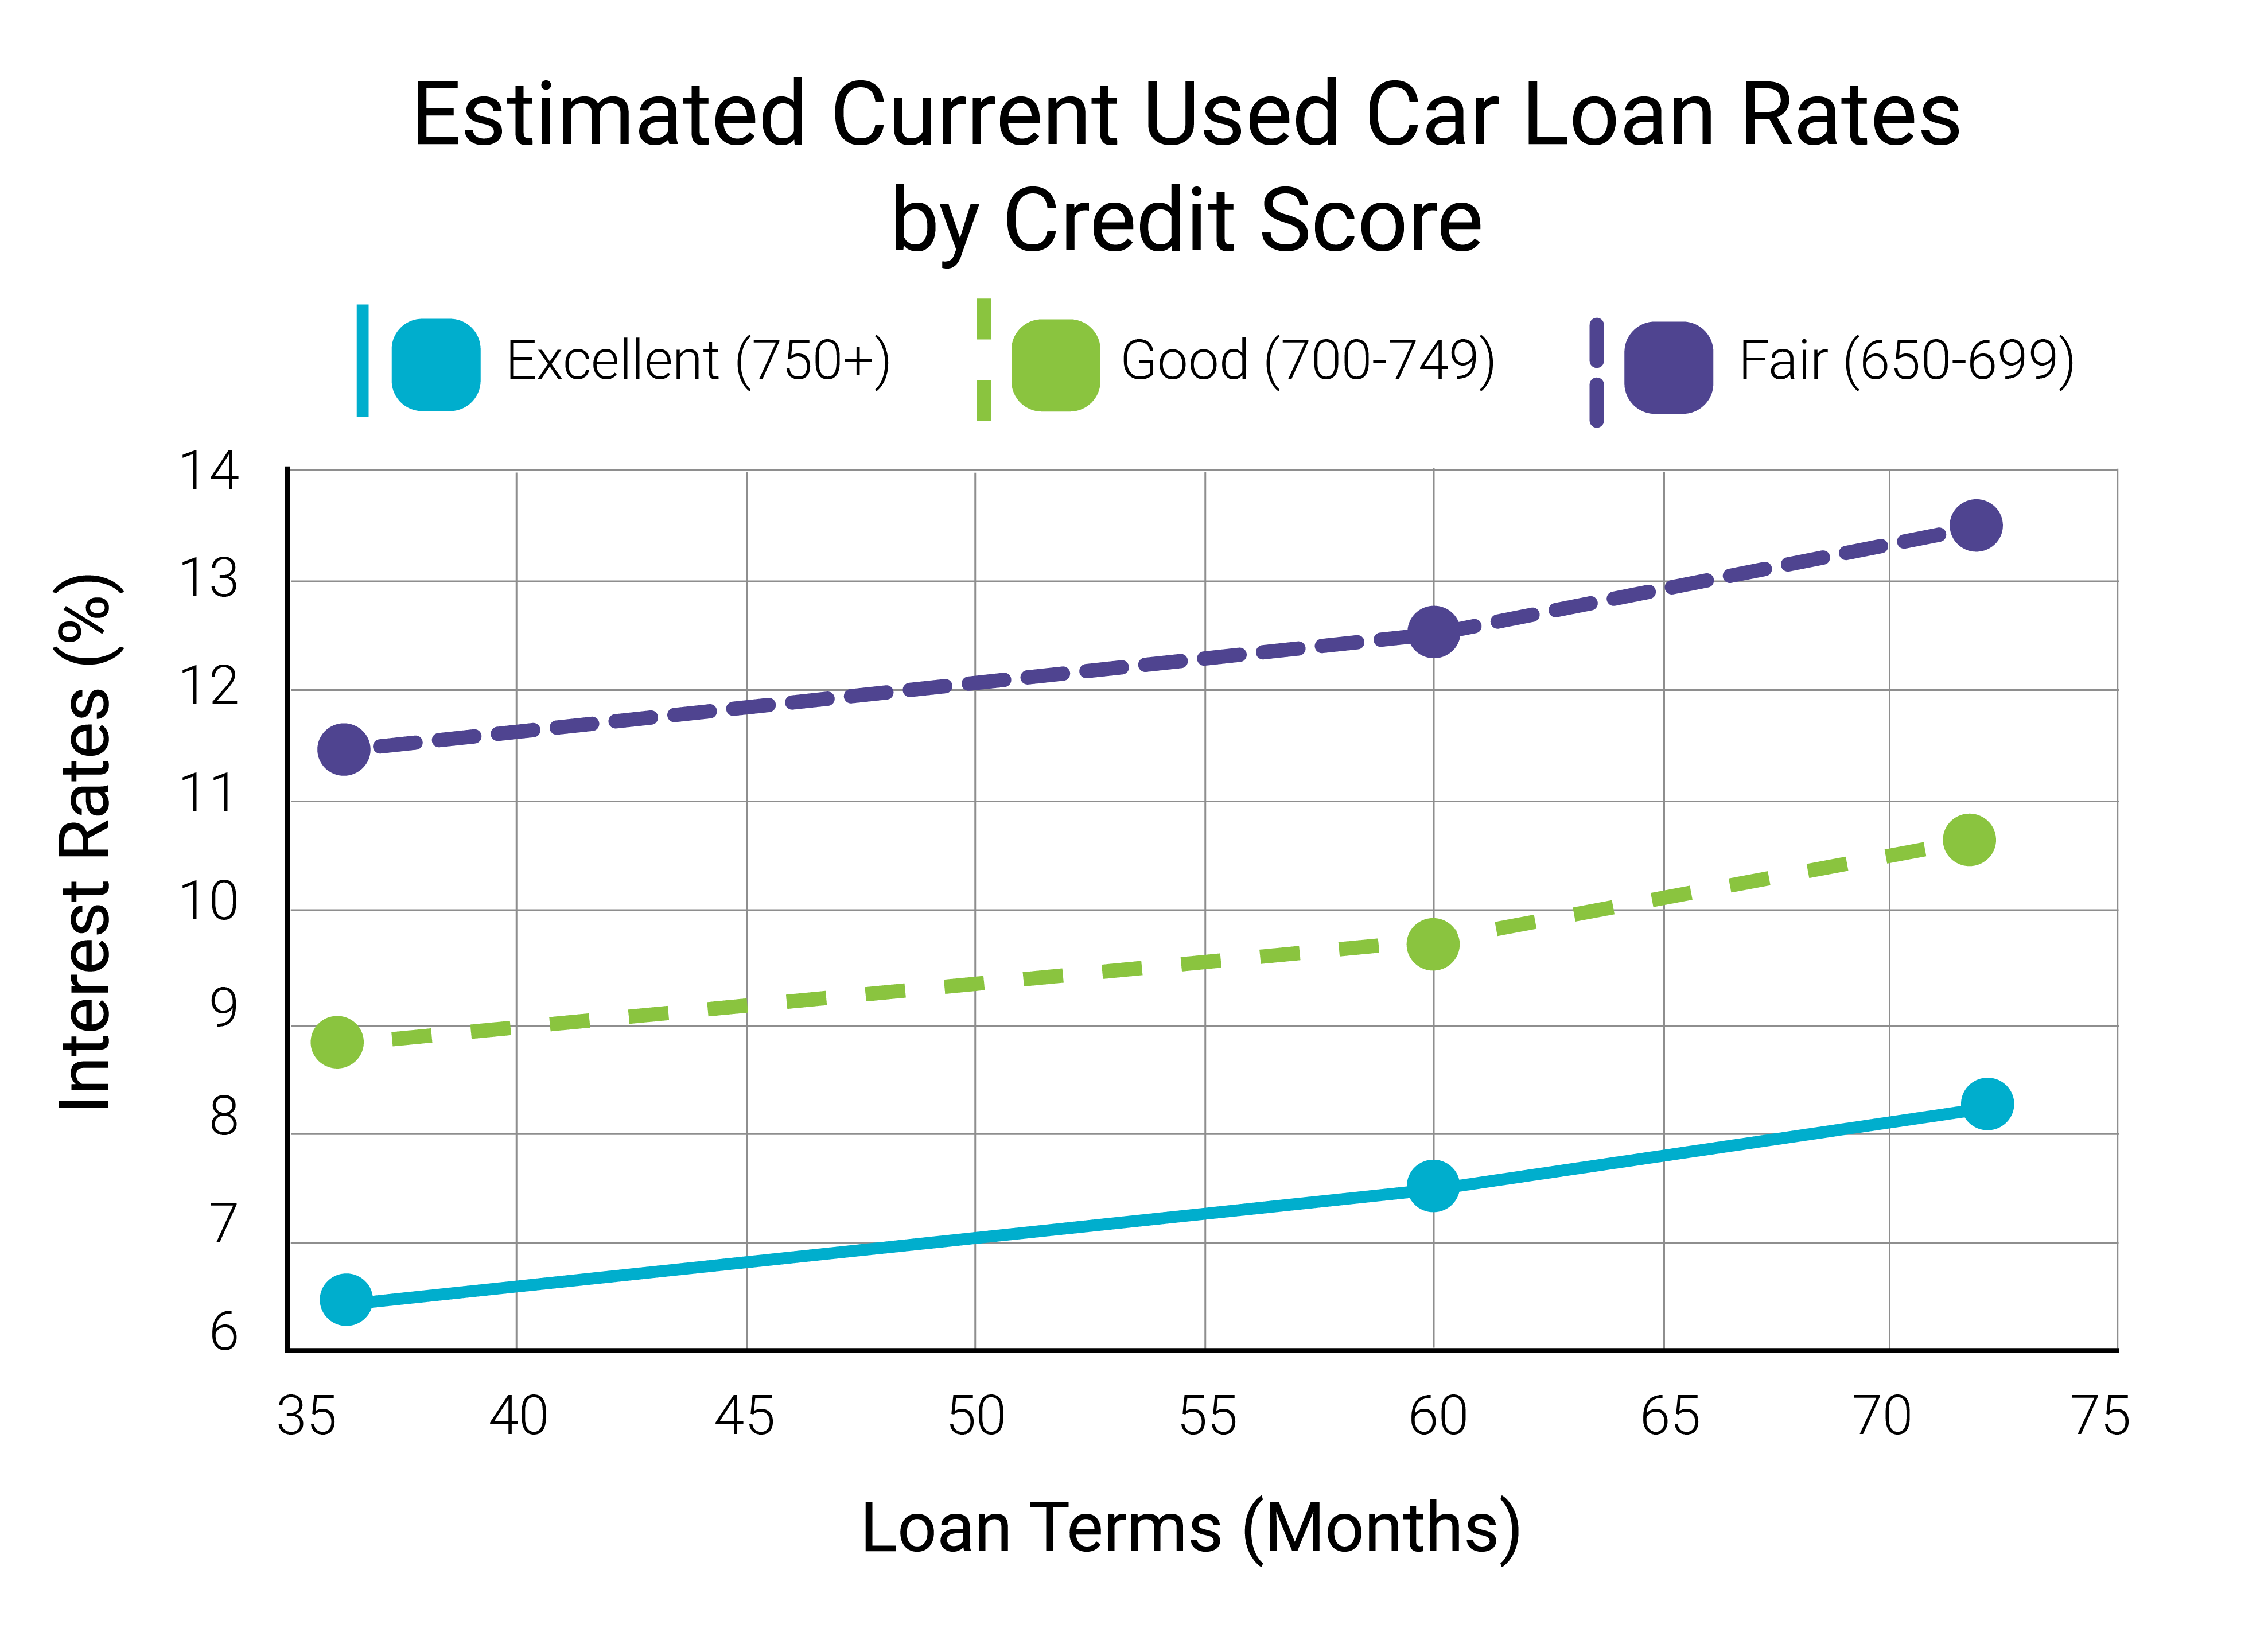
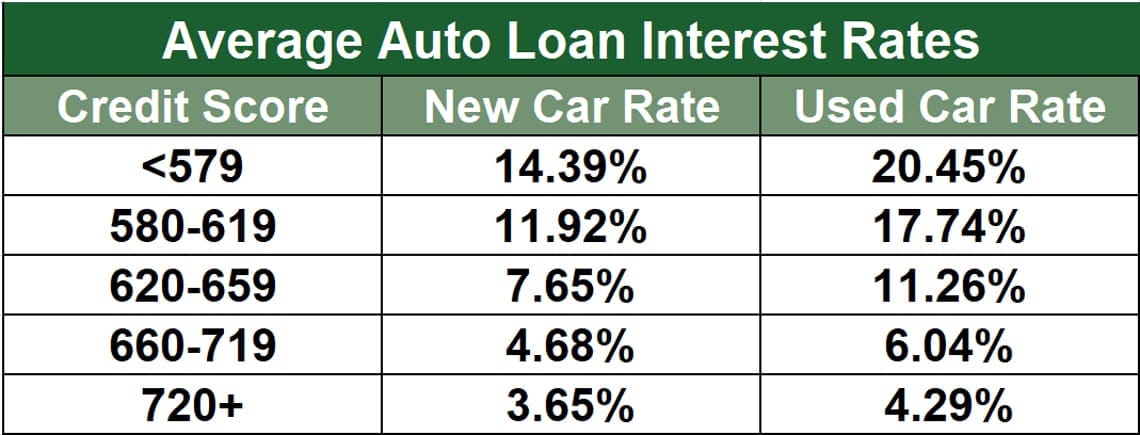
When you're shopping for a car loan, the numbers on the page don't always tell the full story. Interest rates vary wildly depending on your credit score, the lender, the loan term, and where you live. I spent years working in auto lending, and I can tell you that most people overpay by thousands without realizing it. Here's what actually matters. This resource aggregates rate data from multiple lenders and helps borrowers compare options side by side. The value isn't in having a single number — it's in seeing the range. A five-point spread on a $25,000 loan over six years is roughly $4,200 in total interest. That's real money sitting on the table if you pick the first rate you see. I've seen borrowers walk away with rates 2-3% higher than they qualified for simply because they didn't check. The workaround is straightforward: run your numbers through the calculator, note your top three rate offers, then take the lowest one to your local credit union or bank and ask them to beat it. Most will. I had a client once who used a comparable rate quote to get his credit union to shave 0.75% off an already decent rate. That alone saved him over $800 over the life of the loan.
Here's the part nobody mentions. Your debt-to-income ratio matters more than your credit score in some lending tiers. I processed a loan for someone with a 680 credit score and a 31% DTI who got a better rate than a borrower with a 720 score and a 45% DTI. The lender saw payment capacity and rewarded it. Check your DTI before you shop. Pull your recent pay stubs, add up all monthly debt obligations, divide by gross monthly income, and you'll know where you stand. Loan terms also distort what looks like a good deal. A lower monthly payment doesn't mean a better loan. Extend a 60-month loan to 84 months and your payment drops, but your total interest cost balloons. I reviewed a situation where a borrower took an 84-month loan at 5.9% versus a 60-month at 6.4%. The monthly savings looked nice, but the total interest paid was $2,100 more. The rate difference was only 0.5%, yet the term difference cost significantly more. Always calculate total cost, not just the monthly number. The tool itself has limitations. It pulls from a snapshot of lender rates that may not reflect your exact profile. If you have recent late payments, a bankruptcy, or a thin credit file, the displayed rates will be optimistic. The best use of this guide is as a baseline — something to measure your actual offers against, not as a final answer. I recommend getting pre-approved from at least two lenders before relying on any calculator output. The pre-approval locks in a rate and gives you a concrete number to compare.
One practical step most people skip: check whether the lender charges origination fees or prepayment penalties. A rate that's 0.25% higher but has no fees can end up cheaper than a slightly lower rate with a $500 origination charge. Run the total dollar cost, not just the percentage. The calculator may not factor in every fee type, so request a full disclosure document from each lender before signing anything.
Get the Full Details
What Actually Moves the Needle on Your Rate
Credit score improvements take time, but there are faster levers. Making a larger down payment reduces the lender's risk and typically drops your rate tier. Putting 20% down instead of 10% can move you from a subprime bracket into a prime bracket with the same credit profile. If you have savings available, that's usually the highest-return move you can make before you walk into a dealership. Co-signing is another option, but it's a double-edged sword. The co-signer's credit history gets pulled into the decision, which can improve your rate significantly. However, the co-signer is equally responsible for the debt, and any missed payment hits their credit too. I've watched relationships fracture over auto loans because the borrower assumed the co-signer wouldn't notice the late payment notices. They do notice. Shop within a focused window. Rate inquiries within a 14-to-45-day period are typically treated as a single hard pull by FICO scoring models, so you can compare multiple lenders without taking repeated credit score damage. Space them out too far and each inquiry counts separately. I once had a borrower who checked rates over three separate weekends across two months and lost nearly 10 points from the accumulated inquiries. One concentrated weekend of shopping would have cost nothing.
The guide is useful for understanding what's available, but the real work happens before and after you lock a rate. Read the loan documents carefully. Verify the APR matches what was quoted. Confirm the payment amount, term length, and any balloon payment structure. Lenders rarely error on your behalf, and when they do, it takes more time to fix than to prevent upfront.