Auto Loan Rates Right Now
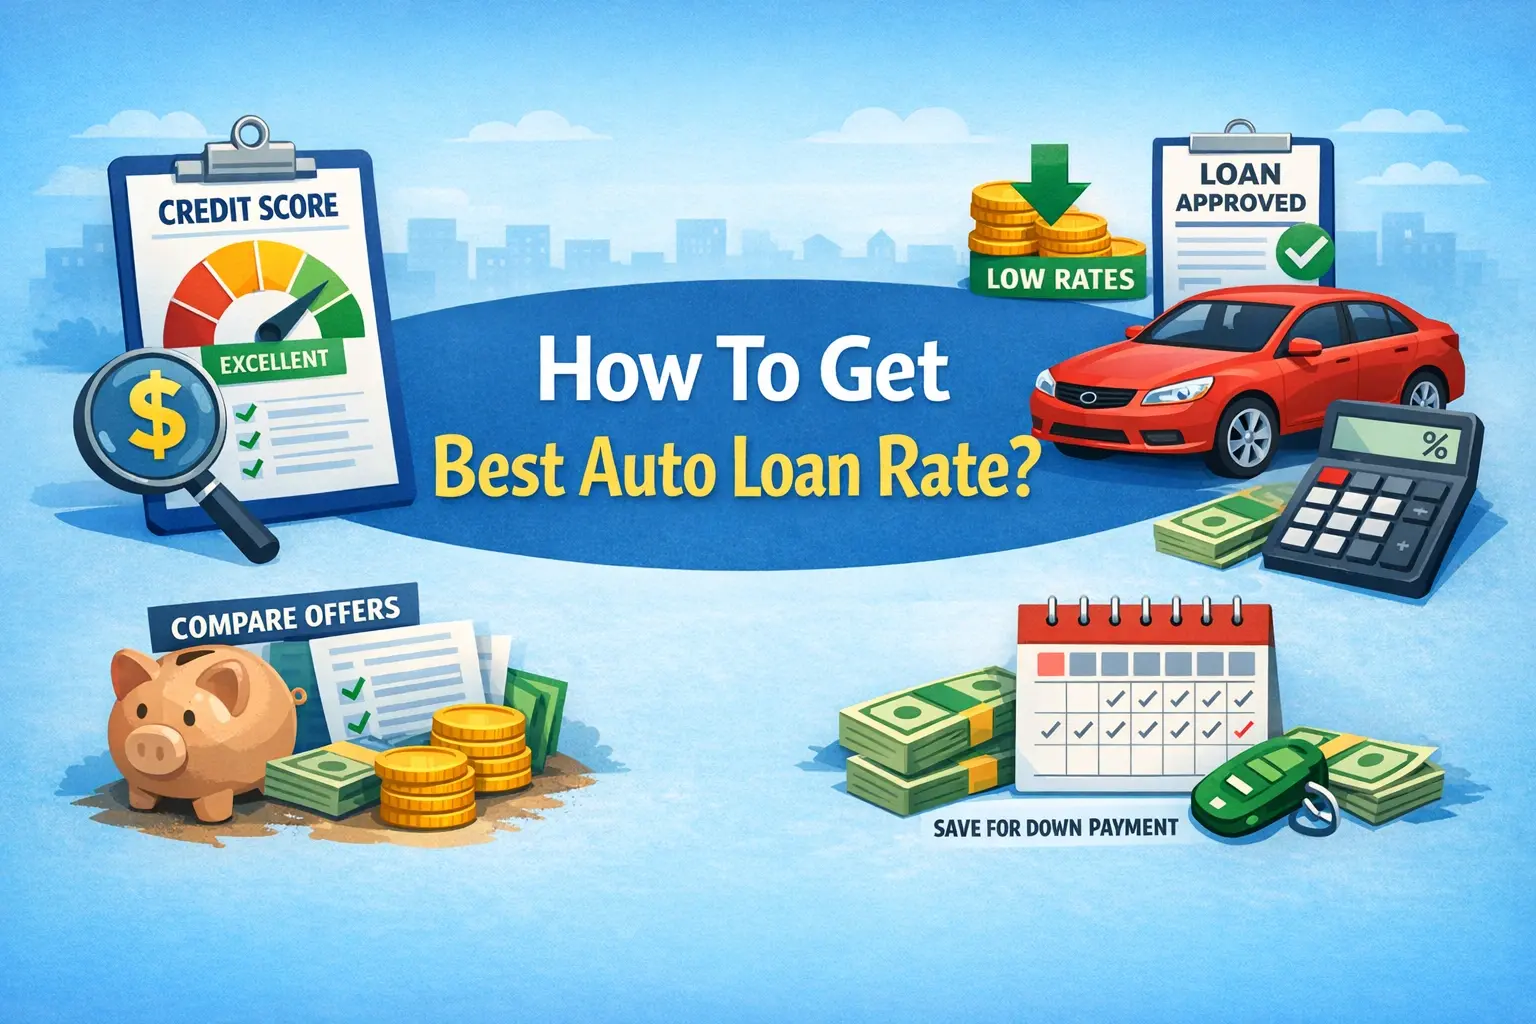
The market shifted again this year. Rates that looked generous at the start of 2025 have tightened considerably, and a lot of people walking into dealerships are getting quoted numbers that don't match what they saw online. I've been watching this space for over a decade, and the pattern is familiar. Lenders advertise one rate, approve you for another, and the final number depends almost entirely on how well you've prepared before you ever sit across from a finance manager. When I look at reviews for Psecu auto loan rates, the good and the bad tend to cluster around the same issues. Some borrowers report straightforward approvals with competitive rates for strong credit profiles. Others ran into delays, unclear fee structures, or rate quotes that didn't hold up by the time paperwork got signed. That second group usually didn't do one thing: they didn't lock their rate before shopping around. Rate locks expire, and Psecu, like most lenders, will honor the locked rate only if you close within the lock period. Miss that window and you're back at whatever the current desk rate is. Here's what I've found works in practice. First, check your credit report yourself. Not just the score, but the actual lines. One inquiry that shouldn't be there, one account showing late payments when you know they were on time — those details move the needle more than most people realize. Pull your reports from annualcreditreport.com or through your bank. Dispute anything that looks wrong before you apply. The dispute process takes longer than the loan application, so do it early.
Second, get prequalified with two or three lenders. Not just Psecu. Prequalification is a soft pull and gives you a baseline. When you walk into a dealership or a credit union with a prequalification letter in hand, you have leverage. The finance manager can't bluff you as easily when you already know what the market is offering. Third, read the fine print on the rate quote. Is it a purchase rate or a refinance rate? Those are different products with different terms even when the percentage looks identical. I once saw a borrower who got quoted 5.9 percent and celebrated. The fine print said that was a refinance rate, not a purchase rate, and the actual auto loan rate for their profile came in at 7.4 percent. They wasted a week going back and forth before someone caught it. The biggest misconception I see people make is assuming the advertised rate is what they'll actually pay. Advertised rates are usually the lowest tier, reserved for the top credit brackets. If your score is in the 700 range instead of the 760 range, you're probably looking at a rate that's a full point or more above what's on the landing page. That's not deceptive, exactly. It's just how pricing tiers work. But knowing it upfront saves you from feeling misled later.
What Actually Happens During Approval
The approval process at most direct lenders — Psecu included — runs through an automated decision engine first. You submit your information, the system pulls your credit, verifies employment and income through third-party data sources, and spits out an initial decision within minutes if everything checks out. That initial decision isn't final. It's a preliminary qualification. The final underwriting review happens after you've signed the purchase agreement and the lender pulls a fresh credit report, confirms the vehicle details, and checks the title status. This is where people get tripped up. Between the preliminary approval and the final sign-off, your financial situation can change. A new credit inquiry, a large purchase on a credit card, a job change — any of that can flip a conditional approval to a denial. I had a borrower last year who got conditionally approved at 6.2 percent, then maxed out a $3,000 credit card for furniture before closing. The final credit pull showed the new debt-to-income ratio and the rate jumped to 8.1 percent. The lender didn't deny the loan entirely, but the cost went up significantly. He called me annoyed, and I told him the hard truth: don't touch your credit between approval and closing. Period. No new accounts, no large purchases, no balance transfers. If you're working with a dealer rather than applying directly, the process gets murkier. The dealer submits your application to multiple lenders through their wholesale network. You might get three offers, each from a different lender, each with different rates and terms. The dealer's mark-up on the rate, known as the dealer reserve, is legal in most states but it's not something most borrowers negotiate against effectively. The dealer gets a spread between the rate the lender offers and the rate you're quoted. That spread is where the dealer makes extra profit on the financing side.
Get the Full Details

How to Negotiate the Rate
Negotiating an auto loan rate isn't the same as negotiating a car price. You can't really haggle over interest rates the way you haggle over a sticker price. What you're actually negotiating is the rate the lender offers you, and that depends on three things: your credit profile, the lender's current appetite for risk, and how much competition you're creating between lenders. So you create competition. Get written rate quotes from at least three sources before you go to the dealership. A credit union, a direct online lender, and a bank. Compare the annual percentage rates, not just the interest rates. The APR includes fees and gives you a truer picture of what the loan actually costs. Bring those quotes with you. When the finance manager gives you their offer, ask them to beat the best quote you have. Most of the time they will, because they want the sale. Sometimes they won't, and in that case you can walk away and use the quote you already have. One counter-intuitive thing about auto loans: a shorter loan term often comes with a lower rate. Sixty-month loans carry higher rates than thirty-six-month loans at many lenders, even though you're borrowing the same amount. The risk profile is different in the lender's model. Shorter terms mean the loan gets paid off faster, and the model prices that lower risk as a lower rate. The monthly payment is higher, but the total interest paid is often less than a longer-term loan at a seemingly lower rate. Run the numbers both ways before you commit to the term length.
Where People Lose Money
Add-on products. Gap insurance, extended warranties, key fob replacements, paint sealants — these get pushed during the finance process and they inflate the total loan amount. Every dollar added to the principal earns interest for the life of the loan. A $800 gap insurance policy at a 7 percent rate over 60 months costs you roughly $830 in total. Not catastrophic on its own, but these products stack up fast. Most of them are also available cheaper elsewhere. Your homeowner's or renter's insurance might already cover gap. Credit unions often sell gap insurance for half the dealer price. You don't need to accept everything they offer at the desk. Pre-paid interest is another one. Some loans front-load fees into the interest calculation, making the effective rate higher than the quoted rate. Always calculate the total cost of the loan — total of all payments plus fees — and compare that across offers rather than just looking at the monthly payment. A lower monthly payment can hide a much higher total cost if the term is extended or the rate is inflated behind the scenes.
When Psecu Might Not Be the Right Choice
Psecu works well for borrowers with solid credit and straightforward applications. Their online process is streamlined, and the customer service is generally responsive based on the volume of positive reviews. But they're not ideal if you have thin credit files, recent bankruptcies, or if you're buying from a dealer who isn't part of their direct lending network. In those situations, their automated system might decline you or offer terms that aren't competitive. If your credit is below 640, you're better off working with a credit union that does manual underwriting or a subprime specialist lender. They'll charge more, but they'll actually approve the loan instead of leaving you to guess why you got declined. If you're buying from a dealer outside Psecu's network, shop for a pre-approval from another source first, then bring it to the dealer. The dealer will often match or beat an outside offer because they still make money on the vehicle sale even if the financing margin is thinner. The bottom line is that the best rate you get depends on preparation, not luck. Check your credit, gather quotes, understand what you're being offered, and don't let the pressure of the dealership environment rush you into accepting the first number on the table. The process takes an afternoon, not a whole day, and the difference a well-negotiated rate makes over the life of the loan is substantial enough to make the effort worthwhile.