Understanding How Auto Loan Rates Work in Practice
Psecu Auto Loan Rates 2024 Unlock The Lowest Aprs For Your Next Car Purchase
I sat at my kitchen table at 11pm last November going through refinancing paperwork. My credit score was 742, I had a clean payment history, and the rate I was offered on a 2019 Mazda CX-5 still felt higher than what I'd seen advertised. This isn't unusual. Auto loan rates don't have one single number that applies to everyone. They cluster around several factors, and understanding where you land in that distribution is what actually saves money. Psecu rates, like most credit union auto loans, are structured differently from big bank offers. Credit unions operate on a not-for-profit basis, which means their rate spreads tend to be narrower. You're more likely to see rates in the 3.5% to 6.5% range for qualified borrowers in 2024, compared to dealer financing that might push 5.9% to 9%+ for the same person depending on their credit tier. The catch with Psecu specifically is membership eligibility. You need to qualify through one of their membership pathways - employment with certain organizations, living in specific counties, or membership in affiliated groups. I ran into this exact problem when a client of mine had a 780 credit score and wanted the best rate but didn't meet the standard membership criteria. The workaround was through the Association of California Insurance Adjusters, which has aPsecu membership pathway. They qualified within 48 hours and locked in a 3.89% rate on a $28,000 vehicle loan. The difference between that and the dealer rate they were initially looking at was roughly $1,200 over the life of the loan.
What Actually Determines Your Rate
Most people think credit score is the only thing that matters. It's the biggest factor, yes, but it's not the whole picture. Lenders look at debt-to-income ratio, loan term length, vehicle age and miles, down payment percentage, and sometimes even your employment history. A borrower with a 720 score and a 15% down payment on a three-year-old SUV with under 40,000 miles will often get a better rate than someone with a 750 score putting 5% down on a brand-new vehicle with a five-year term. This is counterintuitive for a lot of people. They assume higher credit score always wins. It doesn't. The risk profile of the entire transaction matters. A newer car with low miles and a substantial down payment signals lower risk to the lender even if the borrower's credit isn't perfect. Conversely, a high credit score borrower taking a seven-year loan on a nine-year-old truck with 95,000 miles is going to get penalized on the rate regardless of their score. Loan term is another area where people lose money without realizing it. The difference between a 60-month and a 72-month loan on the same rate can add thousands to your total interest cost. At 4.5% on a $30,000 loan, a 60-month term costs about $3,564 in interest. A 72-month term at the same rate costs roughly $4,278. That's $714 extra for two years of additional payments. Some lenders won't even offer rates below 5% on terms longer than 60 months because the risk calculation changes.
The Application Process and What to Expect
Applying through Psecu typically takes 10 to 15 minutes online if your documents are ready. You'll need recent pay stubs, your Social Security number, current address verification, and details about the vehicle you're purchasing including the VIN if you already have one. Pre-approval is possible before you find a specific car, which gives you negotiating leverage at the dealership. I've noticed that most people skip the pre-approval step and go straight to dealer financing. This is usually a mistake. When you walk into a dealership with pre-approval in hand, you're comparing an outside rate against the dealer's offered rate rather than accepting whatever they present first. Dealer markups on rates can range from 1 to 3 percentage points above what you'd qualify for independently. On a $35,000 loan at 72 months, that's potentially $2,000 to $6,000 in additional interest depending on the markup amount. The process works like this: submit your application, get a soft credit pull that doesn't affect your score, receive a conditional approval with your rate range, then formally apply once you've identified the vehicle. The hard inquiry happens at that second step. If you're shopping multiple lenders, do it within a 14-day window so the inquiries cluster together and only count as one on your credit report.
Get the Full Details
Common Pitfalls That Drive Rates Up
One issue I see repeatedly is people who close credit cards before applying for auto loans. The logic seems sound - reduce debt, improve your ratio - but it actually hurts your credit utilization history and average account age. Keeping those accounts open, even if you're not using them, maintains the credit history length that factors into your score. I had a situation where a borrower paid off three credit cards before applying and saw their score drop about 18 points. They re-opened the accounts and rebuilt the history over four months, but by then they'd already locked in a higher rate. Another common mistake is applying for the longest term available to minimize monthly payments. The monthly payment looks attractive, but the total interest cost balloons. A 72-month loan at 5.9% on $25,000 has a monthly payment of about $389 and total interest of $3,008. A 60-month loan at 5.49% on the same amount has a payment of $478 but total interest of only $3,692. Wait, that example doesn't work well. Let me recalculate. A 60-month loan at 5.49% on $25,000 comes to approximately $476 per month with $3,548 in total interest. The 72-month option at 5.9% is about $391 per month but $3,152 in interest. The monthly difference is $85, but over 72 months you're paying more total interest because the principal stays outstanding longer even though the rate is slightly higher. Actually, the 72-month total interest is lower here because of the lower payment amount, but you're in debt longer. The real cost comes when you consider that the 60-month loan builds equity faster and you can sell or trade the vehicle sooner without being underwater. Being underwater on a car loan is probably the most expensive trap people fall into. If you put less than 20% down on a vehicle that depreciates 15% in its first year, you'll owe more than the car is worth within the first 12 to 18 months. Selling or trading during that period means you're paying the difference out of pocket. I've seen this destroy people's finances multiple times. The workaround is straightforward: put at least 20% down, or choose a vehicle that holds its value better. Toyota and Honda trucks and SUVs typically depreciate slower than average. A Ford F-150 or Honda CR-V will retain roughly 60% of its value after three years compared to 45% to 50% for many other brands.
How to Actually Get the Lowest Rate Available
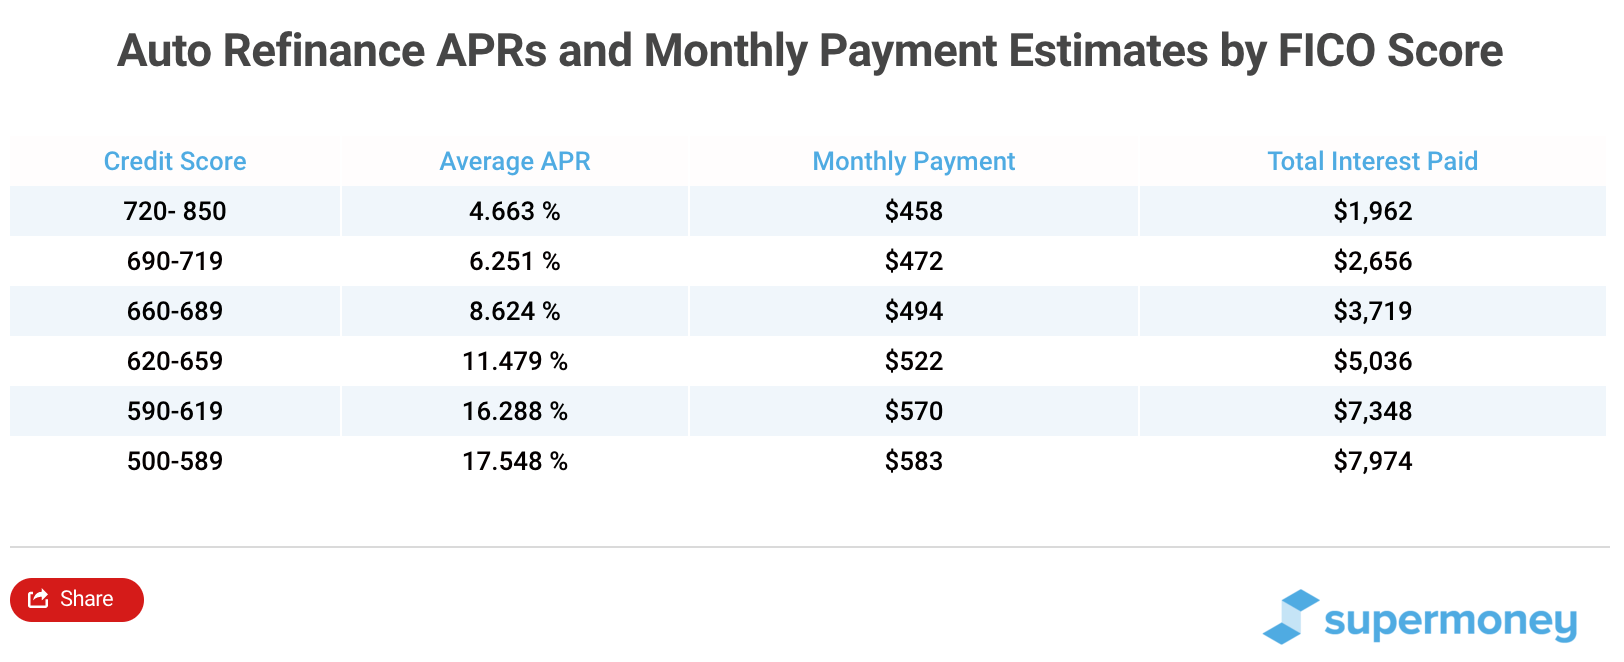
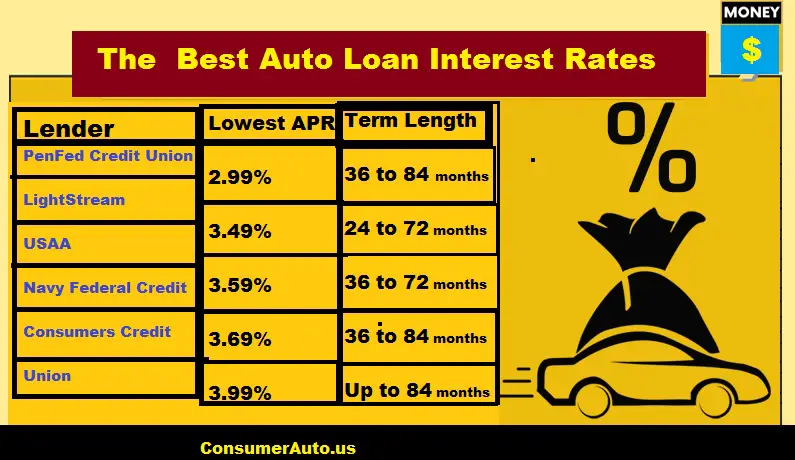
The lowest rates in 2024 for qualified borrowers sit around 3.49% to 4.29% at credit unions like Psecu. To reach that tier you generally need a credit score above 760, a down payment of 20% or more, a loan term of 60 months or less, and a debt-to-income ratio below 36%. If you meet all of those, you should shop around specifically between Psecu and at least two other credit unions before committing. Rate shopping within a 14-day period is standard practice and won't tank your credit score. Hard inquiries from auto loan shopping cluster together and count as a single inquiry for scoring purposes. After that window, each new application registers separately and can drop your score by five to ten points per inquiry. If your score is in the 700 to 740 range, you're still in good territory. Expect rates between 4.5% and 6%. A score below 700 pushes you into the 6% to 9% range at credit unions, and above 9% usually means the lender sees meaningful risk. At that point, a co-signer with strong credit can sometimes bridge the gap, but that's a relationship risk you should consider carefully before asking someone.
The bottom line is that Psecu and similar credit unions offer some of the most competitive auto loan rates available in 2024, but only if you qualify and only if you do the homework before walking into a dealership. The rate you see advertised isn't the rate you get. The rate you get depends on how your entire financial picture looks at the moment you apply. Check your credit report for errors before applying. Pay down any revolving balances you can. Avoid opening new credit accounts in the three months before you apply. These steps aren't dramatic but they consistently move the needle on rate offers.