Expense Ratios on PSE ETFs Are Not as Simple as They Look
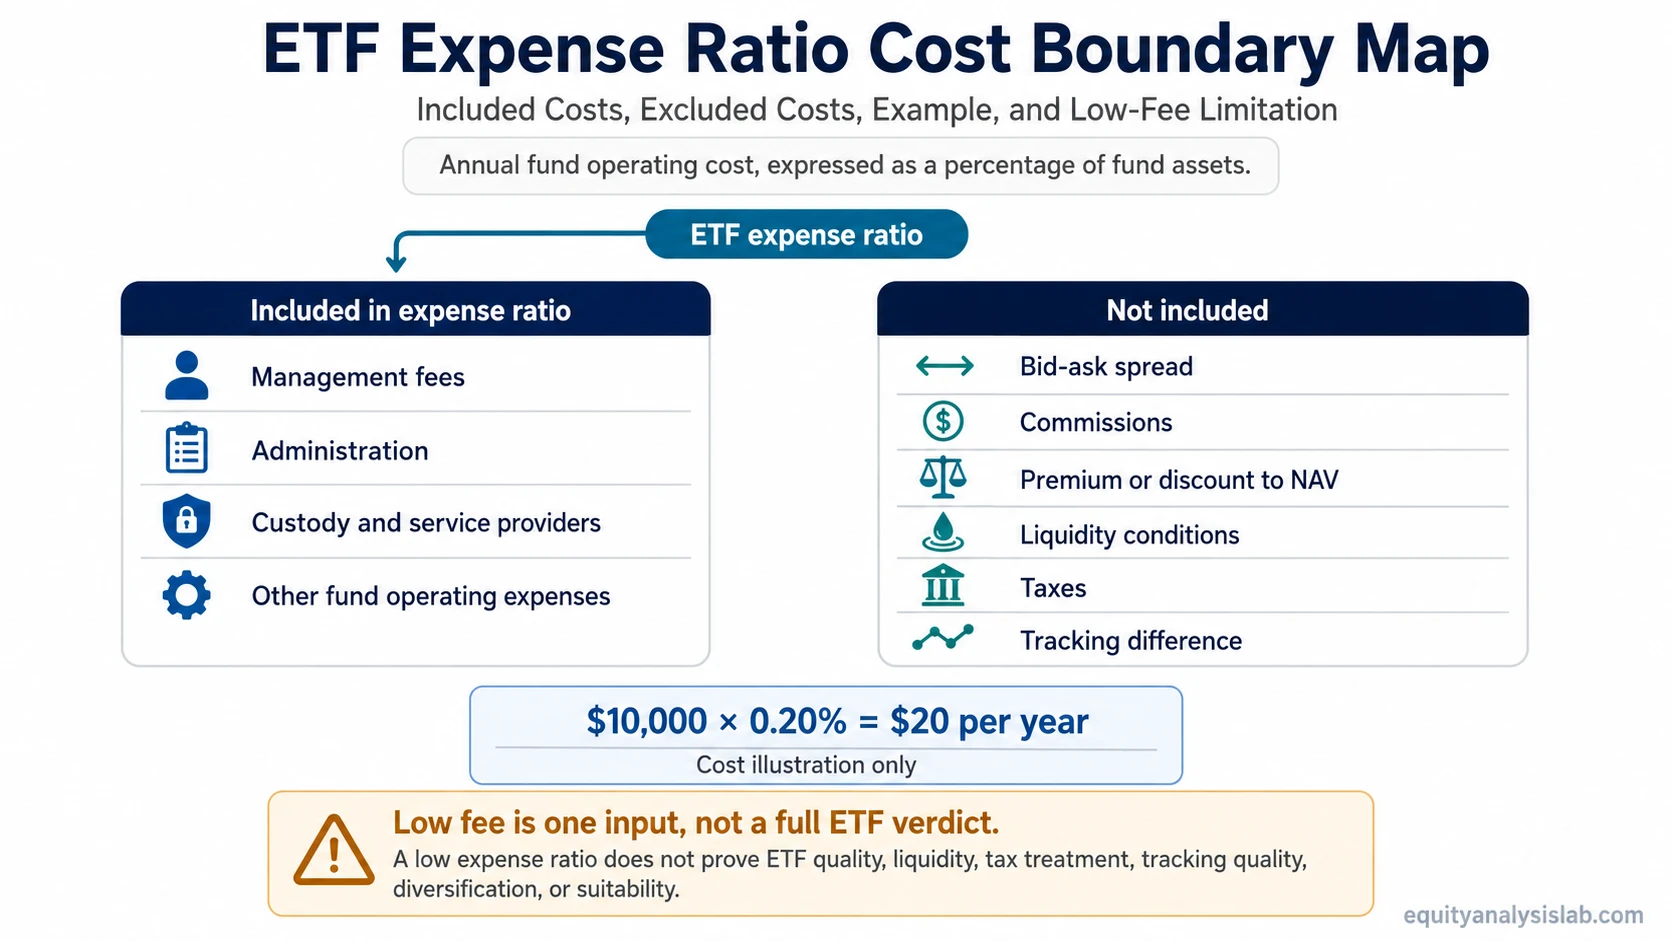
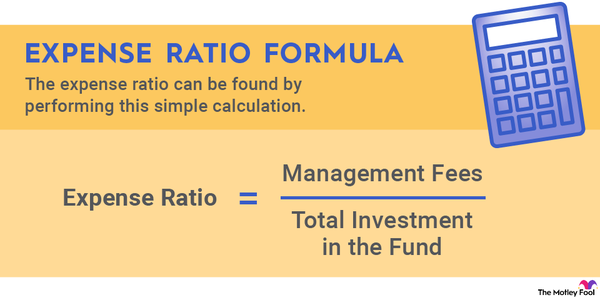
Most people assume the expense ratio on a Philippine Stock Exchange ETF is just a number you find on a fact sheet and move on. That assumption gets you into trouble fast. I opened my first PSE-listed ETF account in 2022 and spent about three weeks cross-referencing numbers before I realized the published expense ratio was not the full picture of what I was paying. Let me walk through what actually happens, because the official documentation leaves gaps that matter. An expense ratio is the annual fee an ETF charges for management, administration, and operational costs. It is expressed as a percentage of your average daily net assets. If you hold a PSE ETF with a 0.60% expense ratio and your position averages ₱100,000 over a year, you pay roughly ₱600 in fees. That is the textbook version. The real version includes stuff the fact sheet buries in small print or omits entirely.
Pse ETF Demystifying The Expense Ratio What You Need To Know
Here is the breakdown most retail investors on the PH market miss. PSE ETFs in the Philippines are managed by fund managers like BDO Asset Management, FMI Asset Management, UnionBank Asset Management, and others. Each product has a base management fee built into the expense ratio, but there are layered costs that vary by fund and by structure. The base fee is usually between 0.50% and 1.00% for most PH equity ETFs, while bond or balanced ETFs run slightly lower. What drives the spread is custody fees, trustee fees, audit costs, and the exchange listing fees that get rolled into the annual report figure. I encountered a specific problem that I did not see coming. In late 2023, I compared two similar PSE ETFs that both quoted an expense ratio around 0.75%. One was a broad market index fund tracking the PSEi, the other tracked a subset of dividend-paying stocks. The difference in what I actually paid came out to nearly 0.20% annually after I dug into the fund's semi-annual reports. The broader fund had higher trading costs baked into its operations because it rebalanced more frequently and held more positions with tighter liquidity. The narrower fund charged slightly more in pure management fees but saved on transaction friction. The published expense ratio told me almost nothing about which one would cost me more in practice. The workaround I used was straightforward. I stopped looking at the single expense ratio number and started pulling the actual fund reports from the asset manager's website. Every PSE ETF publishes semi-annual and annual reports that break down total operating expenses, gross fees, and net fees after any waivers. I added up the management fee, the trustee fee, the audit fee, and the custodian fee separately, then compared those line items across funds. This gave me a number that was usually 5 to 15 basis points higher than the headline expense ratio, depending on the fund. For a long-term holder, that gap compounds.
Another detail worth noting is that some fund managers occasionally waive part of their management fee to make a product look cheaper. A net expense ratio of 0.55% might become a gross ratio of 0.70% once you strip out the waiver. The waiver is temporary and can be removed without notice. I saw this happen with a mid-cap ETF in 2024 where the net ratio jumped from 0.55% to 0.68% after the manager decided the promotional period was over. If you bought based on the lower number, your effective cost increased with no warning. There is also the matter of trading costs that do not appear in the expense ratio at all. When you buy or sell a PSE ETF on the exchange, you pay a broker commission and a document stamp tax. Some brokers offer zero-commission ETF trades, but that is not universal. The stamp tax is 0.5% on the sell side for shares traded on the PSE, though ETFs have a different rate that is generally lower than regular stocks. You need to check with your broker because the rate depends on whether the ETF is treated as a equity security or a bond-like instrument for tax purposes. On a round-trip trade of ₱50,000, stamp tax and commission can add another 0.10% to 0.25% to your total cost, which dwarfs the difference between a 0.60% and a 0.70% expense ratio on a single trade. For investors who hold ETFs for years, the expense ratio is the cost that eats into compounding the most. I have seen people obsess over picking between two funds with a 0.05% difference in expense ratio while ignoring the fact that one fund has a wider bid-ask spread and the other requires a higher minimum position size to trade efficiently. A fund with a 0.65% expense ratio and tight spreads can be cheaper than a 0.55% fund that trades with a 0.30% spread. The spread cost hits you every time you enter or exit. The expense ratio hits you every day you hold.
Get the Full Details
If you want a practical way to evaluate PSE ETF expense ratios, do this. Download the latest annual report from the fund manager's site. Look for the section labeled "Operating Expenses" or "Total Expense Ratio." Add the management fee, trustee fee, audit fee, and any other operational cost listed. Compare the gross expense ratio to the net expense ratio and note whether any fee waivers are in effect. Then check the fund's trading data on the PSE website or your broker platform for average daily spread and volume. A fund with low expense ratio and low liquidity is a trap. A fund with reasonable expense ratio and high volume is where you want to be. I also found that the cheapest ETF is not always the right choice for your situation. A low-cost bond ETF might track an index that does not match your risk profile. A low-cost equity ETF might have concentration risk in a handful of stocks. The expense ratio is one input, not the entire decision. I learned this the hard way when I initially rotated into a low-fee sector ETF that had terrible exposure to a declining segment of the market. The savings on fees were irrelevant because the fund lost 12% in six months. The broader market ETF I switched to cost 10 basis points more but delivered far better risk-adjusted returns. One final point that deserves attention. The expense ratio on PSE ETFs is not static. Fund managers can change it, and they do. The Securities and Exchange Commission requires approval for material changes, but the process is not instantaneous. If a fund manager announces a fee increase, it usually takes effect at the next annual or semi-annual meeting of the board of trustees. Holders are notified, but the notice comes through circulars and announcements, not push notifications from your broker app. I recommend subscribing to the fund's updates or checking the PSE Edge announcements periodically so you are not blindsided by a sudden jump in your annual costs.