California Fair Plan basics
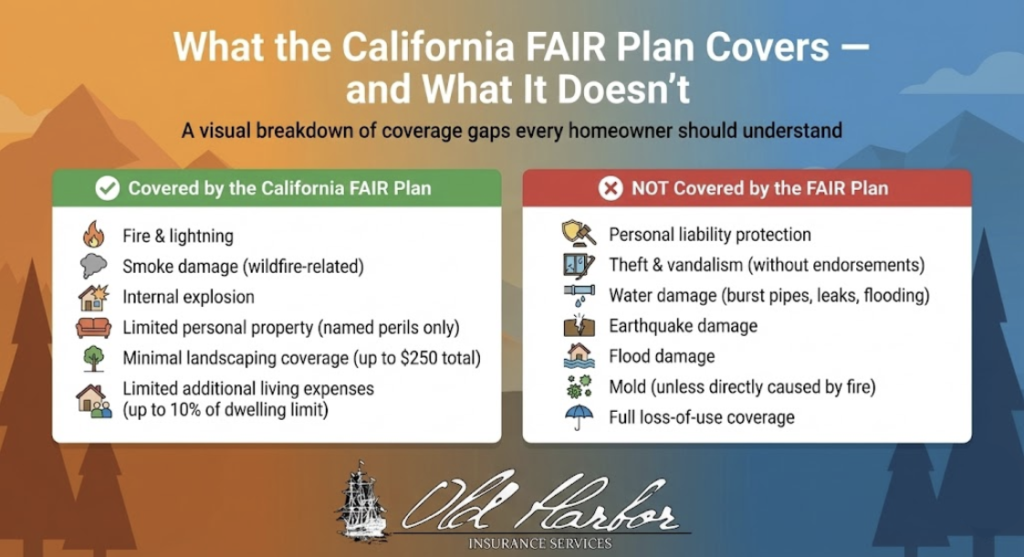
California Fair Plan is the state's residual market for property insurance. It exists because private carriers pulled back from writing high-fire-risk policies in certain zip codes. If your home qualifies, Fair Plan acts as an insurer of last resort. You don't need a prior denial to apply, but you do need to meet their eligibility thresholds, which are stricter than most people realize. The product itself is basic. It covers dwelling, attached structures, and personal property on a named-perils basis. Fire, lightning, internal explosion, and a few other perils make the list. Smoke damage is included. Windstorm and earthquake are NOT included unless you buy them as separate endorsements. Most homeowners I talk to discover that after their claim gets partially denied because they assumed coverage was broader than it actually is.
Protect Your Home Without Breaking The Bank California Fair Plan Insurance Made Simple
I've been working with wildfire-adjacent insurance for roughly a decade. What trips people up most is the premium calculation. Fair Plan doesn't use standard credit-based scoring. They use a blend of construction type, distance to the nearest fire station, roof material, and a fire hazard severity score tied to your specific address. The formula isn't published. Nobody outside the rating department sees it. Here is how I structure the application process. Step one is pulling your CLUE report before you even fill out the application. Fair Plan checks your claims history through ClaimSearch. If you have three or more property claims in the past seven years, your premium jumps significantly, and in some cases you get screened out entirely. Step two is photographing your roof and exterior from ground level. I send those images ahead with the application. Agents on the Fair Plan side sometimes flag applications for reinspection, and having those photos already attached cuts that delay by about two weeks. The actual online application takes roughly forty minutes. You'll need your tax parcel number, your legal address, square footage of your home, year built, roof type, and whether the property has a pool or trampoline. The system auto-populates a lot of this from county assessor data, but the assessor's square footage is often wrong. I always verify it myself. One client had twenty-two square feet missing from the county record, which shifted her classification from a two-story to a one-story rating tier and dropped her annual premium by about three hundred dollars.
What Fair Plan actually covers
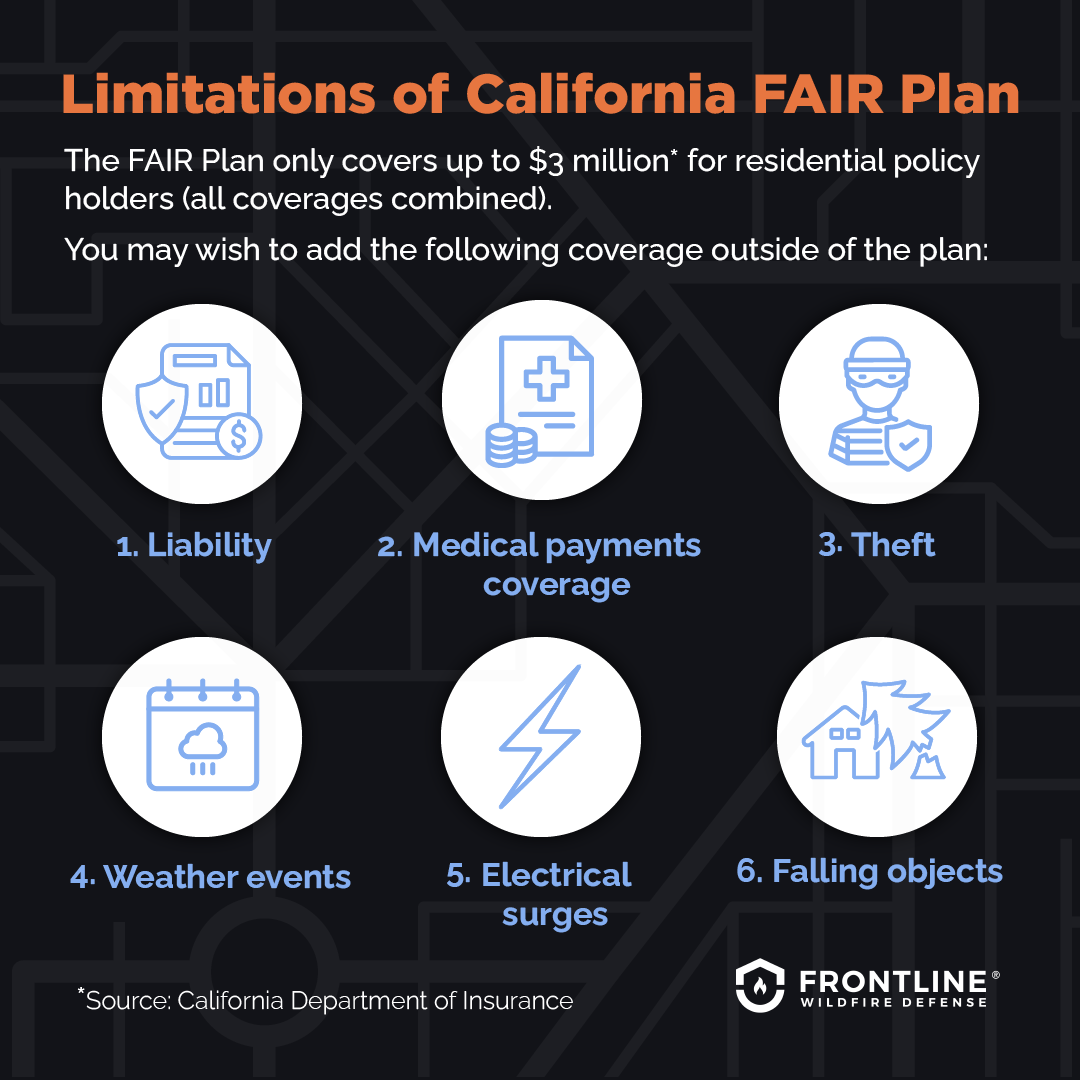
The dwelling coverage is written on a replacement cost basis, not actual cash value. That matters. Replacement cost pays what it takes to rebuild with similar materials at current prices. Actual cash value depreciates everything. Fair Plan defaults to replacement cost for dwellings, but the personal property portion is actual cash value unless you elect replacement cost coverage, which adds roughly eight to twelve percent to your premium. Liability coverage is available but limited. You can add personal liability up to five hundred thousand dollars. It costs around ninety-five dollars per year. Most people skip it because they carry homeowner's liability through a different policy or rely on umbrella coverage. That is fine as long as your umbrella policy explicitly accepts Fair Plan as an underlying carrier. I learned this the hard way with a client whose umbrella had a trailing clause requiring a standard HO-3 as the base policy. She filed a liability claim and the umbrella carrier denied it, citing non-conforming underlying coverage. We ended up paying the legal defense out of pocket.
Get the Full Details
Common pitfalls and workarounds
The biggest mistake I see is assuming Fair Plan premiums are cheap. They are not. A modest three-bedroom home in a moderate fire zone will run between four and seven thousand dollars annually. That feels high until you compare it to the zero percent availability rate some carriers quote for the same zip code. Another issue is the deductible structure. Fair Plan uses a straight deductible expressed as a percentage of your dwelling coverage amount. A one percent deductible on a three hundred thousand dollar dwelling means you are responsible for the first three thousand dollars on any claim. Some policyholders pick a three percent deductible to lower their premium, then forget about it until they file a claim for minor wind damage and get stung. I recommend sticking with one or two percent and keeping the cash reserve you would have saved for the higher deductible. Here is a specific edge case that took me months to resolve. A client had a secondary structure — a detached workshop — that measured fourteen hundred square feet. The fair plan application asked about "attached structures" only, and the workshop was not clearly addressed in the system. She submitted without it, got approved, and then had a fire loss where the workshop was totaled. The claim adjuster denied the workshop portion outright because it was never scheduled on the policy. We had to reopen the account, add the structure, and negotiate a partial payment using a loss payee letter. The whole process took eleven months. My workaround now is to inventory every structure on the property, including sheds over fifty square feet, fences longer than twenty feet, and detached garages, and list them all on the application even if the form doesn't explicitly ask for them. The underwriter will call if there is a discrepancy, and it is faster to address it upfront.
How to file a claim
Fair Plan handles claims differently than standard carriers. You file through their dedicated claims line, not through a third-party administrator. The initial adjuster assignment typically happens within five business days for fire claims and ten to fourteen days for other perils. Response time is slower than private carriers because the adjuster pool is smaller. During the 2024 canyon fire complex, average first contact waited three weeks in some regions. When you file, have your policy number, the date of loss, and a written timeline ready. Do not throw away damaged items before the adjuster inspects them. I have seen policyholders dump debris into a dumpster because they assumed Fair Plan would reimburse disposal costs. They did not. The policy covers the damage, not the cleanup, unless you separately purchase debris removal coverage, which costs about sixty-five dollars additional per year and covers up to ten percent of the claim amount.
When Fair Plan is the right choice and when it is not
Fair Plan makes sense when you live in a high-fire severity zone, your home is older construction, or your area has limited carrier participation. It also works if you have a clean claims history and are willing to accept named-perils coverage in exchange for actual insurability. It is a poor choice if you are looking for comprehensive coverage, if you need earthquake insurance bundled in, or if your home has significant deferred maintenance. Fair Plan does conduct inspections on high-value policies, and if your property fails the inspection you may be required to make repairs before coverage is issued or maintained. One client in Sonoma County had peeling exterior paint and an unpermitted addition. They were told they had sixty days to address both issues or the policy would be cancelled. He chose to sell the property instead. The alternative pathway is seeking a standard homeowner's policy through a specialty surplus lines carrier. These policies cost more but include broader perils and often bundle earthquake coverage. I typically recommend this route for homes valued above six hundred thousand dollars where the premium difference between Fair Plan and a standard policy is under fifteen percent. Below that threshold, Fair Plan usually remains the more economical option simply because the alternatives are scarce.
Application and documents checklist
You will need your tax parcel number, the legal property description from your deed, square footage verified against your tax assessment, roof material and age, and whether the property has undergone any additions or remodels in the last ten years. If you have prior insurance, bring your cancellation or nonrenewal letter. Fair Plan does not require it, but having it speeds up the underwriting review. The application portal is located at fairplan.ca.gov. Processing typically takes seven to ten business days for standard applications. Expedited processing is available for policies in areas with active fire danger warnings, but that requires a letter from your local fire district confirming elevated risk. I have used this route during red flag warnings and received approvals in four business days instead of the usual two weeks.
Ongoing policy management
Review your coverage annually. Fair Plan allows endorsements for water damage, equipment breakdown, and identity theft protection. None of these are necessary for basic coverage, but the equipment breakdown endorsement costs about forty dollars per year and covers mechanical failure of your HVAC system, which is a common claim source in rural properties where systems run harder due to temperature extremes. Keep your contact information current. Fair Plan sends renewal notices by mail, not email. If you move or change your address and miss the renewal notice, your policy lapses thirty days after the expiration date with no grace period. A lapse means you have to reapply, which resets your processing time and potentially your rating tier.