Understanding Allstate Business Insurance: What It Actually Covers and Where It Falls Short
Allstate offers a range of commercial insurance products designed for small to medium-sized businesses. The core offering typically includes general liability, commercial property, business personal property, business income coverage, and optional add-ons like cyber liability, professional liability, and commercial auto. They position it as a bundled solution called the Allstate Business Insurance Bundle, which is meant to simplify purchasing by combining several coverages under one policy. I spent several years working with commercial insurance carriers before moving into a consulting role, and the thing about Allstate's business line that trips people up is the gap between what the marketing says and what the policy language actually delivers. Their bundling discounts are real, but so are the hidden exclusions that only show up when you read the actual declarations page instead of relying on the agent summary sheet.
Protect Your Business A Comprehensive Guide To Allstate Business Insurance
Getting covered through Allstate starts with identifying your business type and size. Allstate defines small business as typically having under $5 million in annual revenue and fewer than 100 employees, though some policies extend beyond that threshold. You will need basic information ready: your business entity type, approximate payroll, square footage of your premises, equipment values, and any prior claims history going back five years. The quoting process happens primarily through their online platform or through a local Allstate agent. The online route tends to give you a baseline premium estimate within ten to fifteen minutes, but it will almost always recommend connecting with an agent before binding coverage. That is not a sales tactic as much as it is a genuine limitation. Allstate's automated underwriting engine flags certain risk indicators that require manual review, and if your business has anything non-standard — contractors, vehicles, high-value equipment, or a physical location in a flood zone — the system will pause the quote anyway. One specific detail most people miss is the difference between Allstate's standard commercial general liability form and their modified forms. The standard CGL form uses the completed operations hazard trigger, which means claims filed after your policy expires may or may not be covered depending on when the incident occurred versus when the damage manifested. I ran into this directly with a client who switched carriers mid-year. They had a CGL policy with Allstate for three years, switched to a different carrier, and then eighteen months later a subcontractor's work from year two was called into question. Allstate's policy had an endorsement that limited completed operations coverage to twelve months after the work was finished, not the standard two-year lookback. The new carrier's policy had a different trigger. We ended up filing a claim under both policies' extended reporting periods and spent about six weeks coordinating between the two adjusters just to establish primary versus excess responsibility. That whole situation could have been avoided by reading the actual policy form, not just the summary booklet.
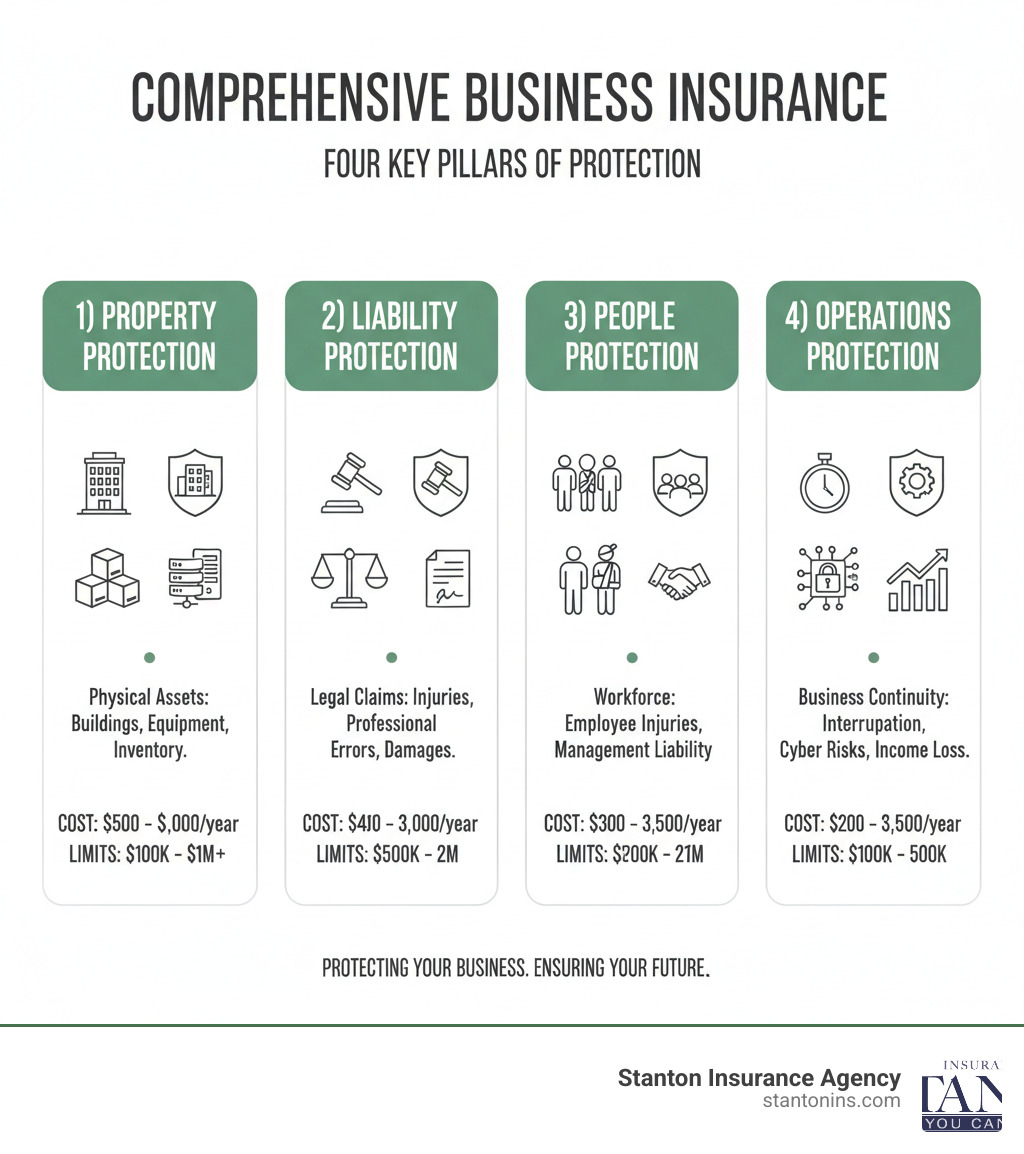
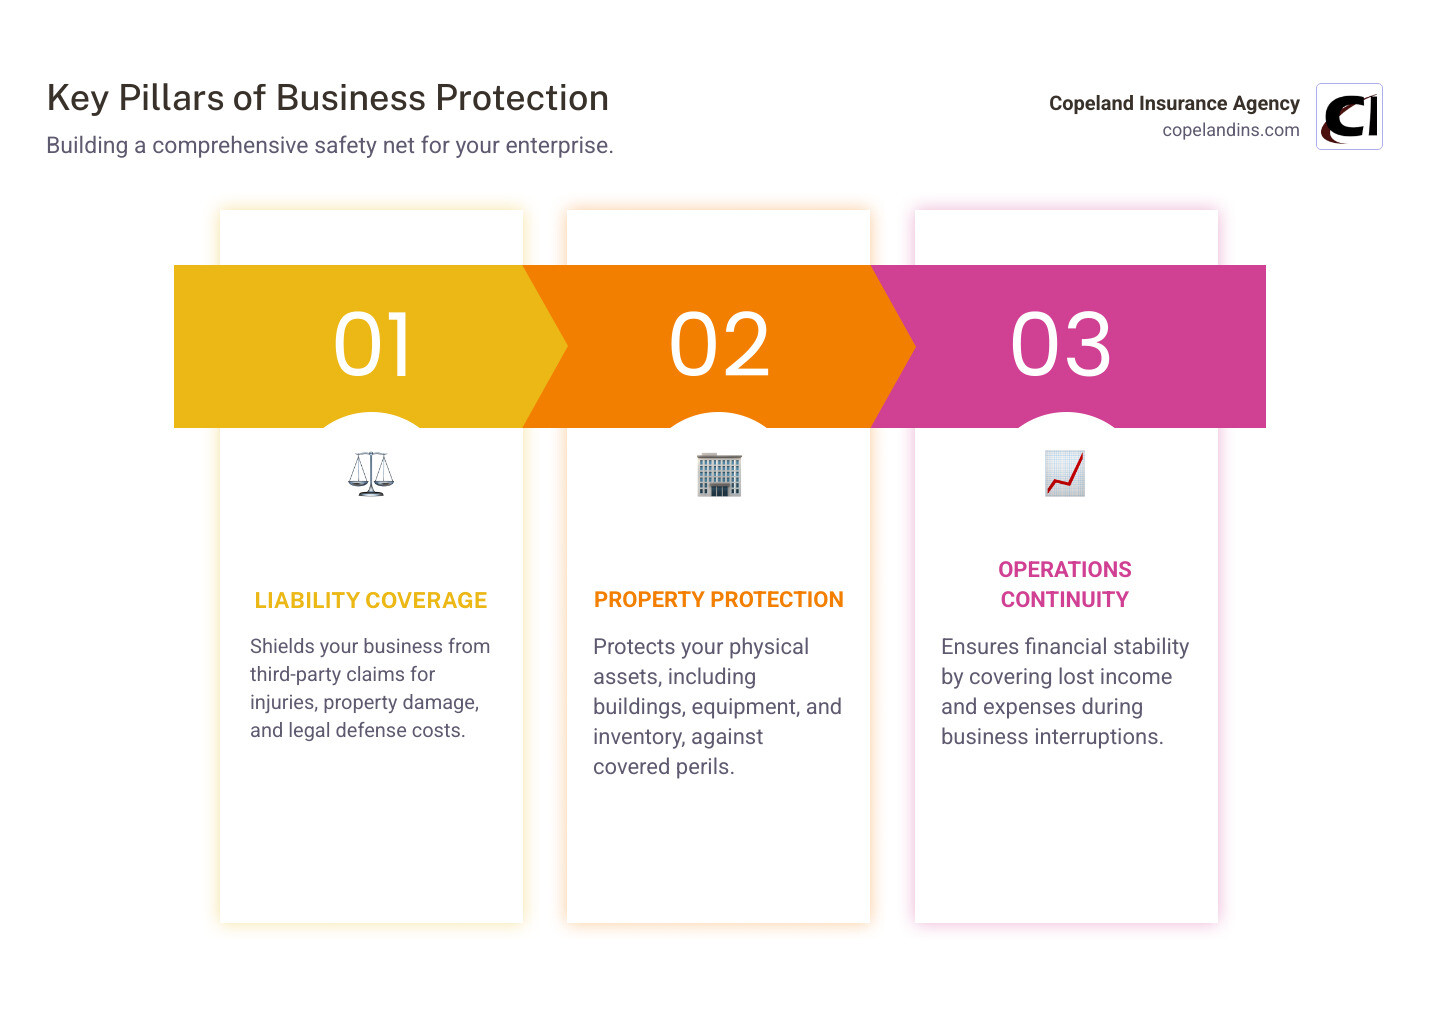
When it comes to actual coverage terms, here is what you need to understand about the main components. General liability typically covers third-party bodily injury, property damage, and personal injury like slander or false advertising. The per-occurrence limit is the maximum Allstate will pay for a single claim, while the aggregate limit is the total maximum for the policy period. Most small business policies start at $1 million per occurrence with a $2 million aggregate, but you can go higher. The important thing is that these limits apply across all covered incidents, so a single severe claim can eat into your aggregate quickly if you are not careful. Commercial property coverage is more nuanced than it appears on the surface. Allstate offers actual cash value and replacement cost options. Actual cash value factors in depreciation, which means a five-year-old roof on your business property might only pay out at a fraction of what it costs to replace. Replacement cost is better but costs more. I had a restaurant client who took the ACV option to save about two hundred dollars annually on their premium. When a kitchen fire damaged their ovens and ventilation system, the payout covered maybe thirty percent of the replacement cost. They ended up spending nearly eighteen thousand dollars out of pocket. The premium savings were irrelevant by comparison. Business income coverage — sometimes called business interruption — is another area where people misunderstand what they are buying. This coverage replaces lost income when your business cannot operate normally after a covered property loss. The key word is after. It does not cover losses from economic downturns, supply chain disruptions, or pandemic-related closures. The coverage period is limited to the time it would reasonably take to repair or rebuild your premises, typically capped at twelve to twenty-four months depending on the endorsement you select. Some policies have a waiting period of forty-eight hours before coverage kicks in, which means the first two days of lost revenue are entirely on you.
Get the Full Details
Allstate also offers a separate cyber liability policy, but it is important to understand what it excludes. Like most standard cyber policies in this market, it does not cover pre-existing breaches, losses from unpatched software vulnerabilities that you knew about but did not fix, or business interruption caused by a vendor's breach rather than your own. I once worked with a client who assumed their Allstate cyber policy would cover a ransomware incident. It did not, because the investigation revealed their antivirus software had been disabled for six months due to a compatibility issue with their accounting program. The denial letter cited the maintenance neglect exclusion explicitly. After that incident, I always recommend clients run a quarterly security audit and keep documentation. It is not fun administrative work, but it is the difference between a claim being paid and a claim being denied.
Common Pitfalls and How to Avoid Them
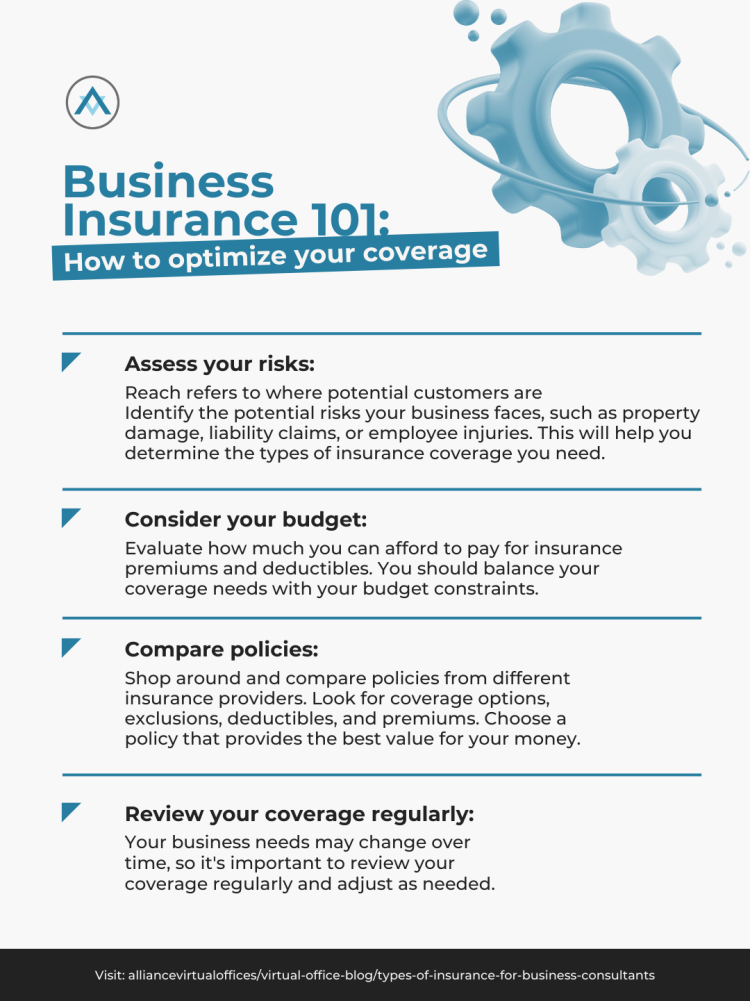
The most common mistake I see is underinsuring. People look at the premium and try to minimize it by lowering limits or increasing deductibles across the board. This is backwards thinking. A $500 deductible on a $500,000 general liability policy sounds reasonable until you are defending a lawsuit where the legal fees alone exceed that amount. Allstate's own data on small business claims shows that the average liability claim for businesses with under $1 million in revenue runs between $75,000 and $150,000 when medical costs and legal fees are included. A higher deductible might save you a few hundred dollars a year, but it exposes you to significant out-of-pocket risk on every claim. Another frequent issue is the inventory of business personal property. Allstate requires you to schedule your equipment, tools, and inventory with approximate values. Many business owners skip this step or grossly underestimate. When a fire or theft occurs, the adjuster will look at your scheduled values and pay based on those figures, not on what it actually cost to replace everything. If you bought $200,000 worth of equipment over the past three years and only listed $50,000 on your policy, you will receive a fraction of the actual loss. I recommend taking a photo inventory every January with serial numbers and purchase estimates, and updating it annually. It takes about ninety minutes and prevents a hundred thousand dollars in coverage gaps. Workers compensation is handled separately in most states and Allstate does not write it in all jurisdictions. If you have employees, you will likely need a separate workers comp policy or a combined package that includes it. Premiums for workers comp are based on your payroll and your classification codes, which determine your industry risk level. A coding error here can cost you significantly — either in overpayment during good years or in a massive audit bill during a claims review. I have seen small contractors get hit with retroactive premiums exceeding $20,000 after an audit reclassified their work to a higher-risk category. Always verify that your classification codes match your actual operations, not just the default suggestions Allstate's system generates.
When Allstate Might Not Be the Right Fit
Allstate is a solid option for straightforward small business insurance needs. If you run a retail shop, a professional services firm, or a light manufacturing operation with standard risks, their bundling discounts and established claims process are competitive. But there are scenarios where their standard products will not serve you well. High-risk industries — construction contractors with significant subcontractor exposure, restaurants with extensive liquor service, medical practices, or businesses with international operations — often need specialized policies that Allstate's standard commercial lines do not adequately cover. In these cases, you are better off looking at specialty carriers like Chubb, Hartford, or a surplus lines broker who can place coverage on the excess and surplus market. Allstate's underwriting guidelines for these categories tend to be conservative, which means they may decline coverage altogether or offer it with restrictive endorsements that leave real gaps. There is also the matter of claims handling quality, which varies significantly by region. Allstate uses a combination of staff adjusters and independent adjusters depending on your location. In some markets, their response times and settlement offers are comparable to or better than competitors. In others, policyholders report delays of sixty to ninety days on straightforward property claims and aggressive negotiation on liability settlements. I cannot give you a definitive map of which offices perform well and which do not, but I can tell you that checking your state's insurance department complaint ratios and reading recent policyholder reviews for your specific region is worthwhile before committing.

The bottom line is that Allstate Business Insurance is a legitimate option for many small business owners, but it is not a one-size-fits-all solution. The discounts for bundling are real, the online quoting process is convenient, and their financial strength ratings are strong. But the policy details matter more than the price, and the gaps in standard coverage can become expensive if you do not read the actual policy forms carefully before signing. Budget at least an hour to review your declarations page and every endorsement attached to it, and if anything is unclear, ask for the full policy wording rather than accepting the summary. Most people regret skipping that step.