How Banco Del Bienestar Cards Get Compromised and What Actually Works
I've been dealing with fraud issues on Mexican government-issued cards for years. Banco Del Bienestar isn't a different bank in any meaningful sense—it's just one of the many institutions the Mexican government uses to distribute social programs. The fraud vectors are the same ones hitting every debit and prepaid card out there. What matters is understanding how the attacks work and what barriers actually stop them. The most common way these cards get drained isn't through elaborate hacking. It's card skimming at point-of-sale terminals and phishing scams that target people who already have low digital literacy. Here's what happens in practice. A person goes to a local store or a cash advance kiosk to withdraw their weekly benefit amount. The merchant runs the card through a modified terminal that clones the magnetic stripe or captures the chip data. By the time the cardholder notices a discrepancy, the money is already gone and the cloned card has been used elsewhere. These operations move fast. They often target neighborhoods where Banco Del Bienestar clients gather, which means the fraud is concentrated and repeatable.
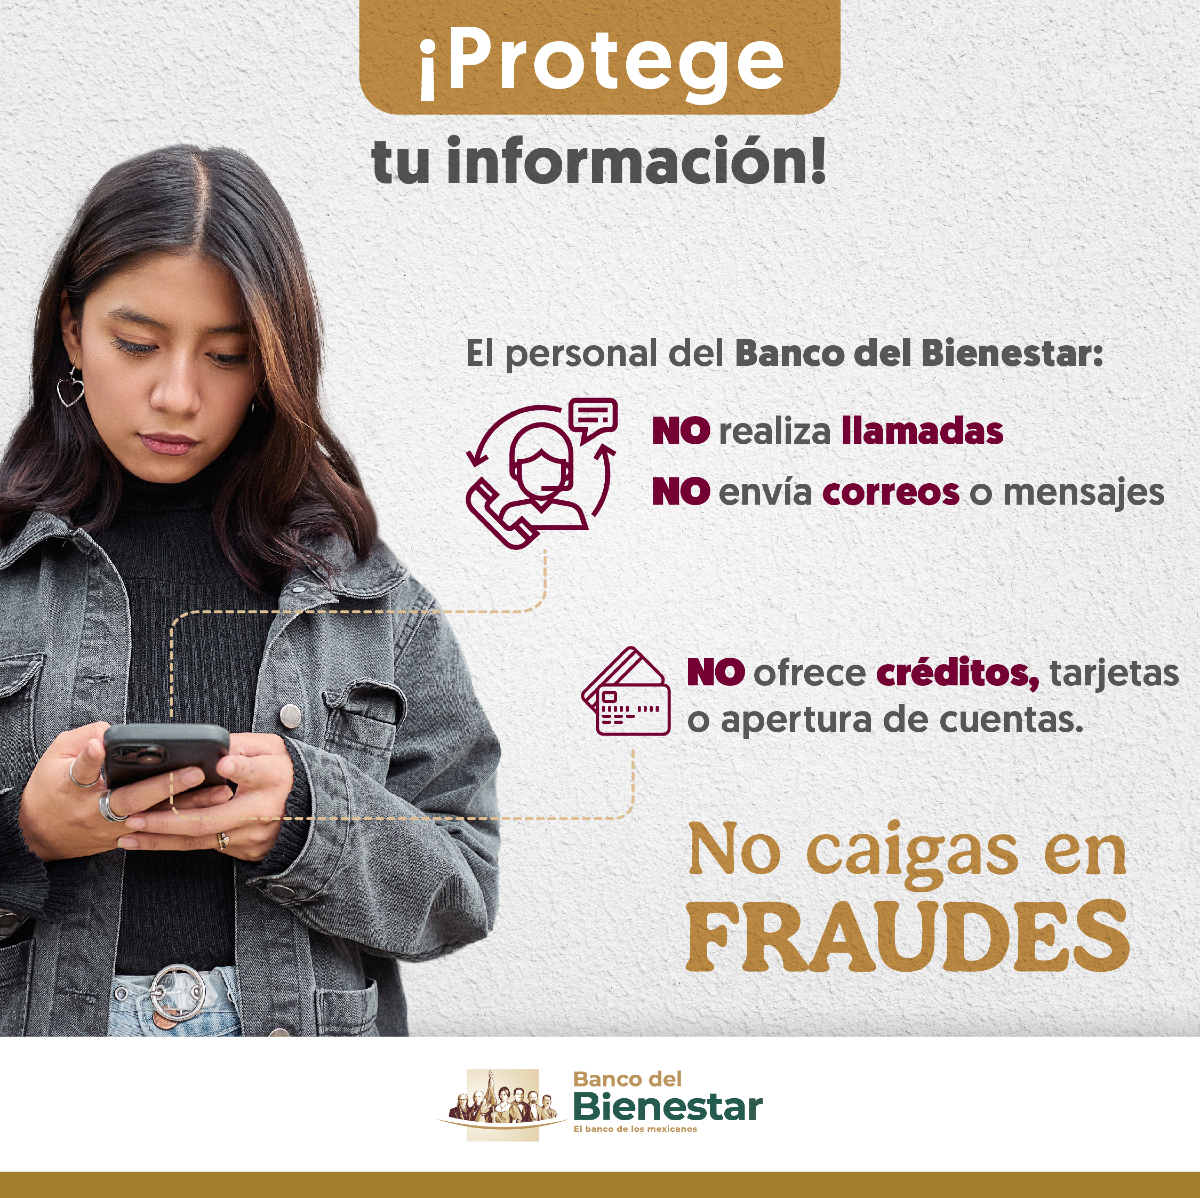
The second vector is SMS phishing. Someone receives a message that looks like it's from the bank saying your card has been blocked and you need to verify your information by clicking a link. They click it. They enter their card number, their PIN, sometimes even their CURP. The fraudulent operator now has everything needed to drain the account. This happens constantly because the messages are well-crafted and the urgency feels real. Here's the practical method I recommend and use: Turn on transaction alerts immediately. Banco Del Bienestar's app and their customer service line allow you to register for push notifications or SMS alerts on every transaction above a threshold you set. I set mine to alert on any transaction over one peso. Yes, that sounds extreme. But a one-peso alert means you see movement the second it happens instead of discovering a gap three days later. This cuts the time between unauthorized access and freezing your account from potentially 72 hours to under 15 minutes.
Set your card to a daily withdrawal limit that matches your actual needs. If your weekly benefit is roughly $1,500 to $2,500 pesos depending on the program, set your daily ATM limit to something slightly above what you'd realistically need in a single day. Most people don't need more than $500 in one trip. Anything higher and you're leaving excess money accessible to anyone who compromises your PIN. You can adjust this limit through the app or at any Banco Del Bienestar branch. The change takes effect within minutes. Use only the official app and the official website. There are counterfeit banking apps on third-party app stores that look identical to the real thing. I've seen at least two versions circulate on APK download sites. They harvest login credentials the moment you enter them. Always verify the app is from the official Banco Del Bienestar developer account and check the URL carefully. The real site ends in gob.mx. Anything else is not trustworthy. When you withdraw cash, shield your PIN entry. I know this sounds obvious, but I've watched people enter their four-digit PIN at outdoor ATMs without covering the keypad while strangers stand directly behind them. Some of these are professional PIN spotters who work in teams with skimmers. The combination of both tools gets you locked out of your money within hours.
Get the Full Details

Here's a specific edge case I encountered that most guides won't cover: Last year, a client of mine reported that their card was being declined at a legitimate merchant, but when they tried to use it at an ATM, the transaction went through. The card wasn't cloned—the magnetic stripe and chip data were intact. What was happening is the card had been flagged for suspicious activity by the bank's fraud detection system, but the flag wasn't propagating to all channels instantly. The ATM network processes transactions with different latency than the merchant payment network. By the time the fraud team reviewed the flagged transaction and cleared it, the ATM had already processed several withdrawals using the same card because the system hadn't synced the block yet. The workaround was straightforward but only after I understood the internal processing delays. I called the fraud line and explicitly asked them to place a full card freeze, not just a transaction hold. A hold lets the card remain partially active across channels. A freeze locks every channel simultaneously. Once they confirmed the freeze was active, the fraud stopped. I then requested a replacement card with a new number, which took about five business days to arrive at the designated pickup location.
Counter-intuitive insight that most people miss: Changing your PIN regularly does not significantly reduce fraud risk unless you suspect the current PIN is compromised. What actually reduces risk is making your PIN unpredictable in the first place. People who use birthdates, sequential numbers like 1234, or repeating digits like 1111 are far more vulnerable because those combinations are easy to guess through social engineering or brute force. I've seen PINs written on sticky notes attached to the card itself. That defeats every other security measure you put in place. Another thing beginners consistently overlook: the CVV and expiration date printed on the card front. If someone photographs your card, they have two of the three critical pieces of information needed for online fraud. Even if your card doesn't support online purchases, some merchants can still attempt card-not-present transactions with just the number and CVV, especially on systems with weaker verification. Cover the CVV with opaque tape if you're concerned about this. It's a small inconvenience that blocks a real attack vector. Limitations I want to be honest about:
The Banco Del Bienestar fraud detection system is not as sophisticated as what major commercial banks offer. It lacks real-time machine learning-based anomaly detection, geographic velocity checks, and device fingerprinting. When fraud does occur, the resolution process can take anywhere from 3 to 14 business days depending on the complexity and the branch handling your case. There's no instant chat support. You either call the fraud hotline, visit a branch in person, or use the app's contact form, which has significant response delays. If you need immediate card replacement, plan on waiting at least a week for a new card to arrive at your assigned pickup point. Another limitation is that the app sometimes fails to send transaction alerts due to server issues or poor mobile coverage in certain regions. I've personally experienced missed alerts during peak hours when multiple users in a municipality were accessing the system simultaneously. During these outages, your only option is to manually check your balance through the app or by calling customer service. This means you might not catch fraud the moment it happens even if alerts are supposed to be active. If you find the bank's own security measures insufficient, your best alternative is to treat the card like a prepaid debit card rather than a full checking account. Keep only one week's benefit on the card at a time. Set your daily limit accordingly. If the card gets compromised, the maximum loss is limited to whatever amount remained on it during the exposure window. Don't deposit extra personal funds onto this card. The fraud systems are optimized for government benefit disbursement, not for protecting supplementary balances.

What to do if you discover fraud on your card: Don't wait. Call the fraud hotline immediately and request a full freeze. Then file a formal complaint at your nearest Banco Del Bienestar branch with a written record. Ask for a case number and the name of the agent who took your report. Keep screenshots of every transaction you recognize as unauthorized. Send these to the fraud team as supporting documentation. The bank will typically reverse fraudulent transactions within 30 to 45 business days, but having a paper trail speeds up the review and gives you grounds to escalate if the process stalls. Also notify your local consumer protection authority in Mexico. The CONDUSEF handles complaints against financial institutions and can intervene when the bank's internal process is too slow. Having a CONDUSEF complaint on file often prompts the bank to prioritize your case.
The reality is straightforward. Banco Del Bienestar cards serve a vulnerable population that scammers target precisely because these clients may not have the resources or knowledge to fight fraud effectively. The steps above are not theoretical. They are the ones that work in practice. Start with transaction alerts and withdrawal limits. Those two changes alone will prevent the majority of losses. Everything else is incremental defense layered on top of that foundation.


